Opinion / Op-Ed
Gen Z AI Skills: Online Degrees That Boost Job Prospects

For Gen Z, artificial intelligence has transformed the question of education.
The question is no longer simply:
“What degree should I get?”
It has become:
“What degree gives me skills that remain valuable when AI changes the job?”
That distinction is becoming increasingly important as AI moves into recruitment, marketing, finance, software development, customer service and administration.
The AI-Proof Degree Myth
No degree is completely AI-proof.
Instead, students should look for combinations of:
- Technical literacy
- Analytical skills
- Communication
- Domain expertise
- Problem solving
- Human judgment
A degree becomes more valuable when it is combined with practical AI skills.
Online Degrees Can Offer Flexibility
Online education allows students to study while working or building a business.
That can be particularly useful for Gen Z workers who don’t want to leave the workforce for four years.
Potentially attractive fields include:
| Degree Area | AI Relevance | Career Flexibility |
|---|---|---|
| Computer Science | Very high | High |
| Data Analytics | Very high | High |
| Cybersecurity | Very high | High |
| Business Analytics | High | High |
| Finance | High | High |
| Marketing | High | High |
| Healthcare Administration | Medium-high | Medium-high |
| Project Management | High | High |
Why Business + AI Is Powerful
Not every student needs to become a programmer.
Businesses need people who understand how technology affects:
- Operations
- Customers
- Revenue
- Employees
- Risk
- Strategy
That’s why combinations such as business analytics, information systems and technology management can be attractive.
Don’t Choose a Degree Based on Salary Alone
A high advertised salary does not automatically mean high ROI.
Calculate:
Expected earnings − tuition − financing cost − opportunity cost
Then consider:
- Graduation rate
- Program reputation
- Employer demand
- Internship access
- Curriculum
- Career services
- Flexibility
The New Education Formula
The strongest combination may be:
Degree + AI literacy + portfolio + internship + communication skills
A degree gets you through some doors.
Demonstrable ability gets you further.
Bottom Line
Gen Z should not ask whether AI makes university irrelevant.
The better question is whether an education program helps students become better at working with AI.
The strongest online degrees will increasingly be those that combine domain expertise with technology, analytics and practical experience.
People Also Ask
What degree is best for AI careers?
Computer science, data science, analytics and related technology fields are strong options, but many nontechnical degrees can also benefit from AI specialization.
Are online degrees worth it?
They can be, provided the institution, program quality, cost and career outcomes justify the investment.
Will AI replace business degrees?
AI may automate some business tasks, but management, strategy, communication and decision-making remain important.
Economy & Markets
Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation
Gasoline rose 3.9% in August and drove over a third of the CPI increase. Inside the crude-to-pump-to-CPI chain and what it means for the next Fed decision.There is a clean, traceable chain running from a Saudi pipeline to a Bureau of Labor Statistics table, and August 2026 is the cleanest illustration of it in years.
Executive Summary / Key Takeaways
- The August 2026 CPI, released 11 September, showed the all-items index up 0.4% on the month and 3.4% over twelve months.
- The gasoline index rose 3.9% in August, accounting for over one third of the entire monthly all-items increase. Energy overall rose 2.1% after falling 1.5% in July.
- Year-on-year, gasoline was up 27.4% and fuel oil up 52%, while energy as a whole rose 16.3%.
- Core CPI, excluding food and energy, rose 0.3% on the month but slowed to 2.4% annually — the lowest reading since March 2021.
- The divergence is the signal: headline inflation is being generated almost entirely by energy while underlying price pressure cools. That is the precise configuration that makes a supply-shock tightening cycle contentious.
The Consumer Price Index rose 0.4% month-on-month in August, meeting consensus, and held at 3.4% on a twelve-month basis, per TD Economics. Energy costs rose 2.1% monthly, led by a 3.9% gain in gasoline. Food rose a subdued 0.1% for a second consecutive month and is up 2.7% over the year. Excluding food and energy, core prices rose 0.3% monthly — a tick hotter than expectations — while the twelve-month core rate edged down to 2.4%, with the three-month annualised at a softer 2.0%.
The BLS itself flagged the concentration: the gasoline index accounted for over one third of the monthly all-items increase.
2. Core Analysis: The Transmission Chain
2.1 August CPI in detail
| Component | Monthly change | Annual change | Note |
|---|---|---|---|
| All items | +0.4% | +3.4% | Strongest monthly rise in three months |
| Core (ex food & energy) | +0.3% | +2.4% | Lowest annual reading since March 2021 |
| Gasoline | +3.9% | +27.4% | Over one-third of the monthly headline increase |
| Energy (all) | +2.1% | +16.3% | After -1.5% in July |
| Fuel oil | +10.1% | +52.0% | Sharpest annual move in the report |
| Electricity | -0.2% | +3.8% | Declined monthly |
| Natural gas | -1.1% | — | Declined monthly |
| Shelter | +0.3% | +3.0% | Eased from 3.2% |
| Food | +0.1% | +2.7% | Eased from 3.0% |
| Airline fares | +2.7% | — | Fuel pass-through visible |
Data compiled from the BLS release, Trading Economics and Fox Business reporting.
2.2 Crude to pump to CPI
The chain has three links and a measurable lag at each.
Crude to pump. Crude is the largest single cost in a gallon of gasoline, and pump prices generally track WTI and Brent with a one-to-two week lag. WTI has traded near $103 and Brent near $107, following Houthi attacks that shut a crucial Saudi crude pipeline bypassing the Strait of Hormuz.
Pump to CPI. The BLS surveys consumer prices up to the previous month, so the August report published on 11 September reflects August pump prices — which averaged well below the $4.329 recorded on 15 September, per AAA data. Real-time retail fuel readings therefore lead the gasoline index by roughly four to six weeks.
CPI to policy. The August report showed inflation remaining elevated on rising energy prices, which Vanguard senior economist Josh Hirt said made a September rate hike more likely, per Fox Business. The Fed hiked on 16 September.
That is the full loop, and it took roughly six weeks from pipeline to policy decision.
2.3 Why headline and core diverged
Core inflation falling to 2.4% — its lowest since March 2021 — while headline holds at 3.4% is the most consequential detail in the release, and most coverage buried it.
Core below headline means energy is the primary driver and underlying price pressures are cooling. Shelter, the largest single CPI component, rose a comparatively modest 0.3% monthly and 3.0% annually, elevated historically but not accelerating the way energy is, per analysis of the release. Used vehicle prices are essentially flat year-on-year at +0.4% and new vehicles up only 0.6%, meaning that outside gasoline, transportation is not an inflation driver at all.
Headline is also well off its peak. The 3.4% annual rate is down from the April 2026 peak of 4.2%.
3. Structural Drivers and Competitor Gaps
Retail fuel telemetry as a leading indicator. Because CPI surveys lag by a month and publishes with a further delay, real-time pump-price data is genuinely predictive of the gasoline index — the single most volatile and most headline-relevant CPI component. With national averages running above $4.30 in mid-September against August levels, the September CPI due 14 October carries upside risk on the energy line before any other factor is considered.
The second-round question. Because energy costs feed into shipping, manufacturing and agriculture, economists watch a spike like this for early signs it will appear in core figures in following months. August’s evidence is mixed: core services rose 0.3% monthly on a sharp acceleration in non-housing services (+0.6%), which is where energy pass-through would first appear, even as annual core fell. Airline fares up 2.7% monthly is the cleanest visible pass-through in the report.
The policy disagreement this creates. Treasury Secretary Scott Bessent argued that the Fed typically does not raise rates during a supply shock until second- or third-order inflationary effects appear. The August data is genuinely ambiguous on whether those effects have arrived — annual core at a five-year low argues no; non-housing services acceleration argues possibly. Both sides of the September policy debate could cite this release honestly.
What households actually experience. Gasoline and fuel oil increases hit budgets immediately and visibly at every fill-up, rather than in a monthly bill. A 27.4% annual gasoline increase compounding already-elevated shelter costs means many households are absorbing higher costs on two of their largest monthly expenses at once — which is why consumer inflation expectations track headline rather than core, and why the Fed cannot simply look through energy.
Where the forecasts failed. GasBuddy’s pre-conflict outlook projected a 2026 national average of $2.97 a gallon. The actual reading is $4.329. Any inflation model built in late 2025 embedded an energy assumption that missed by roughly $1.35 a gallon, which is most of the gap between forecast and realised headline CPI this year.
4. Key Implications for Stakeholders
Economists and forecasters. Model headline and core separately and weight retail fuel telemetry into the near-term headline path. The September CPI on 14 October is the key test of whether August’s gasoline spike is sustained or reversed.
Inflation trackers. The 3.4% headline is not a signal of broad-based inflation. Strip energy and the picture is a 2.4% core running at a 2.0% three-month annualised pace — close to target. The economy has an energy problem, not a generalised inflation problem.
Retail traders. Watch Saudi East-West pipeline restoration. The kingdom indicated it could restore around half of capacity within days and full operations within six weeks. A confirmed restoration would remove the dominant CPI driver within one to two print cycles.
Households and budgeters. The gap between headline and core explains why official inflation feels understated: energy and shelter, the two most visible household costs, are both running above the core rate.
5. Frequently Asked Questions
Q1: What was the August 2026 inflation rate?
The CPI rose 0.4% month-on-month and 3.4% over twelve months, unchanged from July and down from the April 2026 peak of 4.2%. Core CPI rose 0.3% monthly and 2.4% annually.
Q2: How much did gasoline contribute to inflation?
The gasoline index rose 3.9% in August, accounting for over one third of the entire monthly all-items increase, and is up 27.4% year-on-year. Energy overall rose 2.1% monthly and 16.3% annually.
Q3: Why is core inflation lower than headline inflation?
Because energy is driving the headline figure while underlying pressures cool. Core CPI, which excludes food and energy, fell to 2.4% annually — the lowest since March 2021 — with shelter easing to 3.0% and vehicle prices essentially flat.
Q4: When is the next CPI report?
The September 2026 CPI is scheduled for release on Wednesday, 14 October 2026 at 8:30 a.m. ET. It will show whether the August gasoline spike was sustained.
Free Trade Area (FTA)
China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific
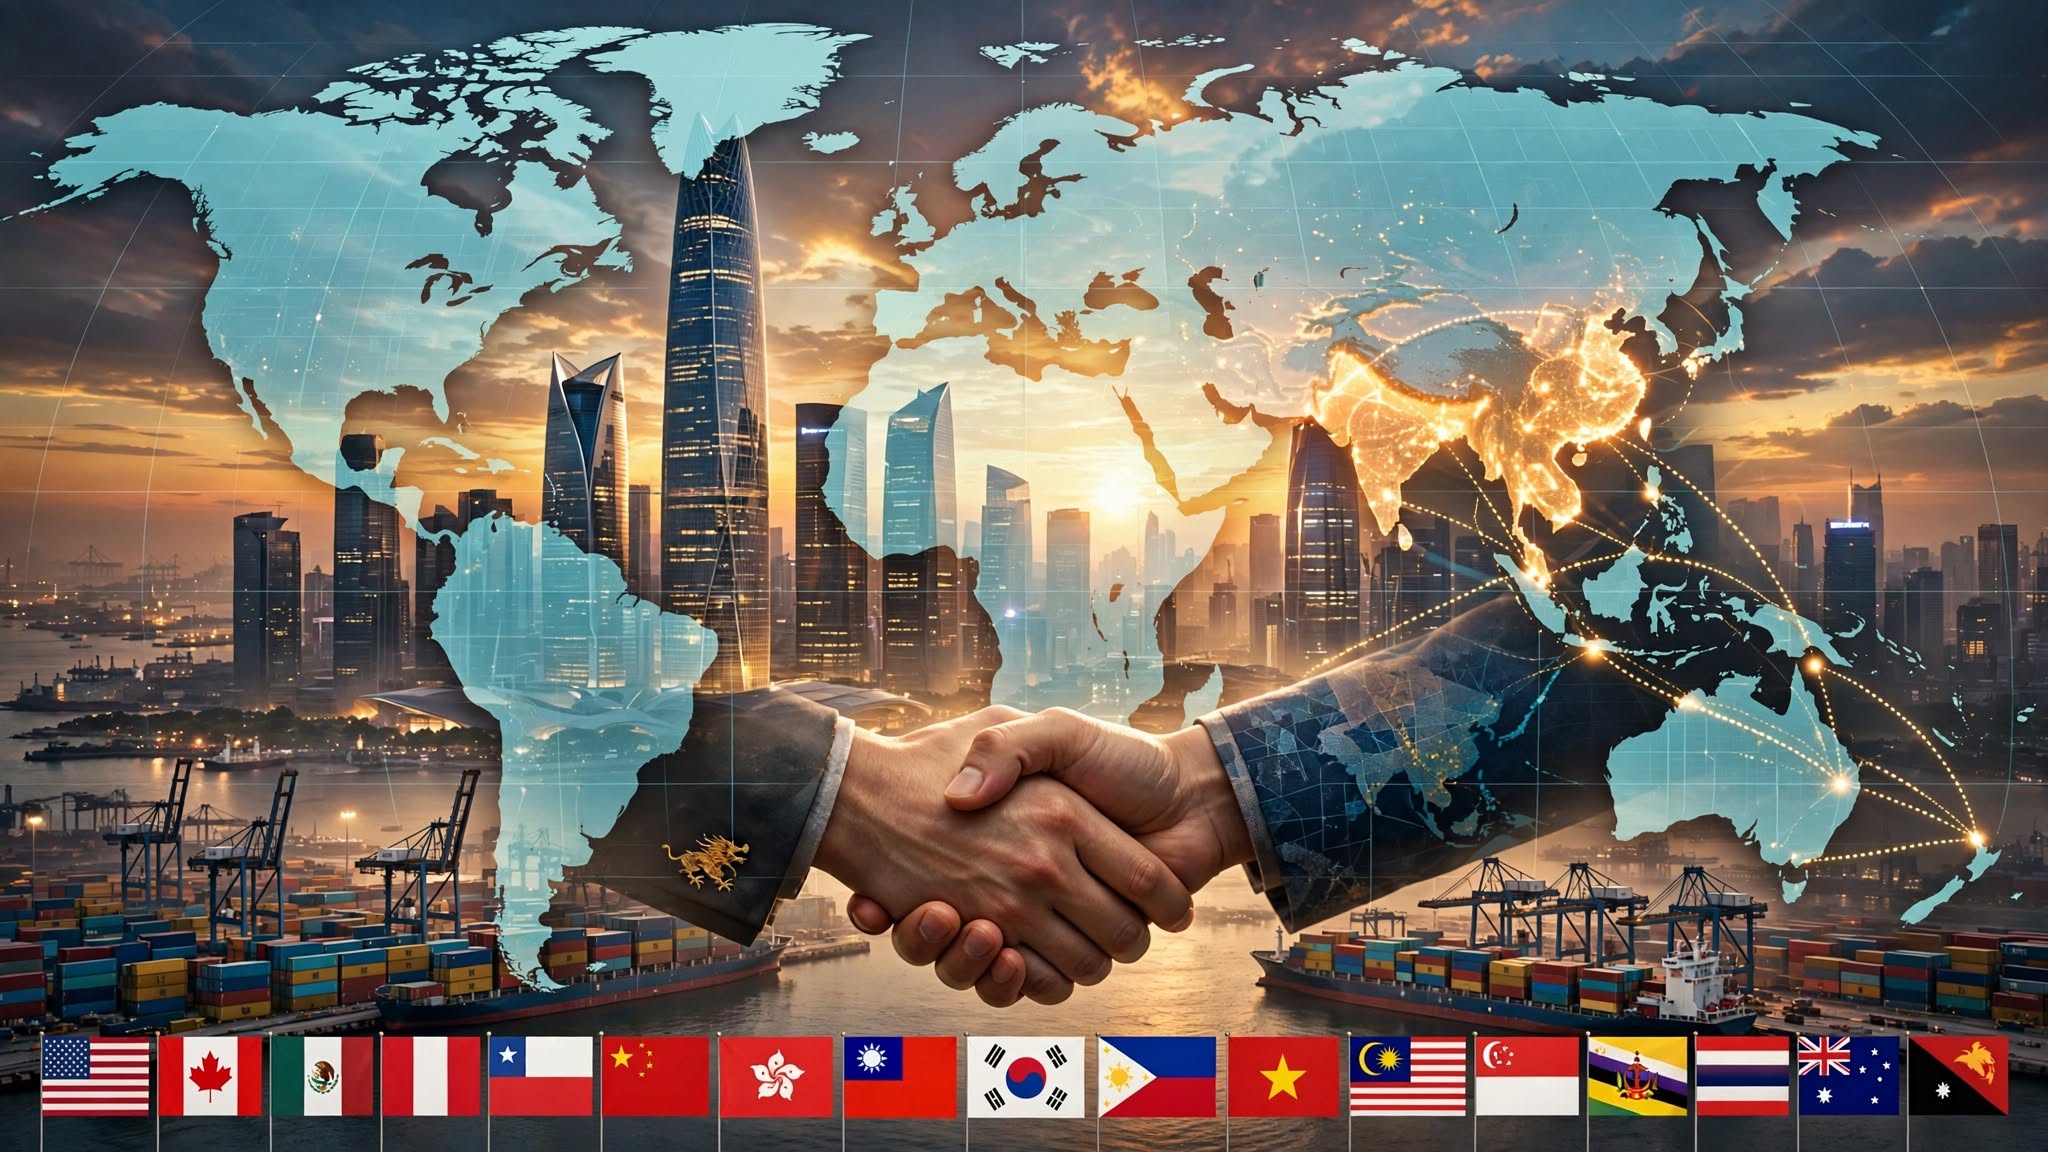
China is preparing to use its hosting of the Asia-Pacific Economic Cooperation (APEC) forum in 2026 to revive one of the world’s most ambitious trade ideas — the Free Trade Area of the Asia-Pacific (FTAAP). The move is widely seen as both a strategic taunt to the United States and a goodwill gesture to Asia.
As host of the 33rd APEC Economic Leaders’ Meeting in Shenzhen, Beijing is positioning itself as the champion of open, multilateral trade at a time when Washington is embracing protectionism.
What is FTAAP and Why Does It Matter Now?
The Free Trade Area of the Asia-Pacific (FTAAP) is a proposed mega-regional trade agreement that would cover all 21 APEC member economies.
APEC’s official history shows the concept was first proposed by the APEC Business Advisory Council (ABAC) in 2004 and formally endorsed by leaders in 2006 as a long-term prospect. It was given major momentum with the adoption of the Beijing Roadmap for APEC’s Contribution to the Realization of the FTAAP in 2014.
The scale is massive. APEC’s 21 members account for over 60% of global GDP and nearly half of world trade, with a combined population of 2.9 billion people. According to USTR data, APEC GDP reached an estimated $67.8 trillion in 2024.
Despite its potential, FTAAP has lain dormant due to geopolitical rivalries, the collapse of WTO Doha talks, and competing regional deals.
APEC 2026: Why Shenzhen Changes Everything
This will be China’s third time hosting APEC and the first in 12 years. Chinese President Xi Jinping announced that Shenzhen will host the 2026 leaders’ meeting from November 18-19, 2026, calling the city a “miracle in world development”.
China’s state media confirmed the APEC CEO Summit 2026 will be held in Shenzhen on Nov 17-18, with the theme “Building an Asia-Pacific Community to Prosper Together”. China Daily reports the agenda will focus on building the FTAAP, alongside digital economy, AI, and sustainable development.
China has chosen three priorities for its host year: Openness, Innovation, and Cooperation. Advancing FTAAP is central to the Openness pillar.
Chinese Vice Minister of Commerce Li Chenggang said China wants to use the 20th anniversary of FTAAP as an opportunity to promote coordinated development of regional trade rules. Indonesia’s official Antara news agency reported that Chinese officials are seeking an “agreement to implement” FTAAP at this year’s forum.
The Two Pathways: RCEP and CPTPP
APEC itself does not negotiate tariffs; it incubates ideas. The consensus view is that FTAAP will be built by merging existing mega-deals.
APEC’s own research identifies RCEP and CPTPP as the two key pathways to FTAAP.
| Feature | RCEP | CPTPP | Proposed FTAAP |
|---|---|---|---|
| Members | 15 (includes China, 12 APEC members) | 12 (11 APEC members, no US or China yet) | All 21 APEC economies including US, China, Russia |
| Standard | Moderate, flexible | Very high standard | High-quality, comprehensive |
| Status | In force since Jan 2022 | In force, China has applied to join | Vision, under study |
Chinese President Xi Jinping said at the 2024 APEC meeting that RCEP and CPTPP should “align with each other and progress together so as to inject impetus into the development of the FTAAP.”
This alignment is strategic. APEC’s Putrajaya Vision 2040, adopted in 2020, reaffirms FTAAP as a major instrument to further regional economic integration and is central to the Aotearoa Plan of Action.
Taunting the US, Tantalising Asia: The Geopolitics
Why China wants it: For Beijing, FTAAP counters pressure from the US and EU over its export practices and allows Chinese exporters — a backbone of the world’s second-largest economy — to ship at lower costs. More importantly, it casts China as the defender of free trade.
Why the US will resist: APEC makes decisions by consensus, not majority vote, giving Washington effective veto power. Analysts note Donald Trump’s opposition to multilateral deals makes an APEC-wide agreement unlikely.
Trump opposes multilateral trade deals and imposed tariffs of more than 100% on Chinese imports during his first term, and again in 2025. China has filed multiple complaints to the WTO, accusing the US of undermining the rules-based multilateral trading system with reckless tariffs and warning that US tariffs violate WTO rules and cause global turbulence.
Experts argue Washington fears China could use other FTAAP members as “stepping stones to export goods to the US.”
As Christopher Beddor of Gavekal Dragonomics noted in the SCMP piece, “Pushing on the [FTAAP] may or may not lead to substantive deliverables, but simply keeping it in the headlines can allow China to portray itself as a champion of open trade.”
Will FTAAP Actually Happen in 2026?
Short answer: A full treaty is unlikely, but a major political declaration is highly probable.
- Consensus hurdle: All 21 economies, including the US and Russia, must agree.
- US-China rivalry: Fundamental disagreement on trade governance.
- Low-hanging fruit strategy: Instead of a full FTA, China is likely to push for an updated “Beijing Roadmap 2.0”, a feasibility study, or new guidelines on next-generation issues like digital trade, green economy, and supply chain connectivity.
Even without a deal, Beijing wins goodwill. For Southeast Asian manufacturing powerhouses already bound to China via RCEP, any move to cut export costs is welcome.
Conclusion: More Than a Trade Deal
China’s FTAAP bid for APEC 2026 is less about signing a treaty in Shenzhen and more about narrative control. While the US uses tariffs as an economic and geopolitical tool, China is using APEC’s host chair to propose action, integration, and cost-cutting.
If successful, it would be the largest free trade area in history. If blocked, it still allows Beijing to portray Washington as the obstacle to regional prosperity — a powerful message for Asia.
SEO Keywords to target: FTAAP, Free Trade Area of the Asia-Pacific, APEC 2026 Shenzhen, APEC China 2026, RCEP CPTPP FTAAP, Putrajaya Vision 2040, China US trade war APEC
FAQ
Q: When and where is APEC 2026?
A: The 33rd APEC Economic Leaders’ Meeting will be held in Shenzhen, China from November 18-19, 2026, with the CEO Summit on Nov 17-18.
Q: What countries are in FTAAP?
A: All 21 APEC members: Australia, Brunei, Canada, Chile, China, Hong Kong, Indonesia, Japan, South Korea, Malaysia, Mexico, New Zealand, Papua New Guinea, Peru, Philippines, Russia, Singapore, Taiwan, Thailand, US, Vietnam.
Q: What is the difference between RCEP, CPTPP and FTAAP?
A: RCEP and CPTPP are existing regional agreements covering 15 and 12 countries respectively. FTAAP is the proposed overarching agreement that would merge them into one covering all 21 APEC economies.

The Pentagon rarely uses the word “unrecoverable” in an official acquisition report. It used it this August, in a Selected Acquisition Report describing the state of Boeing’s F-15EX Eagle II program — and the phrase should have every defense-sector supply chain manager, procurement officer, and B2B logistics executive paying close attention.
The core problem: a 102-day strike at Boeing’s St. Louis-area production facilities didn’t just cost the company three months of output. It broke a delivery schedule in a way the Pentagon itself now says can’t be fully undone.
The Aircraft: What the F-15EX Actually Delivers
Before the supply chain story, it’s worth understanding why the Air Force wants this jet badly enough to be publicly frustrated about delays.
The F-15EX Eagle II is the most advanced variant of the F-15 lineage ever built:
- Digital fly-by-wire flight controls and a large-area glass cockpit with touchscreen interface
- A new APG-82 AESA radar, Joint Helmet Mounted Cueing System, and EPAWSS self-defense electronic warfare suite
- Higher speed and longer range than legacy F-15 variants, with a 29,000-lb payload capacity across additional weapons stations versus older Eagles
- A per-unit flyaway cost of roughly $90–93 million, with a 30-year, 104-jet program lifecycle cost estimated at $30–35 billion — a figure that compares favorably to stealth alternatives on a pure cost basis
The Air Force has committed to replacing aging F-15C/D fleets — including 36 jets slated to permanently replace 48 legacy Eagles at Kadena Air Base, Okinawa — with the EX variant, making this as much an Indo-Pacific readiness story as a domestic manufacturing one.
The Strike: 102 Days That Broke a Production Curve
Roughly 3,000+ Boeing machinists in the St. Louis region — spanning facilities in St. Louis, St. Charles, and Mascoutah, Illinois — walked off the job on August 4, 2025. The strike didn’t end until November 13–17, 2025, a complete production halt of more than three months.
Before the walkout, Boeing’s plan was aggressive but achievable:
- Deliver a full dozen Lot 2 Eagle IIs by the end of calendar 2025
- Ramp to an assembly rate of two jets per month by early 2026
- Maintain the program’s prior track record of staying within cost, schedule, and performance baselines — with all Lot 1 aircraft already delivered on time
The strike erased that runway entirely. Then–Air Force chief of staff nominee Gen. Kenneth Wilsbach confirmed the delay in written Senate testimony well before the strike even ended, warning lawmakers that overseas deliveries — including to Kadena — would be pushed into 2026.
Why the Pentagon Called the Slip “Unrecoverable”
Here’s the detail that separates this piece from standard defense-news coverage: the August 2026 Selected Acquisition Report doesn’t just describe a delay — it describes a structural, non-recoverable schedule slip.
- Boeing’s original contract required all 12 Lot 3 jets delivered in early calendar 2026.
- Instead, only about six will arrive by year’s end.
- The report explicitly frames this shortfall as permanent — the missed units are not simply “coming later,” they represent lost production capacity the line cannot make up under current constraints.
The Real Bottleneck: Parts Shortages Compounding the Strike
This is the angle that pure aviation-hobbyist coverage tends to skip, but that matters enormously to defense-sector procurement and supply chain software buyers: the strike exposed — and worsened — a parts shortage that predates it.
- Elbit-built large-area displays and low-profile head-up displays, which give the Eagle II its signature glass cockpit, are running short.
- General Electric F110 engines, the powerplant behind the jet’s performance envelope, face their own allocation constraints.
- Collins-made ejection seat cartridges round out the list of critical, single-source components.
Stockpiled inventory built up before the strike was sufficient to cover Lot 1B production. Everything after that is exposed. The Pentagon has resorted to borrowing-and-payback arrangements with foreign military sales customers — essentially reallocating parts earmarked for allied buyers back to U.S. production lines, then repaying the debt later — just to keep the line moving. That’s not a sustainable long-term fix; it’s a stopgap that shifts risk onto allied delivery schedules instead of eliminating it.
What This Means for Defense Contractors and Suppliers
For B2B readers in the defense and aerospace supply chain space, the actionable takeaways are:
- Single-source component risk is now a headline Pentagon concern, not a theoretical one. Any supplier or integrator still running single-vendor sourcing on flight-critical components (displays, engines, ejection systems) should expect increased scrutiny — and increased opportunity for qualified second-source suppliers.
- Supply chain visibility software and multi-tier risk modeling tools are likely to see increased defense-sector procurement interest as primes try to avoid a repeat of the Elbit/GE bottleneck on other programs.
- Labor relations at unionized aerospace primes are now a directly quantifiable program risk, one the Pentagon is willing to describe in a public acquisition document. Expect this to influence how future defense contracts price in labor-disruption contingencies.
- The F-15EX buy itself may be doubling in size even as the current lots run behind — the same Selected Acquisition Report flagged new cost and schedule uncertainty tied to an expanded production run, including warnings that radar, mission computer, electronic warfare, and engine systems could become obsolete over a longer timeline, requiring a “significant redesign effort” whose full cost hasn’t yet been estimated.
What Competitors Are Missing
Most defense trade coverage of the F-15EX delays stopped reporting once the strike itself ended in November 2025. The more important story — the one buried in an August 2026 acquisition document most outlets haven’t dug into — is that the schedule damage from that strike is now classified by the Pentagon as permanent, and that a second, ongoing bottleneck (Elbit displays and GE F110 engines) means the program isn’t fully back to healthy even ten months after the picket lines came down.
Timeline at a Glance
- Aug. 4, 2025 — St. Louis strike begins
- Oct. 2025 — Wilsbach confirms delivery delays in Senate testimony
- Nov. 13–17, 2025 — Strike ends
- Nov. 26, 2025 — First post-strike F-15EX delivered (142nd Wing, Portland ANG)
- Feb. 2026 — Air Force confirms delayed Kadena Air Base deployment
- Apr.–Jun. 2026 — Boeing targets doubling production rate to two jets/month
- Aug. 2026 — Selected Acquisition Report flags “unrecoverable delays” and parts shortages
People also Ask :
Q: Why are F-15EX Eagle II deliveries delayed?
A 102-day strike at Boeing’s St. Louis-area facilities (August–November 2025) halted F-15EX production, and a 2026 Pentagon acquisition report calls the resulting schedule slip “unrecoverable” — only about six of the contracted 12 Lot 3 jets will arrive by the end of 2026 instead of all 12 in early 2026. Ongoing shortages of Elbit-built cockpit displays and GE F110 engines are compounding the delay.

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Is SPY Overvalued in September 2026? Fed Rate Hike Odds & Intrinsic Value
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
The New Executive Gold Standard: Top 10 Companies Lavishing Unprecedented Perks on CEOs and CFOs in 2025–2026
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Analysis4 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025