Human Capital
Sindh’s Payroll Crisis: How a Digital Payment System Collapse Left Thousands of Government Employees Without January Salaries

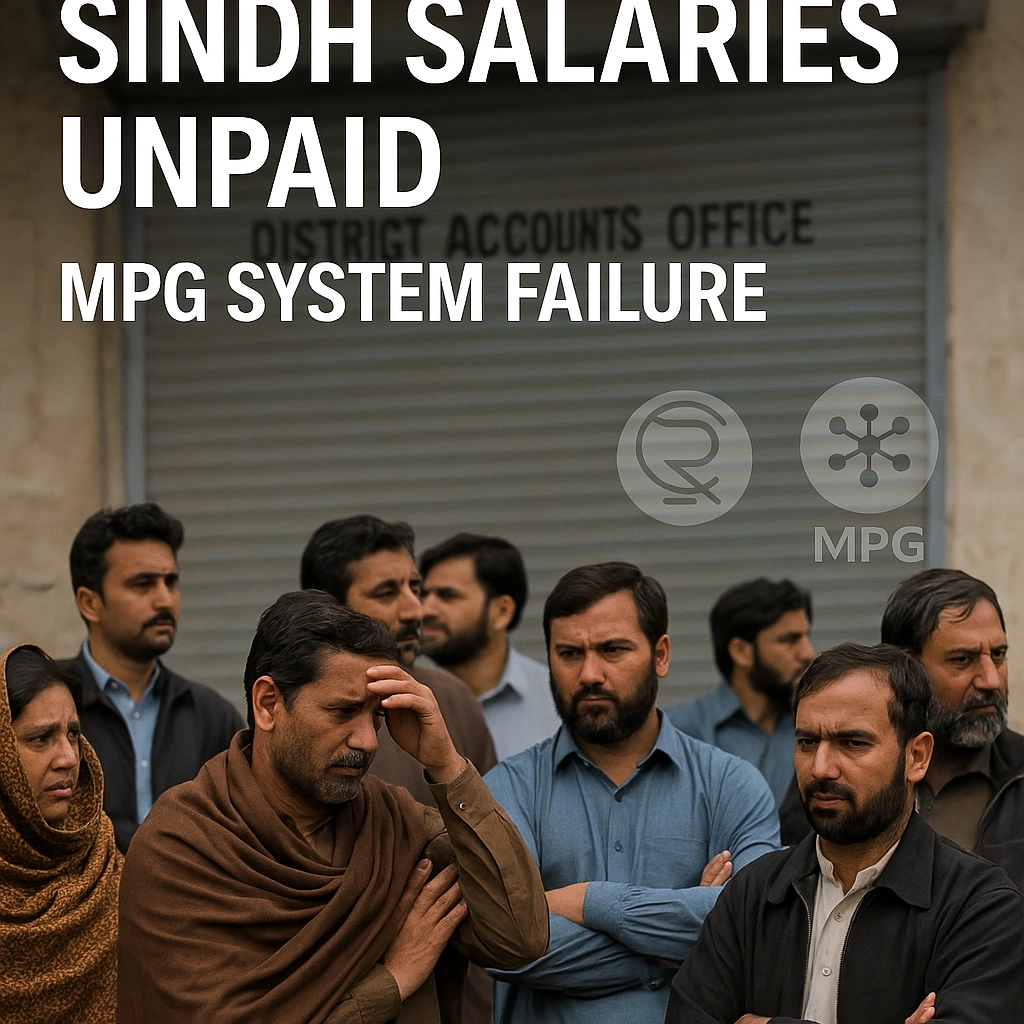
Sindh government employees remain unpaid as MPG payment system fails past January 25th deadline. Exclusive investigation into Pakistan’s digital payment infrastructure breakdown and its human cost.
“The 25th Has Come and Gone—But Salaries Haven’t“
For Muhammad Rasheed, a grade-17 officer in Sindh’s education department, January 28th marks the third day of uncertainty. The 25th—traditionally the day when government salaries illuminate bank accounts across Pakistan—passed without the familiar notification ping. His children’s school fees are overdue. His wife postponed a medical appointment. And like thousands of civil servants across Sindh province, he’s caught in the crossfire of what experts are calling Pakistan’s most significant digital payment system failure in recent memory.
The culprit? The Micro Payment Gateway (MPG), a digital disbursement platform that was supposed to modernize how Sindh pays its 400,000-plus government employees. Instead, it has created a humanitarian and administrative crisis that exposes the fragility of Pakistan’s rush toward digitalization without adequate safeguards.
According to sources within the Accountant General (AG) Sindh office who spoke on condition of anonymity, the system experienced “catastrophic failures” in processing the January 2026 payroll, leaving employees—from junior clerks to senior administrators—in financial limbo. This isn’t merely a technical glitch; it’s a case study in how premature digital transformation can collapse under its own weight.
Understanding the MPG Debacle: What Went Wrong?
The Promise of Digital Transformation
Pakistan’s State Bank of Pakistan (SBP) has been aggressively promoting digital payment infrastructure, including the Raast instant payment system, as part of its National Financial Inclusion Strategy. The MPG was envisioned as Sindh’s answer to efficient, transparent salary disbursement—eliminating intermediaries, reducing corruption, and ensuring timely payments.
The Washington Post recently highlighted Pakistan’s digital ambitions in its Asia economic coverage, noting that “emerging markets face unique challenges in digital payment adoption“—a prescient observation given Sindh’s current predicament.
The Reality: A System Unraveling
Multiple technical failures have compounded since late 2025:
District-Level Breakdowns
- Badin District: Complete payroll processing failure affecting 8,000+ employees
- Dadu District: Partial disbursements with unexplained deductions
- Ghotki District: System rejecting employee bank account validations
Sources indicate the MPG’s integration with the Controller General of Accounts Pakistan (CGA) database encountered synchronization errors, particularly affecting employees receiving the Salaries through MPG .
“The system wasn’t stress-tested for scale,” explains Dr. Ayesha Malik, a digital governance expert at Lahore University of Management Sciences. “When you’re processing 400,000 salaries simultaneously, any latency in API calls or database queries creates cascading failures.”
The Federal-Provincial Divide
The crisis highlights a disturbing disparity. Federal government employees in Islamabad received January salaries on schedule through the tried-and-tested systems managed by the Controller General of Accounts. Punjab province, which piloted a hybrid digital-manual approach, reported 99% on-time disbursement according to data tracked by governance monitoring organizations.
Sindh stands alone in its comprehensive failure—a province that accounts for approximately 22% of Pakistan’s GDP but now cannot pay its own workforce.
The Human Toll: Beyond Statistics and Systems
Stories From the Frontlines
Khadija Bibi, Grade 9 Clerk, Health Department, Hyderabad: “I couldn’t pay my electricity bill. When I went to the school to explain why I couldn’t pay my daughter’s fees, I felt humiliated. They know I’m a government employee. They think I’m making excuses.”
Rashid Ahmed, Grade 16 Officer, Irrigation Department, Sukkur: “We took out high-interest private loans just to buy groceries. The irony? I work in a department that manages water resources for millions, but I can’t manage my own household expenses.”
These aren’t isolated incidents. According to preliminary surveys by civil servant unions, approximately 68% of affected employees have resorted to informal borrowing, often at predatory interest rates exceeding 15% monthly.
The Economist’s recent analysis of emerging market labor dynamics noted that “government employment in South Asia functions as both economic stimulus and social safety net”—making salary delays not just administrative failures but potential triggers for broader economic disruption.
Pension Paralysis
The crisis extends beyond active employees. Thousands of retirees dependent on monthly pensions face similar uncertainty. For many elderly recipients without alternative income sources, this represents an existential threat.
“My father served 35 years in the judiciary,” shares Maryam Khan, daughter of a retired civil judge. “His pension hasn’t come through. He has diabetes medication to buy. This is how we treat our retired public servants?”
Administrative Autopsy: Who’s Accountable?
The Blame Cascade
AG Sindh Office: Claims the State Bank of Pakistan infrastructure experienced “unexpected downtime” during critical processing windows.
State Bank of Pakistan: Points to incomplete data submission from provincial authorities and “non-standard file formats” that violated integration protocols.
Provincial Finance Department: Suggests the Controller General of Accounts delayed authorization for January disbursements due to “budgetary reconciliation issues.”
This circular blame game reveals a fundamental problem: no single entity owns the end-to-end payment process. The MPG system exists in a bureaucratic no-man’s-land where technical failures become administrative hot potatoes.
The Reversion Rumors
Multiple sources confirm that senior Sindh government officials have discussed reverting to manual salary disbursement processes—essentially abandoning the MPG experiment. However, this creates its own complications:
- Data Migration Challenges: Employee records have been partially migrated to the digital system
- Timeline Concerns: Manual processing for 400,000+ employees could take 3-4 business days
- Political Optics: Admitting digital transformation failure before upcoming elections
Financial Times’ coverage of government technology implementations in developing economies warns that “premature abandonment of digital systems after initial failures can create worse long-term outcomes than temporary persistence with fixes”—a dilemma Sindh now faces.
Key Takeaways
- 400,000+ Sindh government employees haven’t received January 2026 salaries due to MPG system failure or Deliberate apathy of Accounts Offices .
- District-level breakdowns in Badin, Dadu,Kashmore and Ghotki compound the crisis
- Federal and Punjab governments disbursed salaries on time, highlighting Sindh’s unique failure
- 68% of affected employees have resorted to high-interest informal borrowing
- Reversion to manual systems being considered but faces logistical and political obstacles
- Broader implications for Pakistan’s digital transformation credibility and economic stability
Comparative Analysis: Lessons From Other Provinces
Punjab’s Hybrid Success
Punjab province implemented a gradual digital transition:
- Pilot program with 10,000 employees (6 months)
- Parallel manual and digital processing (12 months)
- Full digital transition only after 98% success rate achieved
Result? Zero salary delays in the past 18 months.
Federal Government’s Conservative Approach
The federal establishment maintains legacy systems with incremental digital enhancements—prioritizing reliability over innovation. While less efficient, this approach has delivered 100% on-time salary disbursement for 47 consecutive months.
Forbes recently profiled successful government digital transformations in Asia-Pacific, emphasizing that “speed of implementation matters far less than thoroughness of testing and redundancy planning”—wisdom Sindh appears to have ignored.
Broader Implications: Pakistan’s Digital Governance Crossroads
The Credibility Crisis
This failure undermines Pakistan’s broader digital transformation initiatives:
- Raast Payment System Adoption: Banks report declining merchant confidence in government-backed digital platforms
- Tax Digitalization: Concerns about FBR’s planned e-filing mandate
- E-Governance Projects: Provincial governments reconsidering aggressive digital timelines
“One high-profile failure creates systemic skepticism,” notes Farhan Mahmood, a Karachi-based technology governance consultant. “It takes years to rebuild trust in digital government systems.”
The Economic Ripple Effect
When 400,000+ government employees lack purchasing power:
- Local Commerce Disruption: Retailers in government employment hubs (Karachi, Hyderabad, Sukkur) report 30-40% sales declines
- Informal Lending Surge: Private money lenders report unprecedented demand
- Household Debt Accumulation: Long-term financial vulnerability for civil servant families
The Washington Post’s economics desk has documented how public sector salary disruptions in developing economies create “multiplier effects that reduce GDP by 0.3-0.5% quarterly”—a potential scenario for Sindh if delays persist.
The Path Forward: Five Critical Interventions
1. Emergency Manual Disbursement
Activate legacy systems immediately for critical-need employees (grades 1-11, pensioners, medical emergencies) while debugging MPG infrastructure.
2. Independent Technical Audit
Engage international payment system auditors (similar to those used by State Bank of Pakistan for Raast system validation) to identify root causes and recommend fixes.
3. Transparent Communication Protocol
Establish daily public updates on resolution progress—reducing anxiety and rumor circulation among affected employees.
4. Compensatory Measures
Consider:
- Interest-free advance salary loans through government banks
- Automatic reversal of late payment penalties for employee bills
- Hardship grants for lowest-grade employees
5. Accountability Framework
Commission a formal inquiry with public hearings—not for political theater, but genuine systemic learning. The Economist’s governance research emphasizes that “administrative failures require institutional accountability, not individual scapegoating” to prevent recurrence.
Conclusion: A Cautionary Tale for Digital Governance
The Sindh MPG payment system failure represents more than delayed salaries—it’s a referendum on how governments approach digital transformation in resource-constrained environments. The rush to appear technologically progressive, without adequate testing, redundancy planning, and stakeholder preparation, has created precisely the crisis digitalization was meant to prevent.
For Muhammad Rasheed and hundreds of thousands like him, the promise of efficiency has yielded only uncertainty. For Pakistan’s digital governance ambitions, this is a watershed moment: either a catalyst for genuine reform, or the beginning of a retreat to comfortable but inefficient status quo.
The next 72 hours will determine which path employees go for rights . Still no updates for salaries
As Financial Times noted in its recent analysis of emerging market governance challenges: “Technology is only as good as the systems that implement it, and the people who depend on it.” Sindh’s 400,000 government employees are now the unwilling test subjects of that axiom.
The question remains: Will anyone be held accountable before the February salary cycle begins?

Friday morning at 8:30 AM Eastern, the consensus macroeconomic playbook was torn to shreds. Traders who had spent the past three months pricing in a gentle glide path to monetary easing watched their screens flash red as the Bureau of Labor Statistics published a headline number that defied gravity. Investors boost bets for Fed rate rise after bumper US jobs report, scrambling to offload short-dated Treasuries in a matter of seconds. The soft landing narrative, so carefully cultivated in financial media and trading desks alike, suddenly looks precariously close to a no-landing scenario.
For the better part of a year, the prevailing assumption on Wall Street was that the Federal Reserve had broken the back of inflation without breaking the labor market. Central bankers were ostensibly preparing to pivot. Yet, the sheer velocity of job creation over the past month has inverted the yield curve’s fundamental logic.
When an economy operating at full employment suddenly adds upward of 300,000 positions in a single month, the mathematics of disinflation break down. Average hourly earnings are rising faster than productivity can absorb. According to the Bureau of Labor Statistics, wage growth ticked up to 4.1% year-over-year, well above the threshold compatible with the Fed’s 2% inflation target. This isn’t a statistical anomaly. It is a structural warning sign. The bond market, notoriously unsentimental, instantly repriced the terminal rate, pricing out cuts and firmly writing a hike back into the script.
The Core Development: Sizing the Surprise
The mechanics of Friday’s repricing were brutal and instantaneous. A US jobs report Fed rate hike scenario wasn’t even on the bingo card for most institutional desks last week. Now, it is the base case.
The establishment survey revealed a staggering gain of 303,000 nonfarm payrolls, making a mockery of the 200,000 median forecast. Crucially, the gains were not isolated to cyclical sectors. Healthcare, government, and leisure and hospitality drove the headline figure, but construction and manufacturing also posted solid prints. This broad-based hiring completely ruins the argument that the economy is cooling beneath the surface. Companies are not just replacing lost talent; they are actively expanding payrolls at a pace typical of an early-cycle recovery, not a late-cycle tightening phase.
Within minutes of the release, the CME FedWatch Tool — the market’s definitive probability gauge for monetary policy — violently readjusted. The odds of the Federal Open Market Committee delivering a 25-basis-point hike at their next gathering spiked from a negligible 12% to an alarming 48%. Two-year Treasury yields, highly sensitive to near-term policy expectations, surged past 4.75%, causing severe indigestion in equity markets. By 9:00 AM, the S&P 500 futures had surrendered all their weekly gains.
The Fed is trapped by its own data dependency. When Jerome Powell took to the podium last month, he emphasized patience. That patience is now a luxury the central bank cannot afford. If employers are bidding up wages to secure scarce labor, those costs will inevitably bleed into service sector prices. Reuters market analysis confirmed that swap markets are no longer anticipating a dovish reprieve; they are bracing for a prolonged period of restrictive monetary conditions. The data forces a reckoning.
The Analytical Layer: The Phillips Curve Strikes Back
Why does a strong jobs report affect interest rates? When employers aggressively raise pay to attract scarce workers, those higher operational costs are passed directly to consumers via higher prices. The Federal Reserve uses interest rates to cool demand; accelerating job creation forces the central bank to hike rates to prevent the economy from overheating.
Still, understanding why the labor market refuses to cool requires looking past the headline numbers. Corporate America is engaged in systemic labor hoarding. Having been burned by the catastrophic talent shortages of the post-pandemic reopening, executives are refusing to shed staff even as corporate margins compress. They remember the pain of 2022, when recruiting a single mid-level software engineer took six months and a 30% premium. Today, they would rather eat the cost of carrying excess headcount than risk being caught short-handed when demand re-accelerates.
There is a distinct demographic component at play, too. The prime-age labor force participation rate has hit a two-decade high, yet the total pool of available workers is structurally constrained by an aging population. Around 10,000 baby boomers hit retirement age every single day. Companies are hiring because they fear the well will run dry if they wait.
This structural tightness makes the Fed’s traditional economic models look increasingly obsolete. The Phillips curve, which plots the inverse relationship between unemployment and inflation, is steepening. Recent findings published by the International Monetary Fund suggest that in advanced economies with entrenched labor shortages, central banks must maintain higher real rates for demonstrably longer periods to achieve the same deflationary effect. The bumper payrolls print isn’t just a sign of economic health. It is a symptom of an inelastic labor supply that threatens to anchor inflation permanently above target.
Implications & Second-Order Effects: The Dollar Wrecking Ball
The downstream consequences of a revived Federal Reserve hiking cycle will be global and severe. The immediate casualty is the foreign exchange market. A hawkish Fed automatically supercharges the US dollar, acting as a wrecking ball for foreign currencies.
Emerging markets will bear the brunt of this pain. Countries that issue dollar-denominated debt are suddenly staring at a dual crisis: a stronger greenback inflates the principal of their obligations, while higher US Treasury yields drain global liquidity away from their domestic markets. Data from the World Bank highlights that every 100-basis-point increase in US interest rates correlates with a significant contraction in capital flows to developing economies. For nations already grappling with fiscal deficits, this is a recipe for sovereign default.
Domestically, the commercial real estate sector remains the most vulnerable domino. Over $1.5 trillion in commercial mortgages are scheduled to mature over the next three years. These loans were underwritten in an era of near-zero interest rates. If the Fed is forced to hike again, or even maintain current levels well into next year, the refinancing arithmetic for office towers in Manhattan and San Francisco becomes terminal. Default rates will climb, placing renewed stress on regional banks that hold the majority of this paper.
Corporate credit markets are also on notice. High-yield issuers, previously enjoying remarkably tight spreads due to the soft-landing consensus, are suddenly exposed. The cost of capital is rising precisely when consumer purchasing power is starting to fray at the edges. A company that could comfortably service its debt at 5% will face existential questions if forced to roll over that same debt at 9%.
Competing Perspectives: The Illusion of Strength
The picture is more complicated than the hawkish narrative suggests. While the headline payroll figure commands attention, beneath the surface, the data presents glaring contradictions that should give policymakers pause before pulling the trigger on another rate rise.
A significant discrepancy exists between the establishment survey, which polls businesses, and the household survey, which polls individual citizens. While the establishment data shows explosive growth, the household survey paints a stagnating picture, occasionally pointing to outright job losses.
What follows, however, is the composition of these new jobs. A deeper dive into the BLS annex reveals that a massive proportion of the job gains over the past six months are part-time roles. Full-time employment has actually contracted in several key metrics. Multiple jobholders—individuals forced to take on second or third gigs to cope with the elevated cost of living—are heavily skewing the headline numbers. A bartender taking on weekend shifts as an Uber driver registers as two separate jobs in the establishment survey. That isn’t economic strength; that is financial distress masking itself as labor demand.
Furthermore, the birth-death model used by statisticians to estimate job creation by new businesses may be vastly overestimating reality in a high-interest-rate environment. Analysts at the Financial Times have warned that these statistical mirages often precede severe downward revisions. If the Fed hikes rates based on an illusion of part-time labor strength, they risk driving the economy into a deep, unnecessary recession. The central bank is essentially driving using the rearview mirror, and the reflection may be heavily distorted.
Closing
The Federal Reserve is staring down a brutal mandate collision. To tolerate the current pace of job creation is to tacitly accept that inflation will remain structurally elevated, abandoning the sacred 2% target. Yet, to hike rates into a heavily leveraged economy on the back of data that might be fundamentally skewed by part-time employment is to risk financial instability.
Friday’s jobs report didn’t provide clarity; it provided a mandate for market volatility. The bond vigilantes have awakened, and they are demanding higher yields as compensation for the uncertainty. The era of easy monetary answers is definitively over.

SkillsFuture funding reforms signal a strategic pivot toward industry-led upskilling—but at what cost to smaller providers and self-funded learners?
On a humid afternoon in December, Melissa Tan sat in her Jurong West training center watching enrollment numbers tick downward on her computer screen. After fourteen years running a mid-sized vocational training provider, she had weathered economic downturns, policy shifts, and the digitization of Singapore’s workforce. But the new SkillsFuture funding guidelines announced by SkillsFuture Singapore (SSG) in late January felt different. “We’ve built our reputation on serving individuals who want to pivot careers on their own initiative,” she explained over coffee. “Now we need forty percent of our students to be employer-sponsored. That’s a complete business model transformation.”
Tan’s predicament illustrates the complex trade-offs embedded in Singapore’s latest recalibration of its decade-old SkillsFuture initiative. Effective December 31, 2025, SSG has imposed substantially tighter funding criteria on approximately 9,500 training courses across 500 providers—requirements that privilege employer-driven training over individual initiative, data-validated skills over experimental offerings, and quantifiable outcomes over pedagogical innovation. The reforms arrive at a moment when Singapore’s small, open economy faces mounting pressure from technological disruption, an aging workforce, and intensifying regional competition for talent and capital.
The policy shift represents more than administrative housekeeping. It embodies a fundamental question confronting advanced economies worldwide: How do governments balance the democratization of lifelong learning with the imperative to channel scarce public resources toward demonstrable economic returns?
The Mechanics of Tightening
The new guidelines affect what SSG terms “Tier 2” courses—those developing currently demanded skills for workers’ existing roles or professions. (They explicitly exclude SkillsFuture Series courses focused on emerging skills, or career transition programs like Institute of Higher Learning qualifications.) The changes impose three primary gatekeeping mechanisms:
Course approval: Prospective courses must now demonstrate alignment with either (1) skills appearing on SSG’s newly released Course Approval Skills List, derived from data science analysis of job market trends, or (2) documented evidence of industry demand through endorsement from designated government agencies or professional bodies. This represents a marked departure from the previous approach, which permitted a broader range of training offerings to access public subsidies.
Funding renewal threshold: From December 31, 2025 onward, courses seeking to renew their two-year funding cycle must demonstrate that at least 40 percent of enrollments came from employer-sponsored participants. This metric directly measures whether training aligns with enterprise workforce development priorities rather than individual hobbyist pursuits.
Quality survey compliance: Beginning June 1, 2026, courses must achieve a minimum 75 percent response rate on post-training quality surveys, with ratings above the lower quartile. This mechanism aims to eliminate providers who deliver mediocre experiences while gaming enrollment numbers.
A transitional framework softens the immediate impact. Between December 31, 2025 and June 30, 2027, selected course types—including standalone offerings from institutes of higher learning, courses leading to Workforce Skills Qualification Statements of Attainment, and certain other categories—receive a one-year grace period if they fail the 40 percent employer-sponsorship threshold. But the reprieve is temporary; from July 1, 2027, all Tier 2 courses must meet the full criteria.
The Economic Logic: Aligning Supply with Demand
The rationale behind these reforms emerges clearly when viewed against Singapore’s macroeconomic imperatives and recent labor market data. According to SSG’s 2025 Skills Trends analysis, demand for AI-related competencies has surged across industries, with skills like “Generative AI Principles and Applications” experiencing the fastest growth in job postings data. Simultaneously, green economy skills—sustainability management, carbon footprint assessment—and care economy capabilities have gained prominence as Singapore pursues its Green Plan 2030 and grapples with demographic aging.
Yet training providers, responding to consumer demand rather than labor market signals, have often proliferated courses in saturated or declining sectors. The mismatch represents a classic market failure: individual learners, lacking perfect information about employment prospects, gravitate toward familiar or fashionable topics rather than areas of genuine skills shortage. Training providers, incentivized to maximize enrollment volumes, oblige. Public subsidies then inadvertently subsidize this misalignment.
The 40 percent employer-sponsorship requirement cleverly leverages employers’ superior information about workforce needs. Companies investing real money in their employees’ training create a demand-side filter that SSG believes will naturally favor courses addressing actual productivity gaps. “Employers vote with their wallets,” one SSG official noted at the January 27 Training and Adult Education Conference announcing the changes. “If a course can’t attract employer sponsorship, we need to ask whether it’s truly addressing labor market needs.”
From a public finance perspective, the logic is straightforward. Singapore, despite its fiscal strength, operates under self-imposed constraints: a balanced budget requirement, limited borrowing for current spending, and a cultural aversion to expansive welfare states. SkillsFuture expenditures have grown substantially since the program’s 2015 launch—Singaporeans aged 25 and above have collectively claimed over S$1 billion in SkillsFuture Credits, with enhanced subsidies for mid-career workers (aged 40-plus) adding further fiscal pressure. Ensuring these outlays generate measurable employment and productivity outcomes becomes imperative as the government contemplates longer-term structural challenges: an aging society requiring expanded healthcare spending, investments in digital infrastructure and green transition, and resilience measures against external economic shocks.
Global Context: Singapore’s Experiment in Comparative Relief
To appreciate the boldness of Singapore’s approach, consider its divergence from other advanced economies’ lifelong learning models. Denmark’s flexicurity system combines generous unemployment benefits with extensive active labor market policies, including subsidized adult education. But Denmark can afford this largesse through high taxation (total government revenue exceeds 46 percent of GDP, versus Singapore’s 20 percent) and a homogeneous, highly unionized workforce. South Korea’s K-Digital Training initiative, launched in 2020, channels subsidies toward digital skills bootcamps—but targets primarily youth and unemployed workers, not the broader workforce Singapore aims to reach.
France’s Compte Personnel de Formation (CPF) offers perhaps the closest parallel: a portable training account funded through payroll levies, giving workers autonomy over skill development. Yet France’s system has faced criticism for fraud, low-quality providers gaming the system, and inadequate alignment with labor market needs—precisely the pathologies Singapore’s reforms seek to preempt. A 2021 report in The Economist examining retraining programs across OECD countries found that success correlated strongly with employer involvement and labor market relevance, rather than mere accessibility.
Singapore’s model occupies a distinctive middle ground: universal entitlements (every citizen aged 25-plus receives credits), but channeled through market mechanisms and employer validation. The SkillsFuture reforms effectively tighten the alignment mechanism without abandoning the universalist principle—a pragmatic compromise characteristic of Singapore’s technocratic governance style.
The Squeeze on Training Providers: Winners and Losers
The employer-sponsorship threshold creates clear winners and losers among training providers. Large, established players with existing corporate relationships—polytechnics, ITE, private training centers serving multinational corporations—possess natural advantages. They can leverage long-standing contracts, industry advisory boards, and placement track records to attract employer-sponsored enrollments.
Smaller providers face steeper challenges. Many built their businesses serving self-funded mid-career professionals seeking new skills or side ventures—precisely the demographic segment the reforms indirectly penalize. “We’ve invested heavily in emerging areas like blockchain development and sustainability consulting,” explained one boutique training center director who requested anonymity. “These are forward-looking skills, but companies aren’t yet sponsoring at scale because the roles barely exist in their organizations. Under the new rules, we’re essentially being told to wait until the demand becomes mainstream—by which point the opportunity has passed.”
The enrolment cap mechanism, while intended to prevent gaming, compounds the squeeze. Courses reaching their enrollment limit before the funding renewal check (six months prior to the end of the two-year validity period) must pass quality checks before accepting additional students. High-demand courses thus face bureaucratic friction at the worst possible moment—when they’ve demonstrated market appeal. Lower-demand courses, by contrast, may never hit enrollment thresholds requiring scrutiny, creating a perverse incentive structure.
Training providers serving niche industries face particular vulnerability. Specialized sectors like maritime law, conservation biology, or heritage preservation generate modest enrollment volumes and limited employer-sponsorship rates (small firms in these fields often lack formal training budgets). Yet these represent precisely the differentiated capabilities that sustain Singapore’s position as a diversified, knowledge-intensive economy beyond the big four sectors (finance, logistics, technology, manufacturing).
Access and Equity: The Self-Funded Learner’s Dilemma
The employer-sponsorship emphasis raises important equity questions. Not all workers enjoy employer-sponsored training opportunities equally. Research by Singapore’s Ministry of Manpower shows that company-sponsored training tends to concentrate among degree-holders, professionals, and employees of large firms. Rank-and-file workers in SMEs, gig economy participants, and those in precarious employment—precisely the groups most vulnerable to technological displacement—face significant barriers.
Consider Raj Kumar, a 47-year-old logistics coordinator whose employer, a small freight forwarding company, lacks a formal training budget. Kumar has used SkillsFuture credits to complete courses in data analytics and digital supply chain management, hoping to transition into a more technology-oriented role. Under the new guidelines, his preferred courses may lose funding eligibility if they fail to attract sufficient employer sponsorship—forcing him to either pay full cost or choose less relevant but better-subsidized alternatives.
Women reentering the workforce after caregiving breaks present another equity concern. These mid-career returners often invest in self-funded retraining to compensate for skills atrophy or career pivots. Employer-sponsorship requirements create a catch-22: they need training to become employable, but courses require employer interest to remain subsidized.
SSG officials argue that alternative pathways remain available—SkillsFuture Career Transition Programs explicitly serve career switchers, and mid-career enhanced subsidies (covering up to 90 percent of course fees for Singaporeans aged 40-plus) continue supporting self-funded learning. But the distinction between “career transition” and “skills upgrading” proves blurry in practice. Many mid-career workers pursue incremental skill acquisition that doesn’t constitute wholesale career change yet enables internal mobility or role evolution. The new framework may inadvertently penalize this gray zone of professional development.
Data-Driven Skill Identification: Promise and Pitfalls
The Course Approval Skills List represents one of SSG’s more innovative elements. Using natural language processing and machine learning algorithms, SSG analyzes job posting data, wage trends, and hiring patterns to identify skills experiencing demand growth. The 2025 Skills Trends report reveals that 71 skills—spanning agile software development, sustainability management, and client communication—demonstrated consistently high demand and transferability across 2022-2024, with trends expected to continue into 2025.
This data-driven approach offers significant advantages over traditional expert panels or industry surveys. It’s faster, more comprehensive, and less subject to lobbying by incumbent industry players. The methodology also permits granular analysis—SSG now tracks not just skill categories but specific applications and tools (Python libraries, ERP systems, design software) required in job roles.
However, data-driven skill identification harbors limitations. Job postings reflect current employer preferences, not future needs. Emerging disciplines—quantum computing applications, circular economy frameworks, AI ethics—may barely register in job posting data until they’ve already achieved critical mass. By then, first-mover advantages have vanished. If training providers can only offer courses on SSG’s approved list, Singapore risks systematically underinvesting in forward-looking capabilities.
The methodology also privileges skills easily described in job postings. Tacit knowledge, soft skills, and creative competencies prove harder to quantify through algorithmic analysis. Yet these capabilities—judgment, cross-cultural communication, ethical reasoning—often determine long-term career success and organizational adaptability. A training ecosystem optimized for algorithmically identifiable skills may inadvertently neglect the human qualities most resistant to automation.
The Broader Stakes: Singapore’s Competitiveness Calculus
The SkillsFuture reforms must be understood within Singapore’s broader economic development strategy. The city-state has staked its future on becoming a hub for advanced manufacturing, digital services, sustainability innovation, and high-value professional services—sectors requiring a workforce that continuously upgrades capabilities. With neighboring countries investing heavily in technical education (Vietnam’s IT workforce, Thailand’s Eastern Economic Corridor initiative) and established hubs like Hong Kong and Seoul competing for similar industries, Singapore cannot afford complacency.
Yet the tightening carries risks. If Singapore’s training ecosystem becomes too employer-driven and algorithmically determined, it may sacrifice the experimental, entrepreneurial energy that has historically fueled its adaptive capacity. Many of Singapore’s successful industry pivots—from petrochemicals to biotech, from port logistics to digital banking—emerged from individuals and organizations pursuing capabilities ahead of obvious market demand.
The reforms also reflect broader tensions in Singapore’s governance model. The technocratic state excels at efficiency, optimization, and resource allocation toward measurable objectives. These strengths propelled Singapore from third-world poverty to first-world prosperity in two generations. But efficiency-maximizing systems can become brittle when confronted with uncertainty and ambiguity. Training that produces clear, quantifiable outcomes in stable domains may underperform when facing discontinuous change or nonlinear technological shifts.
Forward-Looking Implications: What Comes Next
The January 2026 announcement likely represents the opening salvo in a longer recalibration of Singapore’s lifelong learning architecture. Several trends warrant attention:
Increased emphasis on outcomes-based funding: Expect SSG to develop more sophisticated metrics beyond employer sponsorship—wage progression, job placement rates, productivity enhancements. The agency has already signaled interest in tracking post-training employment outcomes. Future iterations may adjust subsidy levels based on demonstrated impact.
Evolution of the Skills List methodology: As SSG refines its algorithmic approaches, the Course Approval Skills List will likely become more dynamic—updated quarterly rather than annually, incorporating leading indicators beyond job postings, and potentially using predictive modeling to anticipate emerging needs.
Differentiated treatment by sector: SSG may recognize that employer-sponsorship patterns differ across industries. Creative sectors, startups, and SME-dominated fields may receive adjusted thresholds or alternative validation mechanisms.
Greater integration with immigration and talent policy: The skills identified through SkillsFuture’s data infrastructure will increasingly inform Singapore’s employment pass criteria, tech.pass requirements, and sectoral talent initiatives. Training subsidies and immigration policy will converge into a unified human capital strategy.
Experimentation with training innovation zones: To preserve space for experimental offerings, Singapore may designate sandbox environments where providers can test new course concepts with lighter regulatory oversight before scaling.
The Danish Comparison: Lessons from Flexicurity
It’s instructive to contrast Singapore’s approach with Denmark’s vaunted flexicurity model, often cited as a gold standard for lifelong learning. Denmark spends approximately 2.5 percent of GDP on active labor market policies, including extensive adult education subsidies. Workers displaced by technological change or trade shocks can access generous retraining programs with income support.
But Denmark’s system operates in a fundamentally different institutional context. High trust between labor unions, employers, and government enables coordinated approaches to workforce adjustment. Collective bargaining determines training priorities. Social insurance funds (financed through high payroll taxes) cushion income shocks during reskilling. Cultural norms around equality and solidarity legitimize substantial transfers to support individual skill development.
Singapore lacks these institutional preconditions. Its tripartite labor relations model (government-union-employer cooperation) provides some coordination, but stops short of Nordic-style corporatism. The country’s fiscal conservatism precludes Danish-level spending. And Singapore’s multicultural, immigrant-heavy society (40 percent of the population are foreign workers or residents) complicates solidarity-based social insurance.
The SkillsFuture reforms implicitly recognize these constraints. Rather than expand public spending, they aim to spend existing resources more strategically. Rather than rely on trust-based coordination, they deploy data analytics and market mechanisms. This represents neither a superior nor inferior model, but an adapted solution to Singapore’s particular constraints.
The Economist’s Verdict: Calculated Risk or Overreach?
From a pure economic efficiency standpoint, the reforms possess clear merits. Channeling training subsidies toward employer-validated, data-confirmed skills should improve returns on public investment. The employer-sponsorship threshold creates skin-in-the-game dynamics that filter out marginal or dubious training offerings. And the quality survey requirements introduce accountability mechanisms previously absent.
Yet efficiency gains come with potential costs. By privileging current labor market demand over forward-looking capability building, Singapore may diminish its adaptive capacity. The employer-sponsorship threshold, while logical, risks excluding individuals in precarious employment or career transition phases. And the centralization of skill identification—however data-driven—concentrates epistemic power in a single agency that, like all institutions, harbors blind spots.
The optimal balance remains elusive. Singapore’s technocratic governance has historically navigated such trade-offs adeptly, adjusting policies as evidence accumulates. The transitional provisions built into the reforms suggest policymakers recognize implementation risks. Whether these safeguards prove sufficient will emerge over the next eighteen months as providers, employers, and individual learners respond to the new incentives.
What This Means for Stakeholders
For employers: The reforms create opportunities to influence training supply by directing sponsorship toward strategically valuable skills. Forward-thinking HR departments should inventory critical competencies, identify skill gaps, and proactively engage training providers to develop relevant curricula. SMEs, often lacking structured training budgets, may face disadvantages unless industry associations or government intermediaries help aggregate demand.
For training providers: Survival requires pivoting toward corporate partnerships and employer-sponsored enrollments. This means investing in business development capabilities, building industry advisory boards, and potentially consolidating to achieve scale. Providers serving niche or emerging fields face particularly acute pressures—they must either find creative ways to demonstrate industry demand or accept exit from the subsidized market.
For individual learners: Self-funded skill development becomes costlier and riskier. Prudent strategies include leveraging Career Transition Programs when making significant pivots, prioritizing employer-sponsored opportunities where available, and focusing SkillsFuture credits on courses appearing on SSG’s approved skills list. Mid-career workers should proactively discuss training needs with employers to access sponsorship.
For policymakers elsewhere: Singapore’s experiment offers lessons beyond its borders. The employer-sponsorship threshold provides a demand-side filter without abandoning universal access—a model potentially applicable in other advanced economies facing similar efficiency-equity trade-offs. The data-driven skills identification methodology, while imperfect, represents an improvement over purely expert-driven approaches. And the transitional framework demonstrates how aggressive policy reforms can incorporate adjustment periods to mitigate disruption.
The Bigger Picture: Singapore’s Perpetual Adaptation
Step back from the technical details, and the SkillsFuture reforms embody a deeper pattern: Singapore’s continuous recalibration in response to shifting circumstances. The 2015 SkillsFuture launch represented an initial bet on individual empowerment and lifelong learning. A decade’s experience has revealed implementation challenges—misaligned incentives, quality concerns, sustainability questions. The 2025-26 reforms adjust the model based on this learning.
This adaptive approach—launching initiatives, monitoring outcomes, adjusting parameters—characterizes Singapore’s developmental trajectory. The country pivoted from entrepôt trade to manufacturing to services to knowledge economy not through prescient master plans, but through iterative experimentation and course correction. The SkillsFuture reforms continue this tradition.
Yet adaptation has limits. Each course correction narrows future options. Path dependencies emerge. The shift toward employer-driven training may prove difficult to reverse if individual-initiative learning atrophies. Data-driven skill identification, once institutionalized, creates constituencies defending existing methodologies. Singapore’s policymakers must balance the need for optimization with preserving optionality.
Conclusion: The Test Ahead
The SkillsFuture funding tightening represents a calculated bet: that aligning training subsidies with employer demand and labor market data will enhance returns on human capital investment without unduly compromising access or innovation. It’s a quintessentially Singaporean solution—technocratic, efficiency-oriented, data-driven, yet wrapped in rhetoric of lifelong learning and social mobility.
Whether the bet pays off depends on execution and adaptation. Will the employer-sponsorship threshold effectively filter quality while preserving access for vulnerable workers? Will the Skills List methodology prove sufficiently forward-looking, or will it systematically underweight emerging capabilities? Will training providers adapt successfully, or will the sector consolidate in ways that reduce diversity and experimentation?
The answers will emerge gradually as the reforms take effect. Melissa Tan, the training provider director pondering her center’s future that humid December afternoon, exemplifies the stakes. Her ability to navigate the new landscape—finding corporate partners, aligning offerings with approved skills, maintaining quality—will determine not just her business survival but the aggregate health of Singapore’s training ecosystem.
For a small, open economy in a volatile world, the quality of that ecosystem matters immensely. Singapore’s prosperity rests not on natural resources or scale, but on its people’s capabilities. As artificial intelligence reshapes work, climate imperatives transform industries, and geopolitical tensions fragment global markets, continuous skill upgrading becomes not a policy choice but an existential imperative.
The SkillsFuture reforms, whatever their shortcomings, recognize this reality. They represent not the final word on lifelong learning policy, but another iteration in Singapore’s ongoing experiment in sustaining adaptability at the national scale. The city-state’s track record suggests it will continue adjusting, learning, and recalibrating as conditions evolve.
That flexibility—the institutional capacity to course-correct without abandoning core commitments—may prove Singapore’s most valuable skill of all.
Sources:
- SkillsFuture Singapore Official Announcement, January 27, 2026
- Skills Demand for the Future Economy Report 2025
- TPGateway SSG Funding Guidelines
- The Economist, “Retraining Low-Skilled Workers,” Special Report, January 2017
In a sleek laboratory at the University of Science and Technology of China in Hefei, researchers huddle around the Jiuzhang photonic quantum computer, a machine that can complete certain computational tasks in 200 seconds that would take classical supercomputers an estimated half-billion years. Just down the corridor, graduate students test components for next-generation electric vehicle batteries, their work funded by partnerships with BYD and Contemporary Amperex Technology. This scene, replicated across dozens of Chinese research institutions, captures a profound transformation: China’s evolution from the world’s factory floor to an innovation powerhouse where academic research increasingly determines economic competitiveness.
The numbers tell a remarkable story. In 2025, China’s research and development spending reached 2.8 percent of GDP, surpassing the average level of OECD countries for the first time, according to the National Bureau of Statistics. This milestone represents more than statistical achievement—it signals a fundamental reorientation of the world’s second-largest economy toward knowledge-intensive growth. With R&D expenditure rising 8.9 percent year-on-year to exceed 3.6 trillion yuan in 2024, China now stands as the world’s second-largest R&D investor, trailing only the United States but gaining ground rapidly.
Yet China’s research-driven transformation extends far beyond headline spending figures. The country has systematically built an innovation ecosystem where universities, research institutes, and industry collaborate with unprecedented intensity. The results manifest across multiple dimensions: Chinese institutions now dominate the Nature Index rankings, with nine of the world’s top ten academic institutions coming from China, while patent applications reached 1.8 million in 2024, accounting for nearly half of the global total. In strategic sectors from artificial intelligence to quantum computing, electric vehicles to biotechnology, academic research increasingly provides the foundation for commercial breakthroughs that reshape global markets.
This article examines ten distinct ways that China’s academic and research institutions fuel economic expansion. Drawing on the latest data from 2025-2026, it analyzes how university-industry partnerships, talent pipelines, patent commercialization, and regional innovation clusters collectively drive China’s transition toward innovation-led growth. The analysis also acknowledges persistent challenges—inefficiencies in spending allocation, geopolitical tensions constraining international collaboration, and questions about research quality versus quantity—that complicate assessments of China’s research performance. Understanding these dynamics matters not only for evaluating China’s economic trajectory but for anticipating shifts in global technological leadership and competitive advantage.
1. Building a World-Class Talent Pipeline Through Elite Universities
China’s research-driven economic growth begins with human capital cultivation at elite universities that have rapidly ascended global rankings. Tsinghua University and Peking University, China’s flagship institutions, consistently rank among the world’s top 20 universities and produce thousands of STEM graduates annually who populate both domestic industries and international research labs. The University of Science and Technology of China now ranks as the top university in China and second globally in the Nature Index with a total paper count of 2,585, demonstrating research output that rivals Harvard.
This talent pipeline operates at unprecedented scale. China produces more than four million STEM graduates annually, creating the world’s largest pool of technically trained workers. These graduates don’t merely fill existing positions—they drive innovation across emerging sectors. At Zhejiang University, dubbed the “mother of little dragons” because so many founders of top startups, including DeepSeek and Unitree, came from its programs, students transition seamlessly from academic research to entrepreneurship, often with university support providing subsidized infrastructure, mentorship, and capital.
The quality of this talent pool has improved alongside its expansion. Chinese universities have invested heavily in attracting top faculty, including returnee scholars from Western institutions and international researchers. The “Thousand Talents Program” and similar initiatives, despite generating geopolitical controversy, successfully recruited experienced researchers who elevated China’s academic capabilities. These faculty members not only conduct research but train the next generation, creating multiplier effects that compound over time.
Beyond individual institutions, China has developed tiered excellence through initiatives like Project 985 and the Double First-Class Construction project, which concentrate resources at top universities while raising standards across the system. This hierarchical approach allows specialization: while Tsinghua excels in engineering, Peking University leads in humanities and social sciences, and USTC dominates in physics and quantum research. Such specialization enables Chinese universities to compete globally across multiple disciplines simultaneously, rather than concentrating strengths in limited areas.
2. Dominating Global Patent Filings and Intellectual Property Creation
China’s intellectual property generation has reached extraordinary levels, fundamentally altering global innovation dynamics. The country’s patent filing surge reflects not merely bureaucratic productivity but increasingly sophisticated research capabilities that translate into commercial applications. In 2024, China maintained its position as the global leader with 1.8 million patent applications, a figure that dwarfs the 501,831 applications filed in the United States and represents nearly half the global total.
These patents span critical technological domains. Computer technology, electrical machinery, and digital communications lead filing activity, sectors where China seeks competitive advantage and where patents can protect lucrative markets. Huawei Technologies alone filed 6,600 Patent Cooperation Treaty applications in 2024, making it the world’s most prolific corporate filer and demonstrating how Chinese firms use IP strategy to secure market position. Contemporary Amperex Technology, the battery manufacturer, ranked fifth globally with nearly 2,000 applications, illustrating patent activity in sectors like electric vehicles where China has already achieved market dominance.
The quality question surrounding Chinese patents deserves nuanced assessment. Critics correctly note that quantity doesn’t equal quality, and that some Chinese patent filings have historically aimed to meet bureaucratic targets rather than protect genuine innovations. The Chinese government has acknowledged this concern, reducing subsidies that encouraged low-quality filings and implementing stricter quality checks, meaning that while the total number is still impressive, there is a clear focus on ensuring patents are meaningful. Recent data suggests improvement: Chinese patent citations have increased, foreign filings (an indicator of commercial value) have grown, and Chinese-origin patents increasingly appear in high-value litigation globally.
Patent commercialization presents another dimension of economic impact. Chinese universities and research institutes have established technology transfer offices that actively license patents to industry. Tsinghua University operates dedicated tech transfer infrastructure designed to ensure that research outcomes result in products and services that benefit the public, transforming innovations from concept to real-world application. This commercialization creates direct economic value through licensing revenues while generating spillover effects as patented technologies diffuse through supply chains.
3. Forging Deep University-Industry Partnerships and Tech Transfer Hubs
The integration of academic research with industrial application has become a hallmark of China’s innovation system, creating feedback loops where industry funding supports university research that generates commercially relevant findings. This model differs from Western arms-length relationships, instead featuring close collaboration that accelerates technology transfer. Major tech firms maintain extensive research partnerships with leading universities, jointly funding labs, co-supervising graduate students, and sharing research facilities.
The Tsinghua Berkeley Shenzhen Institute exemplifies this model, bringing together U.S. expertise and technological capabilities developed by U.S. professors with Chinese commercialization infrastructure. While such partnerships have generated security concerns in Washington, they demonstrate how Chinese institutions leverage global knowledge networks while building domestic capabilities. Similar institutes linking Chinese universities with international partners have proliferated, particularly in fields like artificial intelligence, semiconductor design, and renewable energy.
Regional tech transfer hubs amplify these partnerships. The China International Technology Transfer Center, established by the Ministry of Science and Technology, promotes technology transfer between universities, research centers, and industry while facilitating international collaboration. These platforms reduce transaction costs associated with moving research from lab to market, providing matchmaking services, incubation support, and commercialization expertise that individual universities might lack.
Financial mechanisms support this ecosystem. Universities increasingly participate as limited partners in venture funds, with Tsinghua University, Peking University, Fudan University, and others establishing science and technology funds that invest directly in startups commercializing university research. In 2024, Sichuan Province partnered with Tsinghua to establish a 10 billion yuan University Science and Technology Achievement Transformation Fund, providing patient capital for translating research into commercial products. Such funds align university incentives with commercialization outcomes while providing startup capital for ventures emerging from academic research.
The economic impact extends beyond individual transactions. Systematic university-industry collaboration creates knowledge spillovers as researchers gain practical problem-solving experience while industry partners access cutting-edge findings. Graduate students exposed to industry challenges produce more relevant research, while companies gain early access to emerging technologies before competitors. These advantages compound across sectors, from pharmaceuticals where university labs conduct drug discovery research funded by biotech firms, to semiconductors where university-designed architectures inform commercial chip development.
4. Achieving Dominance in Strategic High-Tech Sectors
China’s research excellence increasingly concentrates in sectors deemed strategically critical, where academic breakthroughs directly enhance national competitiveness and economic performance. This focused approach reflects deliberate policy choices that channel research funding toward areas with commercial and security significance, creating clusters of excellence that drive sectoral leadership.
Artificial intelligence represents perhaps the clearest example. Chinese institutions have rapidly advanced AI capabilities, with applications ranging from facial recognition and natural language processing to autonomous systems. The release of DeepSeek-R1 in early 2025, developed by researchers with ties to Chinese universities, demonstrated that Chinese AI development could achieve competitive performance while requiring far less computational power than Western models—a crucial advantage given semiconductor access constraints. Universities provide the talent pipeline, with institutions like Tsinghua embedding AI throughout curricula and research programs while companies like Alibaba, Tencent, and Baidu recruit graduates and fund academic research.
Quantum computing showcases similar dynamics. Chinese researchers have achieved multiple breakthroughs, including the Jiuzhang photonic quantum computer that performed a boson-sampling task in 200 seconds that would have taken a classical supercomputer an estimated half-billion years. Pan Jianwei, a quantum physicist and Chinese Academy of Sciences academician, has built a formidable research group at USTC that leads globally in quantum communications and ranks among the world’s best in quantum computing. China’s quantum program spans computing, communications, and sensing, with quantum computing firms increasing from 93 in 2023 to 153 in 2024, a rise of nearly 40 percent.
Electric vehicle and battery technology illustrates how academic research translates into market dominance. Chinese universities conduct extensive research on battery chemistry, power electronics, and electric drivetrain design, often in partnership with firms like BYD and CATL. These collaborations have helped China achieve commanding market positions: the country produced over 16 million new energy vehicles in 2025, accounting for more than half of domestic car sales and roughly two-thirds of global electric vehicle production. University research in materials science enabled improvements in battery energy density, charging speed, and cost that made this scale possible.
Biotechnology and pharmaceuticals represent an emerging area of strength. While China historically lagged in drug development, academic research has accelerated. Universities conduct basic research in genetics, protein folding, and disease mechanisms that inform drug discovery, while pharmaceutical firms increasingly partner with academic labs. The pandemic accelerated vaccine and therapeutic development, with Chinese academic institutions contributing to multiple COVID-19 vaccines. Looking forward, quantum computing applications in drug discovery could compound these advantages, as Chinese startups explore using quantum algorithms for molecular modeling and compound screening.
5. Advancing the Made in China 2025 Initiative Through Research
The Made in China 2025 initiative, launched in 2015 to transform China into a high-tech manufacturing powerhouse, has fundamentally relied on academic and research contributions to achieve its ambitious goals. While the program officially disappeared from public discourse in 2018 amid international criticism, its core objectives have persisted under alternative frameworks, with universities playing central roles in developing technologies across target sectors.
Assessment of Made in China 2025’s success yields mixed but generally positive results. A 2024 analysis found that 86 percent of the over 260 goals proposed under the plan have been achieved, with targets in sectors such as electric vehicles and renewable energy far surpassed. Academic research contributed significantly to sectors where China exceeded targets: renewable energy benefited from university research in solar cell efficiency and wind turbine design, while electric vehicles drew on battery and power electronics research conducted at universities nationwide.
Achievements vary substantially across sectors. In robotics, Chinese universities conduct extensive research in control systems, machine vision, and human-robot interaction that supports the country’s industrial automation. By 2025, China accounted for approximately 54% of all new industrial robot installations, driven partly by domestic suppliers whose technologies often originate in university labs. Agricultural machinery and biopharmaceuticals achieved all stated goals, with university contributions in precision agriculture technology and biological manufacturing proving crucial.
However, significant gaps remain in advanced semiconductors and commercial aircraft—precisely the areas where academic research faces greatest challenges. Despite massive investment, China continues relying on foreign lithography equipment and chip design software, constraints that limit progress despite strong university research programs. The semiconductor challenge illustrates limits of academic research alone: while Chinese universities produce excellent research in chip architecture and materials science, translating findings into manufacturing capabilities requires equipment, processes, and tacit knowledge that prove harder to acquire.
The program’s university-industry collaboration mechanisms have driven technology diffusion. Government guidance funds, many managed through university-affiliated entities, channel capital toward commercializing research. The third iteration of the China Integrated Circuit Industry Investment Fund, at $47.5 billion, and a new $8.2 billion government guidance fund for AI investments in January 2025 both aim to commercialize university research at scale. These funds explicitly prioritize transforming academic findings into industrial capabilities, creating financial incentives that align research agendas with national strategic goals.
6. Attracting Global Talent and Leveraging Diaspora Knowledge Networks
China’s research ascent has been significantly enhanced by talent attraction programs that bring international expertise into Chinese institutions while leveraging overseas Chinese researchers’ knowledge and networks. These initiatives address a historical challenge—brain drain to Western universities and companies—by creating incentives for talented researchers to work in China, either permanently or through collaborative arrangements.
The Thousand Talents Program, despite becoming controversial and largely discontinued amid U.S. security concerns, successfully recruited experienced researchers from abroad. While exact numbers remain unclear, estimates suggest thousands of scientists and engineers returned to China, bringing expertise gained at top Western institutions. Many established research groups at Chinese universities that rapidly achieved international recognition, accelerating China’s research capabilities in fields from materials science to artificial intelligence.
Successor programs continue talent recruitment through different mechanisms. Many Chinese universities offer competitive salaries, research funding, and laboratory facilities that rival Western institutions, particularly for mid-career researchers who might struggle to secure major grants or tenure in the United States or Europe. The appeal extends beyond compensation: Chinese researchers often access larger research teams, more willing industry partners, and faster paths from research to application given China’s manufacturing capabilities and less restrictive regulatory environment in some domains.
Chinese diaspora scientists and engineers, even when remaining abroad, contribute to China’s research ecosystem through collaborations, conferences, and knowledge exchange. Universities maintain extensive international partnerships that facilitate researcher exchanges, joint publications, and shared facilities. While geopolitical tensions have constrained some collaborations, particularly in sensitive technologies, broad networks persist across fields from climate science to mathematics.
These talent flows create economic value through multiple channels. Experienced researchers accelerate capability development, shortening learning curves and avoiding dead ends that junior researchers might pursue. Their international networks provide access to global knowledge while their presence signals institutional quality that attracts additional talent. Returnees often maintain connections abroad that facilitate technology licensing, equipment acquisition, and recruitment of additional researchers, creating network effects that compound advantages.
National talent recruitment complements institutional efforts. Research by China’s national talent recruitment programs shows measurable impact, with “talent hats” improving performance and encouraging collaboration, particularly benefiting experimental and applied research that feeds into commercial innovation. This structured support helps recruited talent navigate China’s academic system, access funding, and build research teams quickly.
7. Cultivating Regional Innovation Clusters and Science Parks
China’s geography of innovation features concentrated regional clusters where universities, research institutes, and industry collocate, generating agglomeration effects that enhance productivity and accelerate knowledge diffusion. These innovation clusters operate at city and sub-city scales, creating dense networks where ideas flow rapidly from research to application.
Beijing’s Zhongguancun district exemplifies this model, functioning as China’s Silicon Valley with concentrations of universities including Tsinghua and Peking, Chinese Academy of Sciences institutes, and thousands of technology companies ranging from startups to giants like ByteDance and Baidu. The proximity enables researchers to consult for companies, graduate students to intern at tech firms, and entrepreneurs to recruit talent directly from university labs. Zhongguancun firms collectively hold hundreds of thousands of patents, many originating from university research, while venture capital flows abundantly given the density of investors and deal flow.
Shenzhen demonstrates how cities without prestigious traditional universities can build innovation clusters through different mechanisms. The city hosts research institutes affiliated with leading universities, including Tsinghua Berkeley Shenzhen Institute and Chinese University of Hong Kong Shenzhen, while its manufacturing ecosystem provides unparalleled resources for hardware innovation. The combination of research capabilities and manufacturing prowess enables rapid prototyping and iteration, advantages that hardware startups globally struggle to replicate. Companies like BYD, Huawei, and DJI have grown into global leaders while maintaining deep ties to research institutions.
Shanghai, Hangzhou, and Guangzhou each cultivate distinct cluster characteristics. Shanghai excels in life sciences and semiconductors, leveraging Fudan University and Shanghai Jiao Tong University alongside pharmaceutical and chip firms. Hangzhou benefits from Zhejiang University’s research strength and Alibaba’s presence, creating a digital economy cluster. Guangzhou’s proximity to Hong Kong and manufacturing base in Guangdong supports hardware and automotive innovation.
Provincial governments actively support cluster development through subsidies, infrastructure investment, and preferential policies. Multiple provinces have established university science and technology funds and transformation funds that commercialize local university research. Beijing invested 327.84 billion yuan in R&D, representing 6.58 percent of its GDP, while Shanghai reached 4.35 percent, both far exceeding the national average. These investments support research universities, technology parks, and innovation districts that anchor regional clusters.
The economic impacts of these clusters extend beyond direct participants. Supplier networks develop around anchor firms, creating ecosystems where specialized services—from IP law to equipment calibration—flourish. Knowledge spillovers occur as employees move between firms or start new ventures, taking expertise developed elsewhere. The density of technical talent creates labor markets thick enough to support specialized skills, reducing costs for firms seeking particular capabilities.
8. Leading in Basic Research and Scientific Publications
China’s basic research capabilities have advanced dramatically, moving from marginal participant to global leader in high-quality scientific output across multiple disciplines. This transformation in fundamental research creates knowledge foundations that support applied research and commercial innovation, while demonstrating research maturity beyond merely scaling up existing approaches.
The Nature Index, which tracks contributions to research articles in elite scientific journals, illustrates China’s ascent. The Chinese Academy of Sciences maintains first position globally with a 2024 Share of 2,776.90, extending its lead over second-place Harvard University. More remarkably, Chinese institutions increased from having 31 institutions in the Nature Index top 100 in 2022 to 43 in 2024, demonstrating breadth alongside excellence at the very top.
China’s strength concentrates particularly in physical sciences and chemistry. In the Nature Index physical sciences rankings, China holds eight of the top ten positions globally, with institutions including CAS, USTC, Tsinghua, and Peking University dominating. In earth and environmental sciences, similar patterns emerge. These subject areas represent traditional Chinese strengths but also fields with enormous economic significance—materials science informs semiconductor and battery development, while earth science research supports renewable energy siting and climate adaptation.
Basic research output has practical economic significance beyond prestige. Fundamental discoveries in quantum physics enable quantum computing development, while advances in materials science inform battery chemistry improvements. Chinese researchers’ work on catalysis and chemical processes contributes to pharmaceutical manufacturing and industrial chemistry. The lag between basic research and commercial application varies by field, but systematic investment in fundamental science creates option value—the possibility that today’s esoteric research enables tomorrow’s breakthrough products.
China’s basic research investment has grown substantially, with spending on basic research, applied research, and experimental development growing by 10.7 percent, 17.6 percent, and 7.6 percent respectively in 2024. This reflects government recognition that leadership requires discovery, not merely development. While critics note that China’s basic research still lags the United States in some metrics—Nobel Prize recognition, citations of most influential papers—the trajectory shows rapid improvement.
Institutional structures support basic research excellence. The Chinese Academy of Sciences operates as a massive research organization with over 100 institutes conducting fundamental research across disciplines. Universities emphasize publication in top-tier international journals, creating incentives for high-quality basic research. State Key Laboratories provide sustained funding for long-term research programs, insulating researchers from short-term commercial pressures that might discourage fundamental inquiry.
9. Incubating Startups and Fostering Entrepreneurial Ecosystems
Chinese universities have evolved into startup incubators, systematically commercializing research through new venture creation while cultivating entrepreneurial mindsets among students and faculty. This transformation reflects both institutional evolution and policy support, creating pathways from academic research to market impact that generate economic growth and employment.
China hosts 158 unicorns—privately held companies valued above $1 billion—in 2025, with collective market capitalization exceeding $500 billion. Many trace origins to university research or were founded by recent graduates. DeepSeek, the AI startup that shocked Western observers with its efficient large language model, emerged from research at Chinese universities. Unitree, which produces advanced quadruped and humanoid robots, similarly benefited from Zhejiang University’s ecosystem. These unicorns don’t merely represent paper wealth—they employ thousands of workers, generate tax revenue, and drive innovation in strategic sectors.
University-affiliated venture funds increasingly invest in student and faculty startups. Fudan University established a science and technology innovation mother fund with initial scale of 1 billion yuan in 2023, expanded to national and overseas funds by 2025. These funds provide patient capital while leveraging university expertise to evaluate technical viability. Beyond capital, universities offer incubation services including subsidized laboratory space, business mentorship, and IP licensing on favorable terms.
The startup ecosystem extends beyond individual unicorns to encompass thousands of small technology companies. Beijing alone hosts over 1.6 million micro, small, and medium enterprises, many technology-focused, which contribute more than 30% of the city’s tax revenue, more than 40% of its revenue, more than 50% of its patents for technological inventions and more than 60% of its jobs. Universities feed this ecosystem with talent, technology, and entrepreneurial energy.
Funding dynamics have shifted recently, with government-affiliated investors replacing some foreign venture capital following U.S.-China tensions. In Q1 2025, government-affiliated investment companies took part in roughly 16% of funding rounds, up from less than 5% a decade earlier. This substitution maintains capital availability for university spin-offs while aligning investment with national priorities in areas like semiconductors, AI, and advanced manufacturing.
Cultural shifts complement structural support. Entrepreneurship has gained social prestige in China, with successful founders achieving celebrity status and “mass entrepreneurship and innovation” becoming a government slogan. Universities cultivate entrepreneurial mindsets through courses, competitions, and exposure to startup ecosystems. This cultural change matters economically because it increases the supply of potential entrepreneurs willing to leave secure academic or corporate positions to commercialize research findings.
10. Generating Productivity Spillovers and Export Competitiveness
The cumulative impact of China’s research ecosystem manifests in productivity improvements and export performance across the broader economy, as knowledge generated in universities and research institutes diffuses through supply chains, labor mobility, and technology adoption. These spillover effects represent perhaps the most important but least visible way that research drives economic growth.
Total factor productivity growth—the portion of economic expansion not explained by capital and labor inputs—depends fundamentally on technological progress and efficiency improvements. China experienced TFP stagnation in recent years amid challenges including resource misallocation and debt accumulation. However, research-intensive sectors show different patterns, with productivity gains concentrated in industries where academic research contributes to process improvements and product innovation.
Manufacturing competitiveness increasingly depends on research capabilities. Chinese manufacturers in sectors from electric vehicles to consumer electronics benefit from domestic research that generates intellectual property, reduces dependence on foreign technology licensing, and enables rapid product iterations. When BYD develops new battery chemistries in partnership with university researchers, it gains cost and performance advantages over competitors using licensed technology. Similar dynamics play across industries, from pharmaceutical manufacturing to telecommunications equipment.
Export performance reflects these advantages. China’s exports of high-tech products have grown dramatically, with the country now leading globally in electric vehicle exports and dominating solar panel production. These export successes rest on research capabilities that enable Chinese firms to compete not merely on price but on technical sophistication. Research also supports export competitiveness indirectly by training engineers who staff export-oriented manufacturers and generate process innovations that improve quality while reducing costs.
Knowledge diffusion mechanisms amplify research impacts. Personnel mobility transfers knowledge as researchers move between universities and companies, or as university-trained engineers join manufacturers. Supplier relationships spread knowledge when technology firms work with component suppliers, sharing technical requirements and problem-solving approaches. Industry-university conferences, training programs, and consulting relationships create additional diffusion channels.
Measurement challenges complicate quantification of these spillovers. Standard economic statistics struggle to capture knowledge flows, making spillover effects difficult to measure precisely. However, sectoral patterns provide suggestive evidence: industries with stronger university linkages generally show higher productivity growth, while regions with denser research ecosystems tend toward faster economic expansion. China’s rise in the Global Innovation Index, entering the top ten for the first time in 2025, reflects accumulated spillover effects as research capabilities translate into broader innovative capacity.
Looking Forward: Challenges and Sustainability
China’s research-driven economic growth faces significant challenges alongside its impressive achievements. Understanding these limitations matters for realistic assessment of the model’s sustainability and likely evolution.
Efficiency concerns deserve serious attention. China’s rapid R&D spending growth doesn’t automatically translate into proportional innovation output. Some investment goes toward duplicative projects as local governments compete for prestige, while other spending supports research of questionable commercial relevance. The government has acknowledged these inefficiencies, adjusting policies to emphasize quality over quantity, but fundamental tensions remain between bureaucratic incentive systems and innovative discovery’s unpredictable nature.
Geopolitical tensions increasingly constrain China’s research ecosystem. U.S. export controls limit access to advanced semiconductor manufacturing equipment and high-end AI chips, handicapping research in affected areas. International collaborations have contracted in sensitive technologies, reducing knowledge flows that previously accelerated Chinese capabilities. Talent recruitment programs face scrutiny and restrictions, complicating efforts to attract overseas researchers. These constraints particularly impact fields where China lags technically and would most benefit from international cooperation.
Quality versus quantity remains an ongoing question in Chinese research. While metrics like patent filings and publication counts show impressive growth, citation impact and breakthrough discoveries represent different challenges. China has produced incremental advances across many fields but fewer paradigm-shifting discoveries that redefine technological possibilities. Whether this reflects measurement timing—with current investment ultimately yielding breakthrough discoveries—or more fundamental limitations remains contested among observers.
The transition from catch-up growth to frontier innovation presents challenges. When developing countries can license, reverse-engineer, or recruit talent from technological leaders, innovation becomes primarily a deployment challenge. At the frontier, innovation requires original discovery with higher uncertainty and failure rates. China’s research system, optimized for rapid scaling and directed toward specific goals, may struggle with frontier research’s inherent unpredictability and longer time horizons.
Sustainability questions also arise regarding the heavy state role in directing research agendas. While state coordination enables focused efforts in strategic technologies, it risks missing opportunities in areas that appear less important to planners but might prove transformative. The balance between directed research and investigator-initiated exploration remains under constant negotiation in China’s system, with economic implications depending on achieving appropriate balance.
Despite these challenges, China’s research ecosystem has demonstrated remarkable capabilities and resilience. The country’s research spending continues growing faster than GDP, indicating sustained commitment despite economic headwinds. Universities continue ascending global rankings, patent quality improves alongside quantity, and commercialization mechanisms mature. The combination of scale, focus, and institutional learning suggests that China’s research contributions to economic growth will persist and likely expand, even if the path forward presents more challenges than the catch-up phase.
The global implications extend beyond China itself. As Chinese research capabilities rise, they create both opportunities and tensions for the broader international research community. Collaboration with Chinese institutions offers access to unique capabilities and resources, while competition intensifies in many technology domains. The resulting dynamic—part collaboration, part competition—will shape innovation trajectories globally in coming decades, with economic consequences extending far beyond China’s borders as research-driven competitive advantages shift and new technological possibilities emerge from the world’s largest scientific enterprise.

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide

Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Is SPY Overvalued in September 2026? Fed Rate Hike Odds & Intrinsic Value
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
The New Executive Gold Standard: Top 10 Companies Lavishing Unprecedented Perks on CEOs and CFOs in 2025–2026
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Analysis4 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025