Economy & Markets
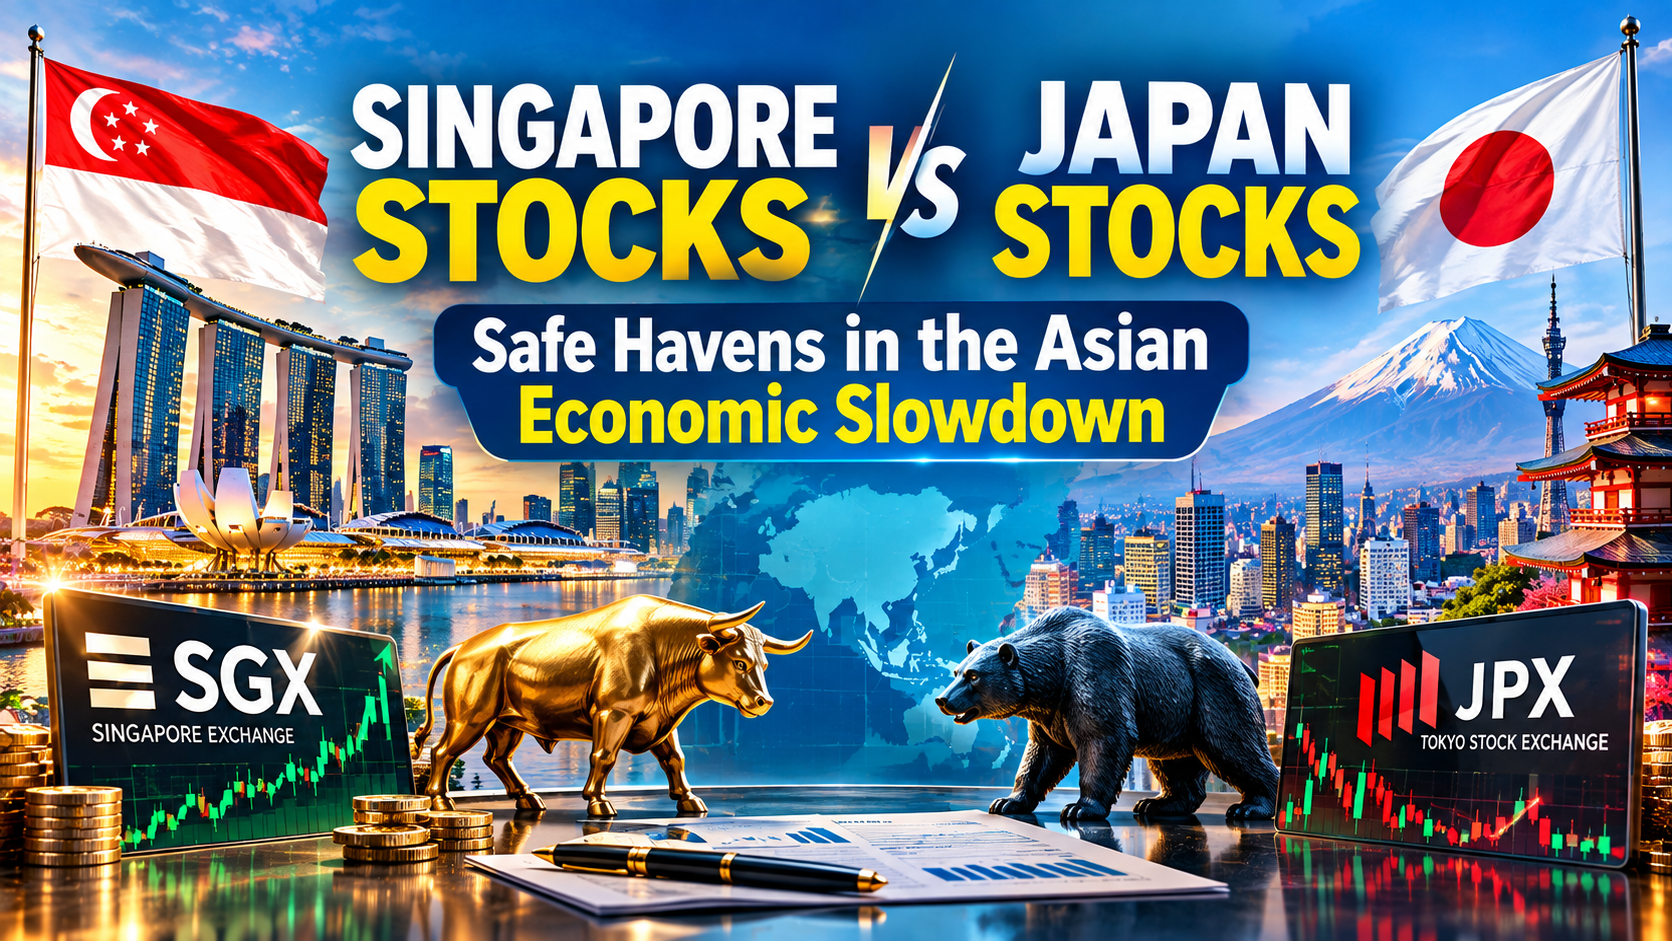
Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Key Takeaways
- Singapore’s STI is being driven higher by its three local banks, whose growing wealth-management fee income — unburdened by capital-buffer requirements — is fueling rising dividend payout ratios.
- Japan’s Nikkei 225 has been far more volatile in September 2026, swinging from an intraday high near 66,400 to a 1.93% drop to 64,011 in the same week, as oil-driven bond-yield spikes hit AI-linked names like SoftBank and Advantest hardest.
- Singapore’s MAS has committed a combined S$8 billion across its Equity Market Development Programme, Anchor Fund, and Financial Sector Development Fund to deepen SGX liquidity and attract listings.
- Japanese equities’ “safe haven” reputation looks fragile in the current environment, per Capital Economics, because Bank of Japan rate-hike expectations are now colliding with imported inflation from elevated oil prices.
- For income-focused investors, Singapore’s REITs and bank stocks currently offer more stable, less rate-sensitive yield than Japan’s tech-heavy, more volatility-prone index.
As the global economy absorbs the twin shocks of a prolonged US-Iran war and an AI-driven technology boom, investors have been asking which Asian market deserves the “safe haven” label this cycle: Singapore or Japan. The honest answer, based on September 2026 trading, is that they’re behaving very differently — and dividend-seeking investors should understand why before allocating capital to either.
Singapore: Bank-Led Stability
Singapore’s benchmark Straits Times Index (STI) has been underpinned largely by its financial sector. The three local banks — DBS, OCBC, and UOB — have benefited from Singapore’s status as a regional wealth-management hub, with assets under management climbing as global capital seeks stability amid geopolitical tensions elsewhere. Crucially, fee income from wealth management isn’t subject to the same regulatory capital buffers as traditional lending, letting banks convert that income more efficiently into rising dividends per share.
Singapore’s regulators have also been proactively deepening the market. The Monetary Authority of Singapore (MAS) has layered a S$1.5 billion addition to its Financial Sector Development Fund on top of the existing S$5 billion Equity Market Development Programme launched in 2025, plus a further S$1.5 billion committed to an Anchor Fund aimed at attracting quality IPOs to the Singapore Exchange (SGX) — a combined push of roughly S$8 billion to boost liquidity and listings.
Singapore REITs: Yield With Nuance
Singapore-listed REITs (S-REITs) remain a core income vehicle, with the market-cap-weighted iEdge S-REIT index yielding roughly 6.3%, rising to 6.8–7.0% on an equal-weighted basis. But yield alone doesn’t tell the full story. Sasseur REIT, for example, delivered 10.2% DPU growth in the first half of 2026 on the back of strong Chinese outlet-mall sales — but that same exposure to Chinese consumption cuts both ways given China’s uneven recovery. Meanwhile, Mapletree Pan Asia Commercial Trust has seen its DPU pressured by weakening Japan occupancy (down to 56% from 75.1%) and negative rental reversion in China, even as Singapore itself now contributes 61% of its asset base. The lesson: not every “Singapore” dividend stock is a pure Singapore bet.
Japan: Higher Beta, Higher Risk
Japan’s Nikkei 225 tells a much choppier story. Earlier in September, the index surged over 2% in a single session to 66,399.84, riding broad tech-stock gains alongside South Korea’s Kospi. But within the same week, the picture flipped: the Nikkei 225 dropped 1.93% to 64,011, with the broader Topix slipping 0.65%, as elevated oil prices and rising global bond yields hit sentiment hard. AI and tech-linked names bore the brunt — Kioxia Holdings fell as much as 8.6%, SoftBank Group dropped up to 12%, and Advantest and Tokyo Electron both posted multi-percent declines.
The proximate trigger was Saudi Arabia shutting down its East-West pipeline — a key Hormuz-bypass route — which pushed oil prices higher and strengthened expectations that both the US Federal Reserve and the Bank of Japan would raise interest rates. That combination — imported energy inflation plus tighter domestic monetary policy — is precisely the scenario that undermines Japan’s traditional “safe haven” framing. As Capital Economics’ Marcel Theliant has noted, Japan’s safe-haven appeal currently looks fragile, with GDP growth momentum expected to cool as investment eases and exports soften.
Head-to-Head Comparison
| Metric | Singapore (STI / S-REITs) | Japan (Nikkei 225) |
|---|---|---|
| September 2026 volatility | Relatively stable, bank-led | High — swung from +2.1% to -1.9% within days |
| Key driver | Wealth-management fee income, MAS liquidity programs | AI/tech-stock sentiment, BOJ rate-hike expectations |
| Yield profile | ~3.5–6% (banks), 6.3–7% (S-REITs) | Lower dividend yields; more capital-appreciation focused |
| Rate sensitivity | Lower — banks benefit from higher rates | Higher — tightening BOJ policy pressures tech valuations |
| 2026 headline risk | China/Japan exposure within specific REITs | Oil-driven bond yields, Hormuz disruption spillover |
Why This Matters for Asian Equity Allocation
For investors explicitly seeking a defensive, income-generating position within Asia during the current global economy slowdown, the September 2026 data suggests Singapore’s bank- and REIT-led market has behaved more like a genuine safe haven than Japan’s tech-heavy index, which remains highly correlated to global risk sentiment and energy-driven rate expectations. That doesn’t make Japan uninvestable — some strategists still see the Nikkei trading toward 55,000–60,000 by year-end on reasonable valuations and BOJ-tightening-adjusted earnings growth — but it does mean Japan currently functions more as a leveraged growth play on the AI cycle than as ballast against volatility elsewhere in a portfolio.
Frequently Asked Questions
Is Singapore or Japan a better safe-haven stock market right now?
Based on September 2026 trading behavior, Singapore’s bank- and REIT-led market has shown more stability, while Japan’s Nikkei 225 has swung sharply due to its heavier weighting toward oil-sensitive, rate-sensitive tech names like SoftBank and Advantest.
Why are Singapore REITs attractive for dividend investors?
S-REITs currently yield roughly 6.3% on a market-cap-weighted basis and up to 7% equal-weighted, and Singapore dividends aren’t taxed at the individual level — though investors should check each REIT’s specific overseas exposure, as some carry meaningful Japan or China revenue concentration.
Why did Japanese tech stocks fall sharply in September 2026?
A Saudi pipeline shutdown pushed oil prices higher, strengthening expectations that both the Federal Reserve and the Bank of Japan would raise interest rates — a combination that hit AI and semiconductor-linked Japanese stocks particularly hard.

Every housing cycle produces a chorus of crash predictions, and 2026 has been no exception. But the data emerging through the third quarter tells a more measured story than the headlines suggest: this is a market undergoing what several major forecasters are now calling “The Great Recalibration” — not a collapse, but a prolonged, uneven reset in which affordability improves slowly, regionally, and unevenly rather than through a sharp price correction.
Key Takeaways
- No major forecaster — Fannie Mae, NAR, Zillow, Redfin, or Realtor.com — is projecting a national home price crash in 2026; forecasts cluster in a 1% to 4% annual price growth range.
- Existing home sales fell 4.2% in the first half of 2026, with June sales down 2.4% to a seasonally adjusted annual rate of 4.09 million units, according to the National Association of Realtors — softness driven by elevated mortgage rates, not distressed selling.
- 30-year fixed mortgage rates are expected to average roughly 6.3% through 2026, per consensus forecasts from Realtor.com, Redfin, and industry surveys — a “new equilibrium” rather than a return to sub-5% pandemic-era rates.
- Home values fell in 24 of the 50 largest US markets as of late 2025; Zillow projects that number to roughly halve to around 12 markets in 2026, indicating regional divergence rather than a uniform correction.
- Nearly two-thirds of prospective buyers (62%) have been waiting for rates to fall before purchasing — the same share that made the identical bet in 2025 and were wrong, underscoring the risk of timing the market on rate predictions alone.
The State of the 2026 Housing Market: Reset, Not Crash
The consensus among major housing economists — at Redfin, Zillow, NAR, Fannie Mae, and J.P. Morgan Global Research — is unusually aligned for a sector prone to disagreement: 2026 is a “recalibration” year, characterized by softening sales volume, modest price growth, and mortgage rates settling into a new, higher-than-pandemic-era range rather than a sharp downward price correction.
J.P. Morgan Global Research’s mid-2026 housing outlook noted that existing home sales pulled back 2.4% in June to a seasonally adjusted annual rate of 4.09 million units, extending a first-half 2026 decline of 4.2%. The bank attributed the softness directly to elevated mortgage rates rather than to distressed inventory or forced selling — a critical distinction from the dynamics that preceded the 2008 crash, where oversupply and subprime defaults, not rate-driven demand softness, drove the collapse.
Mortgage Rate Trajectory: The Central Variable
Mortgage rates remain the single most important variable shaping the 2026 housing market. Forecasts have converged around an average 30-year fixed rate near 6.3% for the year, with Fannie Mae’s Home Price Expectations Survey — which polls more than 100 housing economists — projecting home prices to rise a modest 1.7% in 2026 and 2% in 2027 under that rate assumption. Some forecasters see slightly more optimistic paths: S&P Global has projected an average closer to 5.77%, while Zillow has taken the more cautious position that rates will likely stay above 6% throughout 2026 despite gradual easing.
| Forecaster | 2026 Home Price Growth | 2026 Mortgage Rate (30-yr avg) |
|---|---|---|
| Fannie Mae | +3.2% | ~6.3% |
| National Association of Realtors | +4.0% (median price) | ~6.3% |
| Mortgage Bankers Association | +0.6% | ~6.3% |
| Realtor.com | +2.2% | ~6.3% |
| Zillow | +1.2% | Above 6% |
| Redfin | +1.0% | Low 6% range |
No forecaster in this table projects a price decline — the dispersion is between “modest growth” and “very modest growth,” which is the clearest quantitative rebuttal to crash narratives currently circulating in social media and lower-authority financial commentary.
Regional Divergence: Where the Real Risk Sits
The national picture obscures significant regional variation, and this is where “crash predictions” have the most factual grounding — at the metro level, not the national level. Zillow’s research noted that home values fell in 24 of the 50 largest US markets as of October 2025, with that number of declining markets expected to roughly halve to about 12 in 2026 as affordability improves. This implies that roughly a quarter of major US metros experienced genuine, if modest, price depreciation heading into 2026 — a regional reality that gets flattened into “national crash” narratives online but is more accurately described as localized correction concentrated in previously overheated Sun Belt and pandemic-boomtown markets.
Inventory: The Structural Wildcard
Inventory levels are projected to increase by approximately 8.9% to 12% in 2026, according to appraisal-industry forecasting, though they remain below pre-pandemic averages. This matters directly for crash risk: a genuine price collapse typically requires oversupply relative to demand. Current inventory growth, even at the high end of forecasts, is not projected to push supply into the oversupplied territory that preceded the 2008 downturn — it is a gradual normalization from historically tight conditions, not a supply glut.
The “Waiting for Rates to Fall” Trap
One of the more revealing data points for 2026 buyer psychology comes from a U.S. News survey: nearly two-thirds of prospective homebuyers (62%) were waiting for mortgage rates to fall before buying in 2026 — and the identical share (62%) made the same bet in 2025, and lost it, as rates did not fall meaningfully. This is a behavioral pattern directly analogous to the cash-hoarding trap in personal savings: postponing action based on a rate prediction that forecasters themselves have repeatedly gotten wrong carries its own opportunity cost, particularly if home prices continue their modest upward drift as most forecasters project.
Mortgage Rate Strategies for 2026 Buyers and Owners
- Rate locks with float-down options. With rates expected to hover in a narrow 6.0%–6.5% band rather than swing dramatically, a float-down provision on a rate lock offers modest downside protection without requiring buyers to time a broader market move.
- Adjustable-rate mortgages for shorter holding periods. For buyers expecting to sell or refinance within 5–7 years, ARMs priced meaningfully below the 6.3% fixed-rate consensus can reduce carrying costs without exposure to a 30-year rate commitment.
- Points purchases in a stable-rate environment. Because forecasters see rates stabilizing rather than falling sharply, buying down the rate with points becomes more mathematically attractive than in a falling-rate environment where a near-term refinance might otherwise recapture the cost.
- Regional due diligence over national headlines. Given that roughly a quarter of major metros were still seeing price declines heading into 2026, buyers and investors should underwrite specific metro-level inventory and price-trend data rather than relying on national crash or boom narratives.
Frequently Asked Questions
Is the US housing market going to crash in 2026?
No major housing forecaster — including Fannie Mae, NAR, Zillow, Redfin, and the Mortgage Bankers Association — projects a national price decline in 2026; forecasts range from roughly 0.6% to 4% price growth, with existing home sales projected to be flat to modestly higher.
Why do home sales keep falling if prices aren’t crashing?
Existing home sales fell 4.2% in the first half of 2026 primarily because elevated mortgage rates (averaging around 6.3%) are suppressing transaction volume, not because of distressed or forced selling — a key structural difference from the 2008 crash.
Should I wait for mortgage rates to drop before buying?
Roughly 62% of buyers made this bet in both 2025 and 2026, and rates did not fall meaningfully either year according to consensus forecasts; buyers evaluating this strategy should weigh the opportunity cost of continued modest home-price appreciation against uncertain rate movement.
Conclusion
The 2026 real estate data supports a “Great Recalibration” thesis, not a crash thesis: sales volume is softening under the weight of a stabilized-but-elevated 6.3% mortgage rate environment, national price growth remains positive across every major forecaster, and the genuine downside risk is concentrated regionally in a shrinking subset of previously overheated metros rather than distributed nationally. For buyers, sellers, and investors, the 2026 opportunity lies less in timing a crash that the data does not support and more in navigating rate strategy and regional selection with precision.
If you’ve followed coverage of Anthropic’s reported IPO preparations, you’ve likely seen a specific phrase repeated across Financial Times and Bloomberg reporting: Morgan Stanley is said to hold the “pole position” for the lead-left role on the offering. It sounds like insider jargon — and it is — but understanding what it actually means reveals a lot about how the largest IPOs in history get priced, sold, and stabilized after they start trading.
Key Takeaways
- “Lead-left” refers to the underwriting bank listed first on the cover page of an IPO prospectus — traditionally positioned on the left side of the page.
- The lead-left bank runs the bookbuilding process, sets the final offer price alongside the issuer, and typically earns the largest share of underwriting fees.
- Morgan Stanley reportedly holds the inside track for this role on Anthropic’s IPO, with Goldman Sachs running “neck-and-neck” for a top-tier co-lead position.
- JPMorgan, Citigroup, and Barclays are expected to round out the broader underwriting syndicate.
- The same three lead banks — Morgan Stanley, Goldman Sachs, JPMorgan — ran the book on the SpaceX IPO in June 2026, the current record holder for largest offering ever.
- For investors, the lead-left bank’s decisions directly shape share allocation, pricing discipline, and after-market stability.
The Origin of the Term (and Why It Still Matters)
The “lead-left” designation dates back to a literal physical convention: on the cover page of a printed IPO prospectus, underwriting banks are listed in order of importance, with the most senior bank’s name and logo positioned on the far left. Over decades, “lead-left” became shorthand for the bank running point on the entire transaction — even as prospectuses moved from print to digital filings.
Today, being lead-left signals to the market that a bank has taken primary responsibility for:
- Bookbuilding — soliciting and aggregating orders from institutional investors during the roadshow
- Price discovery — synthesizing investor demand into a final offer price recommendation for the issuer’s board
- Fee allocation — typically claiming the largest cut of the total underwriting discount, often in the 20–40% range of total fees depending on syndicate structure
- Stabilization — managing after-market trading support, including exercising the “greenshoe” over-allotment option to buy back shares if the stock trades below the offer price shortly after listing
Why the Role Matters More in a Deal This Size
For a conventional mid-sized IPO, the lead-left designation is largely an internal Wall Street prestige marker. For a deal of Anthropic’s reported scale — targeting a valuation near $2 trillion, which would rival or exceed SpaceX’s record-setting June 2026 debut — the stakes are dramatically higher.
A misjudged offer price on a deal this large can produce two very different bad outcomes:
- Underpricing: If shares are priced too conservatively relative to demand, the company leaves substantial capital on the table, and early flippers capture gains that could have gone to the company’s own balance sheet.
- Overpricing: If shares are priced too aggressively, the stock can “break issue” — trading below its offer price shortly after listing — which damages investor confidence and can make it harder for the company to raise capital in follow-on offerings.
SpaceX’s own trajectory illustrates this tension well: shares priced at $135, reaching a first-day peak near a $2.1 trillion market cap, before settling into a range closer to $1.5 trillion by late July. Managing that kind of post-listing volatility responsibly falls disproportionately on the lead-left bank’s trading desk.
Morgan Stanley vs. Goldman Sachs: Why Both Are in the Running
Reporting indicates Morgan Stanley and Goldman Sachs are “running neck-and-neck” for top billing on Anthropic’s deal — a genuinely competitive situation rather than a formality. Both banks bring distinct strengths:
| Factor | Morgan Stanley | Goldman Sachs |
|---|---|---|
| Prior AI-sector IPO experience | Co-led SpaceX (June 2026) | Co-led SpaceX (June 2026) |
| Institutional distribution network | Extensive global wealth management arm | Deep institutional and sovereign wealth relationships |
| Existing Anthropic relationship | Reported prior debt financing role | Reported prior debt financing role |
| Technology sector banking franchise | Historically strong in large-cap tech | Historically strong in large-cap tech and growth equity |
In practice, mega-deals of this size increasingly use joint lead-left structures or closely shared top billing, which allows the issuer to tap both banks’ distribution networks without fully subordinating either one — a structure that may ultimately be how Anthropic’s deal resolves this specific competitive tension.
How This Connects to Anthropic’s Debt Financing
It’s not coincidental that the banks reportedly competing for Anthropic’s lead underwriting roles are the same institutions that previously provided the company debt financing, and are now reportedly structuring a $15 billion pre-IPO credit facility. This dual relationship gives whichever bank secures lead-left status unusually deep, pre-existing visibility into Anthropic’s financial position — audited or not — heading into the roadshow.
What Retail Investors Should Take Away From the Lead-Left Story
- It’s a signal of seriousness, not a valuation guarantee. A bank agreeing to lead a deal at a reported $2 trillion target valuation suggests institutional confidence in achievable demand — it does not certify that the price is fundamentally justified.
- It affects share allocation indirectly. Retail brokerage partnerships for IPO share access are often negotiated through relationships with the lead-left and co-lead banks, meaning which banks lead the deal can shape (modestly) which retail platforms get any allocation at all.
- It affects after-market behavior. The lead-left bank’s stabilization activity in the days following listing can meaningfully dampen (or fail to dampen) early volatility — worth watching closely if you plan to trade in the first week after listing rather than the IPO itself.
FAQ
What does “lead-left” mean in an IPO?
It refers to the underwriting bank listed first — traditionally on the left side — of an IPO prospectus cover page, signifying the bank with primary responsibility for pricing, bookbuilding, and after-market stabilization.
Is Morgan Stanley confirmed as Anthropic’s lead-left bank?
Not yet confirmed. Reporting from the Financial Times indicates Morgan Stanley holds the “pole position” for the role, with Goldman Sachs running closely for a top-tier position, but no final syndicate structure has been publicly confirmed by Anthropic.
Do lead-left banks make more money than other underwriters?
Generally yes. The lead-left bank typically receives the largest share of the total underwriting fee pool, reflecting its greater responsibility and risk in the bookbuilding and pricing process.
Does the lead-left bank guarantee a successful IPO?
No. A strong lead-left bank improves the odds of an orderly process and pricing discipline, but cannot guarantee post-listing stock performance, as SpaceX’s own valuation compression after its June 2026 debut illustrates.
Pakistan’s KSE-100 is up nearly 19% year-on-year and within striking distance of its all-time high — even as the country’s structural trade deficit remains unresolved. Here’s the full picture.
Pakistan’s stock market is delivering one of the more remarkable emerging-market growth stories of 2026, even as the country’s underlying trade imbalance remains a live structural concern. Per Trading Economics, the KSE-100 fell to 178,213 points on August 18, 2026, losing 1.27% from the previous session — but the index remains up 18.99% compared to the same time last year and has climbed 1.30% over the past month, with the index having touched an all-time high of 189,556 points.
Key Takeaways
- The KSE-100 stood at 178,213 points on August 18, 2026, up 18.99% year-on-year, and within range of its all-time high of 189,556.
- The index has gained 10.89% over the past four weeks and 64.89% over the past twelve months by an alternate measure of the same rally.
- The rally is being driven by macro stabilisation, S&P’s credit upgrade (see Article 4), and renewed foreign portfolio inflows.
- Pakistan’s structural trade gap — imports consistently exceeding exports — remains unresolved even as equities rally.
- Historical precedent (2024’s record run) shows KSE-100 rallies have previously been fuelled by the largest foreign equity buying in a decade.
The scale of the multi-year rally is worth putting in context, because Pakistan’s equity market has been one of the standout performers globally over an extended stretch, not just a recent spike. The Trading Economics data shows the index gained 10.89% over a recent four-week window and 64.89% over the trailing twelve months, reaching successive all-time highs through late 2025 and into 2026 — from 170,249 in mid-December 2025 to 170,719 by year-end to 189,556 at its most recent peak.
This isn’t the first time Pakistan’s market has rallied on this scale, and the historical pattern is instructive. A Bloomberg report from a prior cycle describes the KSE-100 closing near a then-record high after gaining more than 30% in a single year, aided by foreign investors’ net purchases of $87 million in local shares — at the time, the highest level of foreign buying since 2014. The current rally, still building on that earlier momentum, reflects a continuation of the same foreign-inflow-driven dynamic, now reinforced by the macro stabilisation narrative detailed in Article 4: S&P’s July 22 upgrade of Pakistan’s sovereign credit rating to ‘B’ from ‘B-‘, alongside a 22-year-low fiscal deficit of 2.6% of GDP.
What the rally does not resolve, however, is Pakistan’s persistent external trade imbalance — a structural feature the equity euphoria sits somewhat uneasily alongside. Pakistan’s own national statistics, summarized on Wikipedia’s Economy of Pakistan page using official data, show exports of $40.79 billion against imports of $78.02 billion in 2025 — a nearly $37 billion gap, with petroleum imports alone totaling $15.1 billion, textiles remaining the dominant export category at $16.3 billion, and China, the UAE and the US as the country’s largest trading partners on both sides of the ledger.
Business press coverage from Business Recorder captures the tension in real time: alongside reporting on the fiscal deficit improvement and credit upgrade, the same outlet has separately reported on Pakistan’s textile mills being “caught in a contradiction they did not design” regarding their European buyers, and on the Finance Division sounding “the alarm over the persistent inflation” even as headline stabilisation indicators improve — evidence that the equity rally and the export-competitiveness challenge are running on genuinely separate tracks, both real, both simultaneously true.
Why It Matters
A market this close to record highs, riding genuine macro-improvement momentum, sends a strong signal to portfolio investors evaluating frontier and emerging markets broadly — but the persistent trade gap is the metric that ultimately determines how much of that momentum translates into durable currency stability and reduced dependence on IMF and bilateral bridge financing.
Data and Evidence
- KSE-100, August 18, 2026: 178,213 points, -1.27% daily, +18.99% YoY, +1.30% over the past month
- KSE-100 all-time high: 189,556 points
- 2025 exports: $40.79bn; 2025 imports: $78.02bn (petroleum: $15.1bn of the total)
- S&P sovereign rating: upgraded to ‘B’ from ‘B-‘ (July 22, 2026)
- FY2025-26 fiscal deficit: 2.6% of GDP, a 22-year low
Global Impact
Pakistan’s equity rally, set against a still-wide trade deficit, is a data point international frontier-market investors weigh alongside similar stabilisation-but-imbalanced stories in other IMF-program economies — a useful comparative lens for any reader tracking emerging-market risk more broadly across this batch’s coverage of Indonesia (Article 11) and other developing economies.
What Happens Next
Watch whether the KSE-100 tests its 189,556 all-time high in the coming weeks, and whether Pakistan’s upcoming trade data shows any narrowing of the export-import gap as the fiscal stabilisation narrative continues to build.
Frequently Asked Questions
Is the KSE-100 at a record high right now?
Not quite — as of August 18, 2026 it stood at 178,213, below its all-time high of 189,556, though up nearly 19% year-on-year.
What’s driving the rally?
Macro stabilisation, the S&P credit rating upgrade, a record-low fiscal deficit, and renewed foreign portfolio inflows.
Does the stock rally mean Pakistan’s economy has fully recovered?
Not entirely — the country’s structural trade deficit, with imports far exceeding exports, remains unresolved.
How big is Pakistan’s trade gap?
Roughly $37 billion in 2025, with imports of $78.02 billion against exports of $40.79 billion.
Has Pakistan’s market rallied like this before?
Yes — a similar rally in 2024 was driven by the largest foreign equity buying in a decade at that time.

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide

Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Is SPY Overvalued in September 2026? Fed Rate Hike Odds & Intrinsic Value
Intel 18A Foundry Strategy 2027: Capital Burn, Stock Sales & Break-Even Timeline
Trump Approval Hits 33% Low: What It Means for Markets & Midterms
Crypto Trading: Why AI Tools Are Changing Gen Z Investing
AI Creator Deals: How Contracts Protect Influencers
Gen Z AI Skills: Online Degrees That Boost Job Prospects
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
The New Executive Gold Standard: Top 10 Companies Lavishing Unprecedented Perks on CEOs and CFOs in 2025–2026
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
After Four Decades of Decline, Can Private Ownership Save Pakistan’s National Airline?
The World’s 50 Largest Economies: A 25-Year Growth Trajectory Analysis (2000-2025)
Resource Wealth and Geopolitical Vulnerability: Understanding Recent US Foreign Policy Toward Venezuela, Greenland, and Iran
-
Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis7 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Global Economy9 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
Asia9 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
AI9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
-
Global Economy9 months ago
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide