Markets & Finance
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Discover the top 15 Pakistan Stock Exchange stocks for 2026. Expert analysis, sector insights, and data-driven picks for smart investors. Updated January 2026.
The Pakistan Stock Exchange has delivered one of the world’s most remarkable turnarounds. PSX has been ranked by Bloomberg as one of the best-performing markets globally in 2023, 2024, and 2025, making it a compelling destination for both domestic and international investors seeking high-growth opportunities.
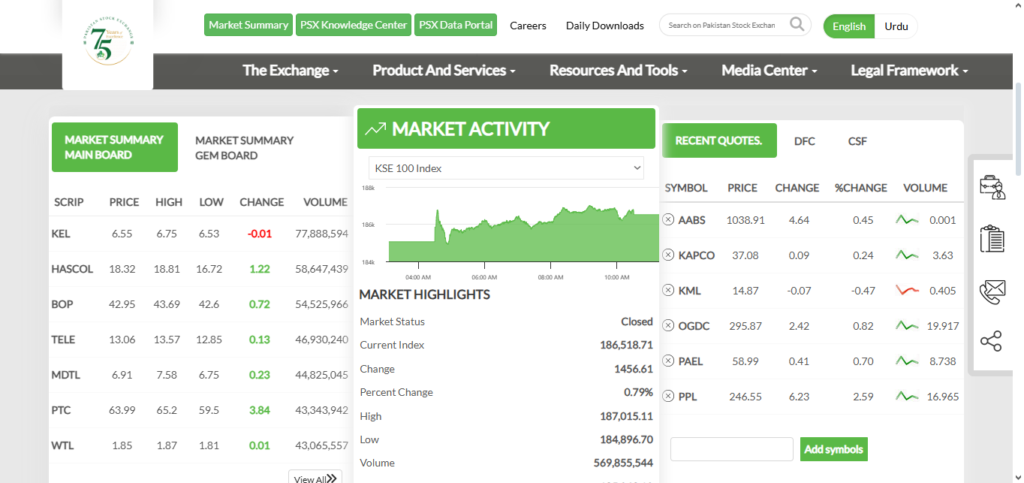
As we enter 2026, Pakistan’s economic fundamentals are stabilizing. Pakistan’s inflation rate slowed to 5.6% in December from 6.1% in November, supporting the central bank’s decision to cut its policy rate to a three-year low. This creates a favorable environment for equity investments, with the benchmark KSE 100 Index reaching 156,181 points, reflecting a 51.7% increase from the previous year.
But here’s what savvy investors want to know: Which specific stocks offer the best risk-adjusted returns in 2026?
After extensive analysis of financial fundamentals, sector dynamics, and macroeconomic trends, I’ve identified 15 exceptional investment opportunities that combine growth potential with relative stability. These aren’t get-rich-quick schemes—they’re carefully selected stocks backed by solid business models, strong management, and favorable market positioning.
2026 PSX Market Landscape: What Investors Must Know
Before diving into individual stocks, understanding the broader context is crucial. Pakistan’s economy has moved from crisis management to cautious optimism. Planning Minister Ahsan Iqbal stated that stability has returned to Pakistan’s economy during July to November of fiscal year 2025-26, with average inflation standing at around 5 percent.
Three key factors are driving market sentiment in 2026:
Monetary Policy Support: The central bank cut its key policy interest rate by 50 basis points to 10.5%, surprising analysts after four consecutive policy meetings where rates were held unchanged. Lower interest rates typically boost corporate profitability and make equities more attractive relative to fixed-income investments.
Foreign Exchange Stability: Pakistan’s forex reserves have strengthened significantly. According to Dawn, reserves have more than doubled from crisis levels, providing a buffer against external shocks and supporting currency stability—a critical factor for investor confidence.
Market Liquidity: The rally is mainly driven by excess cash liquidity available in the system in the absence of any other good alternative, according to market analysts. This liquidity is seeking productive deployment in quality equities.
However, challenges remain. Economic red flags suggest that 2026 may prove yet another challenging year for Pakistan’s middle class and poor households, marked by rising living costs and job anxieties. Smart investors must balance optimism with prudence.
Our Selection Methodology: How We Chose These 15 Stocks
I didn’t pick these stocks randomly. Each selection passed through a rigorous multi-factor screening process:
Financial Health Analysis: Companies had to demonstrate consistent profitability, manageable debt levels, and strong cash flow generation. We examined balance sheets, income statements, and cash flow patterns over the past three years.
Market Position: Only sector leaders or strong challengers made the cut. Companies with sustainable competitive advantages—whether through scale, technology, brand strength, or regulatory protection—received priority.
Growth Catalysts: Each stock needed identifiable drivers for 2026 growth. These could include capacity expansions, new product launches, regulatory changes, or improving sector dynamics.
Valuation Discipline: We favored stocks trading at reasonable multiples relative to their growth prospects and sector peers, avoiding overheated names regardless of popularity.
Risk Assessment: Every investment carries risk. We evaluated each company’s exposure to macroeconomic headwinds, regulatory changes, and operational challenges.
The result? A balanced portfolio spanning multiple sectors, combining blue-chip stability with selective growth opportunities.
Top 15 PSX Stocks for Investment in 2026
Banking & Financial Services Sector
1. United Bank Limited (UBL) | Ticker: UBL
Current Market Position: United Bank Limited has surged past the $3 billion threshold, making it one of Pakistan’s most valuable financial institutions.
Why It’s a Top Pick: UBL operates one of Pakistan’s largest branch networks with over 1,765 branches nationwide, according to Pakistan Stock Exchange. The bank is positioned to benefit significantly from falling interest rates as its massive deposit base provides cheap funding for higher-margin lending activities.
The bank’s recent performance has been stellar. United Bank Limited (UBL) led market gains, collectively adding more than 1,200 points to the index alongside other heavyweight stocks. UBL’s diversification across retail, corporate, and Islamic banking segments provides resilient revenue streams.
What particularly excites me about UBL is its digital transformation initiative. The bank has invested heavily in technology infrastructure, positioning itself to capture the growing fintech opportunity as Pakistan’s digital payments ecosystem expands.
Key Financial Metrics:
- P/E Ratio: Approximately 8.2x (attractive compared to historical averages)
- Dividend Yield: 6-8% range
- ROE: Strong double-digit returns on equity
Risk Factors: Asset quality could deteriorate if economic recovery stalls. Rising loan defaults in any sector could pressure profitability. Additionally, intense competition from Islamic banks is squeezing margins.
2026 Target Potential: 15-20% capital appreciation plus dividends
2. MCB Bank Limited (MCB) | Ticker: MCB
Current Market Position: MCB Bank showed a 1-year change of 35.09% and YTD change of 36.89%, demonstrating strong momentum.
Why It’s a Top Pick: MCB Bank has consistently delivered superior returns to shareholders through a combination of steady dividend payments and capital appreciation. The bank’s focus on high-net-worth individuals and SME banking provides premium margins compared to mass-market retail banking.
Recent market action supports bullish sentiment. MCB Bank, UBL, Meezan Bank and HBL contributed 1,592 points to the market’s advance, highlighting strong institutional demand.
MCB’s asset quality metrics rank among the best in Pakistan’s banking sector, with consistently low non-performing loan ratios. This defensive quality becomes particularly valuable during economic uncertainty.
Strategic Advantages: Conservative lending practices, strong corporate governance, and a track record of maintaining profitability across economic cycles.
Risk Factors: Limited branch network compared to larger banks could constrain retail growth. Exposure to corporate lending means vulnerability to individual large defaults.
2026 Target Potential: 12-18% appreciation opportunity
3. Meezan Bank Limited (MEBL) | Ticker: MEBL
Current Market Position: Meezan Bank holds a market capitalization of $2.10 billion, establishing itself as Pakistan’s largest Islamic bank.
Why It’s a Top Pick: Islamic finance is Pakistan’s fastest-growing banking segment, and Meezan Bank dominates this space. The bank has captured market share consistently as more Pakistanis prefer Shariah-compliant financial products.
Meezan’s growth trajectory remains impressive despite its size. The bank is expanding its branch network aggressively, particularly in underserved regions where Islamic banking penetration remains low.
Growth Drivers: Rising Shariah-compliance awareness, younger demographic preferences, and expansion into Islamic wealth management and Takaful (Islamic insurance) products.
Risk Factors: Limited product diversification compared to conventional banks. Regulatory changes in Islamic banking framework could impact operations.
2026 Target Potential: 15-22% upside
4. Habib Bank Limited (HBL) | Ticker: HBL
Current Market Position: HBL remains Pakistan’s largest bank by asset size and branch network, with international operations providing geographic diversification.
Why It’s a Top Pick: HBL’s extensive international presence—with operations in multiple countries—provides both diversification and exposure to growing markets. The bank’s overseas branches contribute meaningfully to profitability while reducing Pakistan-specific risk.
According to Investing.com, HBL offers a dividend yield of 5.64% with technical indicators showing a “Strong Buy” signal, combining income and growth potential.
Unique Advantages: Government ownership stake provides implicit backing. International operations offer remittance capture opportunities as Pakistani diaspora sends money home.
Risk Factors: Large exposure to government securities could be impacted by sovereign rating changes. International operations face geopolitical and regulatory risks.
2026 Target Potential: 10-15% with steady dividends
Energy & Oil/Gas Sector
5. Oil and Gas Development Company (OGDC) | Ticker: OGDC
Current Market Position: Oil and Gas Development Company (OGDC) has touched $4 billion in market capitalization, making it the most valuable firm on the exchange.
Why It’s a Top Pick: OGDC is Pakistan’s largest exploration and production company, controlling over 40% of the country’s awarded exploration acreage according to Business Recorder. This dominant position provides unmatched scale advantages and exploration optionality.
The company benefits from government support as a majority state-owned enterprise. Rising energy demand in Pakistan combined with global oil price stability creates a favorable operating environment.
Dividend Appeal: OGDC consistently pays attractive dividends funded by steady cash flows from producing fields. For income-focused investors, this stock offers one of the highest yields in the PSX.
Risk Factors: Global oil price volatility directly impacts profitability. Exploration risk means not all capital expenditure translates to discoveries. Government policy on gas pricing affects margins.
2026 Target Potential: 8-12% plus 6-8% dividend yield
6. Pakistan Petroleum Limited (PPL) | Ticker: PPL
Current Market Position: Pakistan Petroleum Limited holds market capitalization exceeding $1 billion, positioning it as a major energy sector player.
Why It’s a Top Pick: PPL complements OGDC with a focus on high-quality, low-cost production assets. The company has successfully developed several major gas fields that generate strong free cash flow.
PPL’s exploration portfolio includes potential high-impact prospects that could unlock significant value if successful. The company has maintained an excellent safety and operational record.
Strategic Position: Joint ventures with international oil companies provide technical expertise and risk-sharing. Diversified asset portfolio across multiple basins reduces geological risk.
Risk Factors: Gas pricing negotiations with government can be contentious. Reserve replacement is critical for long-term sustainability.
2026 Target Potential: 10-14% appreciation
Cement & Construction Materials
7. Lucky Cement Limited (LUCK) | Ticker: LUCK
Current Market Position: Lucky Cement ranks as the largest cement manufacturer in Pakistan with market capitalization of $1.83 billion.
Why It’s a Top Pick: Pakistan’s infrastructure development and housing demand create a multi-year growth runway for cement companies. Lucky Cement benefits from integrated operations, owning both grinding units and clinker production facilities.
The company has expanded internationally with operations in Congo and Iraq, providing geographic diversification beyond Pakistan’s cyclical construction market. Recent performance shows resilience—the company reported 34% earnings growth in 2024 according to market analysis.
Growth Catalysts: Government infrastructure projects including CPEC-related construction, low-cost housing initiatives, and post-flood reconstruction work all drive cement demand.
Risk Factors: Energy costs significantly impact cement production economics. Overcapacity in the sector can trigger price wars. Seasonal monsoons slow construction activity.
2026 Target Potential: 12-18% upside
8. Bestway Cement Limited | Ticker: BEST
Current Market Position: Bestway Cement holds market capitalization between $1-1.7 billion, operating as part of the diversified Bestway Group.
Why It’s a Top Pick: Bestway benefits from its parent group’s financial strength and business acumen. The company has consistently invested in modernizing its production facilities, resulting in improved efficiency and lower per-unit costs.
Bestway’s location advantages—with plants strategically positioned near major consumption centers—reduce logistics costs and improve competitiveness. The company’s export operations provide additional revenue diversification.
Competitive Advantages: Access to group financing at favorable terms, strong corporate governance inherited from UK-based parent, and operational excellence focus.
Risk Factors: Dependence on Pakistan market for majority of sales. Competition from larger players with greater economies of scale.
2026 Target Potential: 10-16% growth potential
Fertilizer Sector
9. Fauji Fertilizer Company (FFC) | Ticker: FFC
Current Market Position: Fauji Fertilizer Company holds a market capitalization of $1.96 billion and posted 140% one-year stock return, with profit growing 81%.
Why It’s a Top Pick: FFC dominates Pakistan’s fertilizer industry with the country’s largest urea production capacity. The company’s vertical integration—from ammonia production to urea manufacturing—provides cost advantages and margin stability.
Recent market action has been phenomenal. The fertilizer sector closed 2.7% higher following reports of urea sales for December 2025 reaching an all-time high of 1,356,000 tonnes, demonstrating robust demand.
Pakistan’s agricultural focus ensures sustained fertilizer demand. Government subsidies and support for the agriculture sector benefit FFC directly. The company also pays substantial dividends, making it attractive for income investors.
Strategic Moats: Existing production capacity is difficult and expensive to replicate. Government relationships provide regulatory stability. Diversification into other chemicals provides growth optionality.
Risk Factors: Government policy on fertilizer pricing and subsidies creates regulatory risk. International urea prices affect profitability. Gas supply disruptions can impact production.
2026 Target Potential: 15-20% appreciation
10. Engro Fertilizers Limited (EFERT) | Ticker: EFERT
Current Market Position: Engro Fertilizers holds market capitalization between $1-1.7 billion as part of the larger Engro Corporation conglomerate.
Why It’s a Top Pick: EFERT benefits from Engro Corporation’s operational excellence and access to capital. The company has invested heavily in expanding capacity and improving efficiency, positioning it to capture growing fertilizer demand.
Recent performance validates the investment thesis. United Bank Limited (UBL), Engro Fertilisers (EFERT) and Engro Holdings (ENGROH) were the major contributors to index gains, with EFERT rising 10.0%.
Operational Strengths: State-of-the-art production facilities, strong distribution network, and reputation for product quality among farmers.
Risk Factors: Competition from FFC and imported fertilizers. Gas supply constraints could limit production. Working capital intensity during planting seasons.
2026 Target Potential: 12-18% upside
Consumer Goods Sector
11. Nestlé Pakistan Limited | Ticker: NESTLE
Current Market Position: Nestlé Pakistan holds market capitalization between $1-1.7 billion, backed by the global Nestlé corporation.
Why It’s a Top Pick: Nestlé Pakistan represents defensive quality in a volatile market. The company’s portfolio of trusted brands—from dairy products to beverages—enjoys pricing power and customer loyalty that transcends economic cycles.
Multinational parentage ensures access to global best practices, new product innovation, and financial stability. Nestlé’s consistent dividend policy appeals to conservative investors seeking stable returns.
Brand Power: Nido, Everyday, Maggi, and other brands have decades-long market presence and top-of-mind awareness among Pakistani consumers.
Risk Factors: High valuation multiples limit upside potential. Rupee depreciation impacts imported raw material costs. Competition from local brands on price.
2026 Target Potential: 8-12% steady growth
12. Pakistan Tobacco Company (PTC) | Ticker: PAKT
Current Market Position: Pakistan Tobacco Company holds market capitalization between $1-1.7 billion.
Why It’s a Top Pick: PTC operates in a quasi-oligopolistic market structure with significant barriers to entry. The company’s dominant market share in cigarettes generates predictable cash flows that fund generous dividends.
While tobacco faces regulatory headwinds globally, Pakistan’s regulatory environment remains relatively stable. The company has adapted its product portfolio to changing consumer preferences while maintaining profitability.
Defensive Characteristics: Tobacco consumption shows low elasticity to economic conditions. Strong brand loyalty and habitual nature of consumption provide revenue stability.
Risk Factors: Increasing health awareness and taxation. Illicit trade impacts legal volumes. ESG-conscious investors may avoid the sector.
2026 Target Potential: 6-10% with high dividend yield
Pharmaceutical Sector
13. Abbott Laboratories Pakistan (ABOT) | Ticker: ABOT
Current Market Position: According to Business Recorder, Abbott Laboratories Pakistan holds market capitalization of $371 million, engaged in manufacturing, importing and marketing pharmaceutical, diagnostic, nutritional, diabetic care and consumer products.
Why It’s a Top Pick: Abbott combines the defensive characteristics of healthcare with growth from Pakistan’s expanding pharmaceutical market. Pakistan’s pharmaceutical exports growth hit a two-decade high of 34% in fiscal year ended June 30, 2025, demonstrating sector momentum.
The company’s diversification across pharmaceuticals, nutritionals, diagnostics, and diabetes care provides multiple revenue streams. Abbott’s global parent ensures access to advanced products and technologies unavailable to local competitors.
Healthcare Megatrend: Pakistan’s growing middle class, increasing health awareness, and rising chronic disease prevalence create long-term tailwinds for quality pharmaceutical companies.
Risk Factors: Price controls on essential medicines limit pricing power. Generic competition erodes margins on older products. Rupee weakness impacts imported finished goods.
2026 Target Potential: 12-16% appreciation
14. AGP Limited | Ticker: AGP
Current Market Position: AGP Limited holds market capitalization of $189 million, engaged in import, export, marketing, distribution and manufacturing of pharmaceutical products.
Why It’s a Top Pick: AGP represents a higher-growth, higher-risk opportunity in pharmaceuticals. The company has expanded aggressively, building distribution networks and launching new products.
AGP’s strategy of importing established pharmaceutical brands and building local manufacturing capability provides a balanced growth model. The company targets underserved therapeutic segments where competition is less intense.
Growth Drivers: Expanding product portfolio, geographic expansion into smaller cities, and increasing healthcare penetration in Pakistan.
Risk Factors: Smaller scale than multinational competitors. Dependence on imported products exposes to forex risk. Working capital intensity of pharmaceutical distribution.
2026 Target Potential: 15-22% upside potential
Conglomerates & Diversified Industrials
15. Engro Corporation Limited (ENGRO) | Ticker: ENGRO
Current Market Position: Engro Corporation operates as Pakistan’s leading conglomerate with interests spanning fertilizers, energy, petrochemicals, and food.
Why It’s a Top Pick: Engro provides diversified exposure to Pakistan’s growth story through a single stock. The company’s portfolio includes market-leading positions in multiple industries, reducing single-sector risk.
Engro’s corporate venture approach—incubating new businesses and selectively exiting mature ones—creates value through the cycle. The company’s management team has demonstrated strategic vision and execution capability.
Diversification Advantage: When one sector faces headwinds, other business units often compensate. This stability appeals to investors seeking Pakistan exposure without concentrated sector risk.
Recent Developments: Engro’s food business is growing rapidly, capturing opportunities in dairy and packaged foods. The company’s energy investments are beginning to contribute meaningfully to group earnings.
Risk Factors: Conglomerate discount may limit valuation multiples. Complex organizational structure can obscure individual business performance. Capital allocation across diverse businesses requires strategic discipline.
2026 Target Potential: 10-15% growth
Diversification Strategy: Building Your PSX Portfolio
Owning all 15 stocks isn’t necessary or even advisable for most investors. Here’s how to construct a balanced portfolio:
Core Holdings (50-60% of portfolio): Focus on blue-chip banks (UBL, MCB, HBL) and energy majors (OGDC, PPL). These provide stability and liquidity.
Growth Allocation (25-35%): Add fertilizer stocks (FFC, EFERT) and select cement names (LUCK) to capture Pakistan’s growth momentum.
Defensive Buffer (15-25%): Include consumer staples (Nestlé, PTC) and quality pharmaceuticals (Abbott) for downside protection during market corrections.
Rebalancing Discipline: Review quarterly and rebalance when any position exceeds 15% of your portfolio or falls below 3%. This mechanical approach prevents emotional decision-making.
Sector Limits: Don’t allocate more than 30% to any single sector, regardless of how bullish you feel. Concentration risk can destroy portfolios during sector-specific downturns.
Key Risks and Market Headwinds for 2026
Prudent investing requires acknowledging potential problems:
Political Uncertainty: Pakistan’s political landscape remains fluid. Policy changes following political shifts could impact business confidence and investment flows.
Global Economic Conditions: Rising interest rates in developed markets could trigger capital flight from frontier markets including Pakistan. Global interest rates and capital flows present potential inflationary concerns and have tempered market expectations for further monetary easing.
Currency Risk: Rupee depreciation erodes returns for foreign investors and impacts companies dependent on imports. While the exchange rate has stabilized, pressures could resurface.
Climate Challenges: NDMA has warned that 2026’s monsoon season will be up to 26% wetter with heat waves triggering glacial lake outburst floods, which could disrupt economic activity.
Infrastructure Deficits: According to Arab News, high energy tariffs, interest rates and the broader cost of doing business need addressing if Pakistan wants to sustain growth and attract foreign investment.
Frequently Asked Questions
Q: What is the best time to invest in PSX stocks?
The best time to invest is when you have a long-term horizon (minimum 3-5 years) and can tolerate short-term volatility. Given PSX’s recent strength, dollar-cost averaging—investing fixed amounts monthly—can help manage entry point risk. Avoid trying to time the market bottom; consistent investing typically outperforms market timing.
Q: How much should I invest in Pakistan Stock Exchange?
Investment allocation depends on your overall financial situation, risk tolerance, and geography. Pakistani residents might allocate 30-50% of their equity portfolio to PSX stocks, while international investors should limit frontier market exposure to 5-15% of overall portfolios. Never invest money you’ll need within three years.
Q: Are PSX stocks good for long-term investment?
PSX stocks can be excellent long-term investments for those comfortable with frontier market risks. Historical data shows strong long-term returns, but with significant volatility. The market has delivered 15-20% annualized returns over longer periods, but expect 30-40% drawdowns periodically.
Q: Which PSX sector will perform best in 2026?
Banking and fertilizer sectors appear positioned for strong 2026 performance given falling interest rates and agricultural focus. However, sector rotation is unpredictable. Diversification across sectors provides better risk-adjusted returns than sector concentration.
Q: How do I start investing in PSX as a beginner?
Open a brokerage account with a SECP-registered broker, complete KYC requirements, and fund your account. Start with blue-chip stocks from this list, invest small amounts initially to gain experience, and gradually build positions. Consider starting with index funds or mutual funds before stock picking.
Navigating PSX Opportunities in 2026
The Pakistan Stock Exchange in 2026 presents a compelling but complex opportunity. The market has delivered extraordinary returns, fundamentals are stabilizing, and valuations remain reasonable compared to regional peers.
However, this isn’t a risk-free proposition. Pakistan faces structural challenges that won’t disappear overnight. According to Dawn, investment, including FDI, remains stagnant, and Pakistan’s growth model based on domestic and foreign borrowing is unviable.
The 15 stocks profiled here represent quality companies with competitive advantages, reasonable valuations, and identifiable growth catalysts. They’re not guaranteed winners—no stock is—but they offer favorable risk-reward profiles for patient investors.
My advice? Start with positions in 5-7 stocks spanning different sectors. Invest amounts you can afford to hold through volatility. Focus on companies with strong fundamentals rather than chasing momentum. And remember that successful investing is a marathon, not a sprint.
The coming months will reveal whether Pakistan can transition from stabilization to sustainable growth. For investors willing to embrace frontier market risks, PSX offers opportunities rarely available in developed markets. Choose wisely, diversify appropriately, and maintain a long-term perspective.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All investments carry risk, including potential loss of principal. Conduct your own research and consult with qualified financial advisors before making investment decisions. Past performance does not guarantee future results.
Data Sources: Pakistan Stock Exchange, Bloomberg, Business Recorder, Dawn, State Bank of Pakistan, Trading Economics
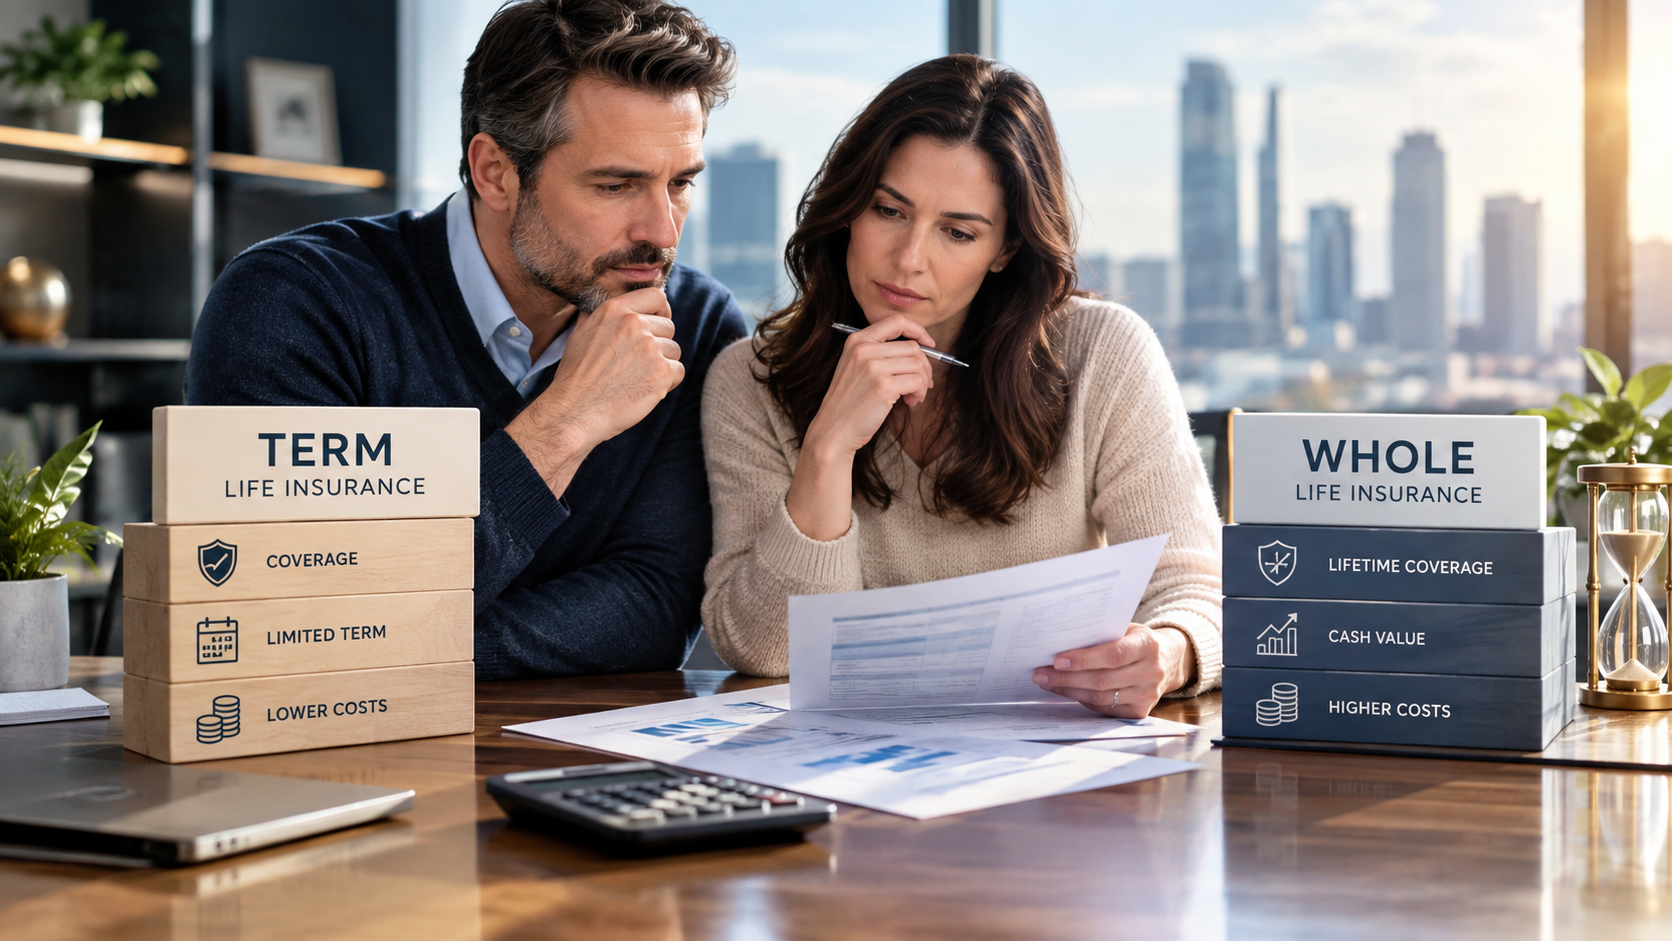
A 40-year-old buying $500,000 in term life coverage pays roughly $26 a month — the same coverage as a whole life policy can cost over $200 a month for the identical death benefit, a gap most first-time shoppers never see clearly explained before they buy.
Life insurance comparison shopping isn’t just about finding the cheapest insurer — it’s about understanding which fundamentally different type of policy actually fits your financial situation, since term and permanent life insurance solve very different problems at dramatically different price points. Getting this choice wrong is one of the most expensive and hardest-to-reverse mistakes in personal finance.
This guide breaks down how term and whole life insurance actually compare, current 2026 rate benchmarks by age and policy type, and how to choose between them.
How Term and Whole Life Insurance Actually Compare
The fundamental distinction is duration and structure: term life covers you for a fixed period with no cash value, while whole life covers you permanently and builds a cash value component — and that structural difference explains nearly the entire price gap between them.
Key takeaway: A 40-year-old man in good health who doesn’t smoke may pay less than $20 per month for a 20-year, $250,000 term life policy, but $216 per month for a whole life policy with the same coverage amount — meaning the permanent policy costs roughly 10 times more for identical death benefit coverage.
Term Life Insurance: What It Is and Isn’t
- Covers a fixed period — commonly 10, 20, or 30 years — and pays a death benefit only if you die during that term.
- Builds no cash value — the policy simply expires if you outlive the term, with no residual value.
- Significantly cheaper — because most term policies never pay out, premiums stay low relative to the coverage amount.
- Best suited to temporary needs — replacing income during child-rearing years, covering a mortgage term, or protecting a co-signed debt.
Whole Life Insurance: What It Is and Isn’t
- Covers your entire lifetime, as long as premiums are paid, with a guaranteed death benefit.
- Builds cash value over time, which grows tax-deferred and can be borrowed against or withdrawn.
- Premiums are fixed for life and, unlike term policies, never increase once the policy is issued.
- Best suited to permanent needs — estate planning, funding a lifetime dependent’s care, or as a component of a broader wealth-transfer strategy.
Step-by-Step: How to Compare Life Insurance Quotes
- Determine how long you actually need coverage — a temporary need (mortgage, income replacement until kids are grown) points toward term; a permanent need points toward whole or universal life.
- Decide on a coverage amount based on income replacement needs, outstanding debts, and dependents’ future expenses.
- Get quotes for the same coverage amount and term length across at least three insurers, since pricing varies meaningfully by carrier even for identical applicant profiles.
- Compare riders and policy features — child riders, disability waivers, and conversion options can meaningfully affect long-term value.
- Review the insurer’s financial strength rating, since a life insurance promise is only as good as the company’s ability to pay decades from now.
- Complete the underwriting process honestly — medical exams and health disclosures directly determine your final rate, and misrepresentation can void a claim later.
Financial and Strategic Implications: 2026 Rate Benchmarks by Age
Rates rise substantially with age for both policy types, making early purchase one of the most effective ways to minimize lifetime insurance costs.
| Age | Term Life (Men, Annual) | Term Life (Women, Annual) | Whole Life (Men, Annual) | Whole Life (Women, Annual) |
|---|---|---|---|---|
| 20 | $749 | $554 | $2,548 | $2,260 |
| 30 | $795 | $645 | $3,662 | $3,292 |
| 40 | $1,482 | $1,175 | $5,524 | $4,967 |
| 50 | $3,495 | $2,560 | $8,749 | $7,782 |
| 60 | $8,435 | $6,002 | $14,517 | $12,670 |
Rates based on a $500,000 policy for preferred nonsmoker applicants in good health; NerdWallet 2026 data.
Expert insight: Whole life premiums typically increase by 8% to 10% for every additional year of age at the time of application, meaning the cost of waiting even a few years to purchase permanent coverage compounds meaningfully — a strong argument for locking in a policy earlier rather than later if permanent coverage genuinely fits your needs.
Factors That Legally Cannot Affect Your Rate
Insurers cannot base your life insurance rate on ethnicity, race, or sexual orientation, and generally do not use credit score as a rating factor the way auto and home insurers do — rates are instead driven primarily by age, gender, health status, tobacco use, and the coverage amount and term length selected.
How to Choose Between Term and Whole Life Insurance
- Match the policy to the actual financial need, not to the policy that feels the most “permanent” or reassuring — a temporary income-replacement need is almost always better served by lower-cost term coverage.
- Consider term conversion options — many term policies allow conversion to permanent coverage later without new medical underwriting, offering flexibility without paying whole life premiums upfront.
- Don’t conflate life insurance with investment strategy — while whole life builds cash value, the returns are typically modest compared to dedicated investment vehicles, meaning “insurance as an investment” pitches deserve careful independent scrutiny.
- Buy coverage while young and healthy — since both term and whole life rates increase substantially with age, delaying a purchase you already know you need has a real, compounding cost.
- Compare quotes from multiple insurers for the same coverage, since rate variation between carriers for identical applicant profiles can be substantial.
- Add a term rider to a whole life policy, rather than buying an all-whole-life solution, as a way to secure higher total coverage during high-need years (young children, a large mortgage) without paying permanent-policy rates on the full amount.
Key takeaway: The most common and costly life insurance mistake isn’t choosing the wrong company — it’s buying a policy type that doesn’t match the actual duration of the financial need, paying permanent-policy premiums for what is really a temporary coverage requirement, or vice versa.
Future Outlook: Life Insurance Trends Through 2027
- Digital underwriting continues to compress application timelines. More insurers now offer accelerated underwriting using health data and prescription history instead of a traditional medical exam for qualifying applicants, meaningfully speeding up the quote-to-policy timeline for healthy applicants.
- Term insurance affordability remains historically favorable. Term rates have stayed relatively stable in recent years, keeping the cost gap between term and permanent coverage wide and reinforcing term’s role as the default choice for most temporary coverage needs.
- Hybrid life-and-long-term-care products are gaining attention. As long-term care costs continue rising, more insurers are marketing permanent life policies with long-term care riders, an area worth independent comparison against standalone long-term care insurance.
- Life insurance adoption gaps persist as an ongoing industry concern. Despite historically low term insurance costs relative to coverage amount, a significant share of households remain underinsured or uninsured, keeping consumer education a continued focus for insurers and regulators alike.
Frequently Asked Questions
What’s the main difference between term and whole life insurance? Term life covers you for a fixed period with no cash value and lower premiums; whole life covers you permanently, builds cash value, and costs substantially more for the same death benefit.
Which is cheaper, term or whole life insurance?
Term life is significantly cheaper — a 40-year-old might pay under $20 a month for term coverage versus over $200 a month for a whole life policy with the same death benefit.
Does my credit score affect my life insurance rate?
Generally no. Unlike auto or home insurance, life insurers typically do not use credit score as a rating factor; rates are driven mainly by age, gender, health, and tobacco use.
Can I convert a term life policy to whole life later?
Many term policies include a conversion option allowing you to switch to permanent coverage later without new medical underwriting, though this should be confirmed at the time of purchase since not all policies include it.
How much does life insurance typically cost per month?
Costs vary widely by age, health, and policy type, but a healthy 40-year-old might pay roughly $26 a month for a standard 20-year, $500,000 term policy, according to industry averages.
Economy & Markets
Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

While the broader market struggled to find a definitive direction on September 23, 2026, the tech-heavy Nasdaq Composite secured another record close. Investors continue to exhibit a voracious appetite for artificial intelligence (AI) and semiconductor stocks, viewing them as long-term structural winners despite underlying macroeconomic crosscurrents.
Meanwhile, the Dow Jones Industrial Average and the S&P 500 failed to catch the tech sector’s tailwind, pressured by sliding oil prices and a rotation out of traditional blue-chip sectors.
Key Market Takeaways
- Nasdaq Extends AI-Fueled Rally: The index surged to a fresh record closing high, fueled by continued momentum in high-performance chipmakers and mega-cap tech stocks.
- Dow Jones & S&P 500 Lag: The Dow shed over 185 points, while the S&P 500 ended flat as investors rotated out of industrial and energy names.
- Oil Prices Slip Below $100: Global crude benchmarks pulled back sharply following productive U.S.-Iran diplomatic discussions at the United Nations.
- Bond Yields Stabilize: The 10-year Treasury yield cooled slightly, slipping back under the critical 5% threshold, offering relief to rate-sensitive equities.
Major Index Performance (September 23, 2026)
| Index | Closing Price | Point Change | Percentage Change |
| Nasdaq Composite | 27,244.28 | +121.15 | +0.45% |
| S&P 500 | 7,764.27 | -0.43 | -0.01% |
| Dow Jones Industrial Average | 51,863.69 | -185.14 | -0.36% |
Tech Leads the Charge While the Dow Drifts
The divergence between high-growth technology and cyclical sectors was the defining narrative of the session. According to market data analyzed by Zacks Investment Research, the Information Technology Select Sector SPDR (XLK) rose 0.7%, masking broader weaknesses in the market.
Semiconductor companies carried the bulk of the index’s weight. High-performance power chipmaker Monolithic Power Systems (MPWR) jumped over 8%, while industry stalwarts like Micron, Nvidia, and Advanced Micro Devices (AMD) all contributed to the upward momentum.
Conversely, the Dow Jones Industrial Average dropped 0.36%, weighed down by lagging industrial stocks and banking financials like JPMorgan Chase and Wells Fargo. The S&P 500 finished effectively flat, reflecting an aggressive tug-of-war between soaring tech valuations and struggling traditional sectors.
Crude Oil Slides Amidst U.S.-Iran Diplomatic Progress
Energy markets commanded outsized attention as both Brent and West Texas Intermediate (WTI) crude experienced notable declines. Brent crude slipped back below the psychological $100-per-barrel mark, settling near $98.68, while WTI fell toward $89.64.
The primary catalyst for the selloff was a geopolitical de-escalation signal. As reported by BNN Bloomberg, diplomatic progress during “very good” meetings between U.S. and Iranian officials at the UN General Assembly helped soothe global energy supply anxieties. This geopolitical cooling temporarily offset supply-side fears stemming from a recent armed blockade at Libya’s El Sharara oil field.
Treasury Yields Cool, Easing Pressure on Equities
Bond markets provided a much-needed tailwind for growth stocks, acting as a counterbalance to the broader economic uncertainty. The benchmark 10-year U.S. Treasury yield touched an intraday high of 4.98% on hawkish Federal Reserve commentary before retreating back to hover near 4.94% by the close.
Falling oil prices naturally provide relief from the inflation and interest rate concerns that have dominated September trading, as highlighted by TheStreet. Stable borrowing costs help keep mortgage rates and corporate debt manageable, granting investors the confidence to bid up valuations in long-duration tech assets.
What to Watch Next
As Wall Street digests Wednesday’s split-market action, institutional focus is pivoting toward critical upcoming macroeconomic and corporate events:
- U.S.-China Summit: A highly anticipated meeting in Washington, D.C., later this week could yield progress on a trade truce and potentially spark new bilateral frameworks for global AI regulation.
- Corporate Earnings: Paychex (PAYX) and Cintas (CTAS) will provide fresh insights into small-business payroll trends and broad corporate hiring, giving investors a real-time read on the health of the U.S. labor market. Retail bellwether Costco Wholesale (COST) is also slated to report on Thursday, which will serve as a barometer for big-ticket consumer demand.
Economy & Markets
Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation
Gasoline rose 3.9% in August and drove over a third of the CPI increase. Inside the crude-to-pump-to-CPI chain and what it means for the next Fed decision.There is a clean, traceable chain running from a Saudi pipeline to a Bureau of Labor Statistics table, and August 2026 is the cleanest illustration of it in years.
Executive Summary / Key Takeaways
- The August 2026 CPI, released 11 September, showed the all-items index up 0.4% on the month and 3.4% over twelve months.
- The gasoline index rose 3.9% in August, accounting for over one third of the entire monthly all-items increase. Energy overall rose 2.1% after falling 1.5% in July.
- Year-on-year, gasoline was up 27.4% and fuel oil up 52%, while energy as a whole rose 16.3%.
- Core CPI, excluding food and energy, rose 0.3% on the month but slowed to 2.4% annually — the lowest reading since March 2021.
- The divergence is the signal: headline inflation is being generated almost entirely by energy while underlying price pressure cools. That is the precise configuration that makes a supply-shock tightening cycle contentious.
The Consumer Price Index rose 0.4% month-on-month in August, meeting consensus, and held at 3.4% on a twelve-month basis, per TD Economics. Energy costs rose 2.1% monthly, led by a 3.9% gain in gasoline. Food rose a subdued 0.1% for a second consecutive month and is up 2.7% over the year. Excluding food and energy, core prices rose 0.3% monthly — a tick hotter than expectations — while the twelve-month core rate edged down to 2.4%, with the three-month annualised at a softer 2.0%.
The BLS itself flagged the concentration: the gasoline index accounted for over one third of the monthly all-items increase.
2. Core Analysis: The Transmission Chain
2.1 August CPI in detail
| Component | Monthly change | Annual change | Note |
|---|---|---|---|
| All items | +0.4% | +3.4% | Strongest monthly rise in three months |
| Core (ex food & energy) | +0.3% | +2.4% | Lowest annual reading since March 2021 |
| Gasoline | +3.9% | +27.4% | Over one-third of the monthly headline increase |
| Energy (all) | +2.1% | +16.3% | After -1.5% in July |
| Fuel oil | +10.1% | +52.0% | Sharpest annual move in the report |
| Electricity | -0.2% | +3.8% | Declined monthly |
| Natural gas | -1.1% | — | Declined monthly |
| Shelter | +0.3% | +3.0% | Eased from 3.2% |
| Food | +0.1% | +2.7% | Eased from 3.0% |
| Airline fares | +2.7% | — | Fuel pass-through visible |
Data compiled from the BLS release, Trading Economics and Fox Business reporting.
2.2 Crude to pump to CPI
The chain has three links and a measurable lag at each.
Crude to pump. Crude is the largest single cost in a gallon of gasoline, and pump prices generally track WTI and Brent with a one-to-two week lag. WTI has traded near $103 and Brent near $107, following Houthi attacks that shut a crucial Saudi crude pipeline bypassing the Strait of Hormuz.
Pump to CPI. The BLS surveys consumer prices up to the previous month, so the August report published on 11 September reflects August pump prices — which averaged well below the $4.329 recorded on 15 September, per AAA data. Real-time retail fuel readings therefore lead the gasoline index by roughly four to six weeks.
CPI to policy. The August report showed inflation remaining elevated on rising energy prices, which Vanguard senior economist Josh Hirt said made a September rate hike more likely, per Fox Business. The Fed hiked on 16 September.
That is the full loop, and it took roughly six weeks from pipeline to policy decision.
2.3 Why headline and core diverged
Core inflation falling to 2.4% — its lowest since March 2021 — while headline holds at 3.4% is the most consequential detail in the release, and most coverage buried it.
Core below headline means energy is the primary driver and underlying price pressures are cooling. Shelter, the largest single CPI component, rose a comparatively modest 0.3% monthly and 3.0% annually, elevated historically but not accelerating the way energy is, per analysis of the release. Used vehicle prices are essentially flat year-on-year at +0.4% and new vehicles up only 0.6%, meaning that outside gasoline, transportation is not an inflation driver at all.
Headline is also well off its peak. The 3.4% annual rate is down from the April 2026 peak of 4.2%.
3. Structural Drivers and Competitor Gaps
Retail fuel telemetry as a leading indicator. Because CPI surveys lag by a month and publishes with a further delay, real-time pump-price data is genuinely predictive of the gasoline index — the single most volatile and most headline-relevant CPI component. With national averages running above $4.30 in mid-September against August levels, the September CPI due 14 October carries upside risk on the energy line before any other factor is considered.
The second-round question. Because energy costs feed into shipping, manufacturing and agriculture, economists watch a spike like this for early signs it will appear in core figures in following months. August’s evidence is mixed: core services rose 0.3% monthly on a sharp acceleration in non-housing services (+0.6%), which is where energy pass-through would first appear, even as annual core fell. Airline fares up 2.7% monthly is the cleanest visible pass-through in the report.
The policy disagreement this creates. Treasury Secretary Scott Bessent argued that the Fed typically does not raise rates during a supply shock until second- or third-order inflationary effects appear. The August data is genuinely ambiguous on whether those effects have arrived — annual core at a five-year low argues no; non-housing services acceleration argues possibly. Both sides of the September policy debate could cite this release honestly.
What households actually experience. Gasoline and fuel oil increases hit budgets immediately and visibly at every fill-up, rather than in a monthly bill. A 27.4% annual gasoline increase compounding already-elevated shelter costs means many households are absorbing higher costs on two of their largest monthly expenses at once — which is why consumer inflation expectations track headline rather than core, and why the Fed cannot simply look through energy.
Where the forecasts failed. GasBuddy’s pre-conflict outlook projected a 2026 national average of $2.97 a gallon. The actual reading is $4.329. Any inflation model built in late 2025 embedded an energy assumption that missed by roughly $1.35 a gallon, which is most of the gap between forecast and realised headline CPI this year.
4. Key Implications for Stakeholders
Economists and forecasters. Model headline and core separately and weight retail fuel telemetry into the near-term headline path. The September CPI on 14 October is the key test of whether August’s gasoline spike is sustained or reversed.
Inflation trackers. The 3.4% headline is not a signal of broad-based inflation. Strip energy and the picture is a 2.4% core running at a 2.0% three-month annualised pace — close to target. The economy has an energy problem, not a generalised inflation problem.
Retail traders. Watch Saudi East-West pipeline restoration. The kingdom indicated it could restore around half of capacity within days and full operations within six weeks. A confirmed restoration would remove the dominant CPI driver within one to two print cycles.
Households and budgeters. The gap between headline and core explains why official inflation feels understated: energy and shelter, the two most visible household costs, are both running above the core rate.
5. Frequently Asked Questions
Q1: What was the August 2026 inflation rate?
The CPI rose 0.4% month-on-month and 3.4% over twelve months, unchanged from July and down from the April 2026 peak of 4.2%. Core CPI rose 0.3% monthly and 2.4% annually.
Q2: How much did gasoline contribute to inflation?
The gasoline index rose 3.9% in August, accounting for over one third of the entire monthly all-items increase, and is up 27.4% year-on-year. Energy overall rose 2.1% monthly and 16.3% annually.
Q3: Why is core inflation lower than headline inflation?
Because energy is driving the headline figure while underlying pressures cool. Core CPI, which excludes food and energy, fell to 2.4% annually — the lowest since March 2021 — with shelter easing to 3.0% and vehicle prices essentially flat.
Q4: When is the next CPI report?
The September 2026 CPI is scheduled for release on Wednesday, 14 October 2026 at 8:30 a.m. ET. It will show whether the August gasoline spike was sustained.

US Impeachment Talk and White House Press Secretary Changes: What the Record Shows

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide

Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
AI Impact on Wages 2026: Productivity Soars, Paychecks Stagnate
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Analysis4 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
-
Global Economy10 months ago
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pingback: Top 5 Stock Picks on the Pakistan Stock Exchange for 2026: Expert Analysis and Investment Outlook - The Economy
Pingback: Top 5 Stock Picks on the Pakistan Stock Exchange for 2026: Expert Analysis and Investment Outlook - The Economy