AI
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

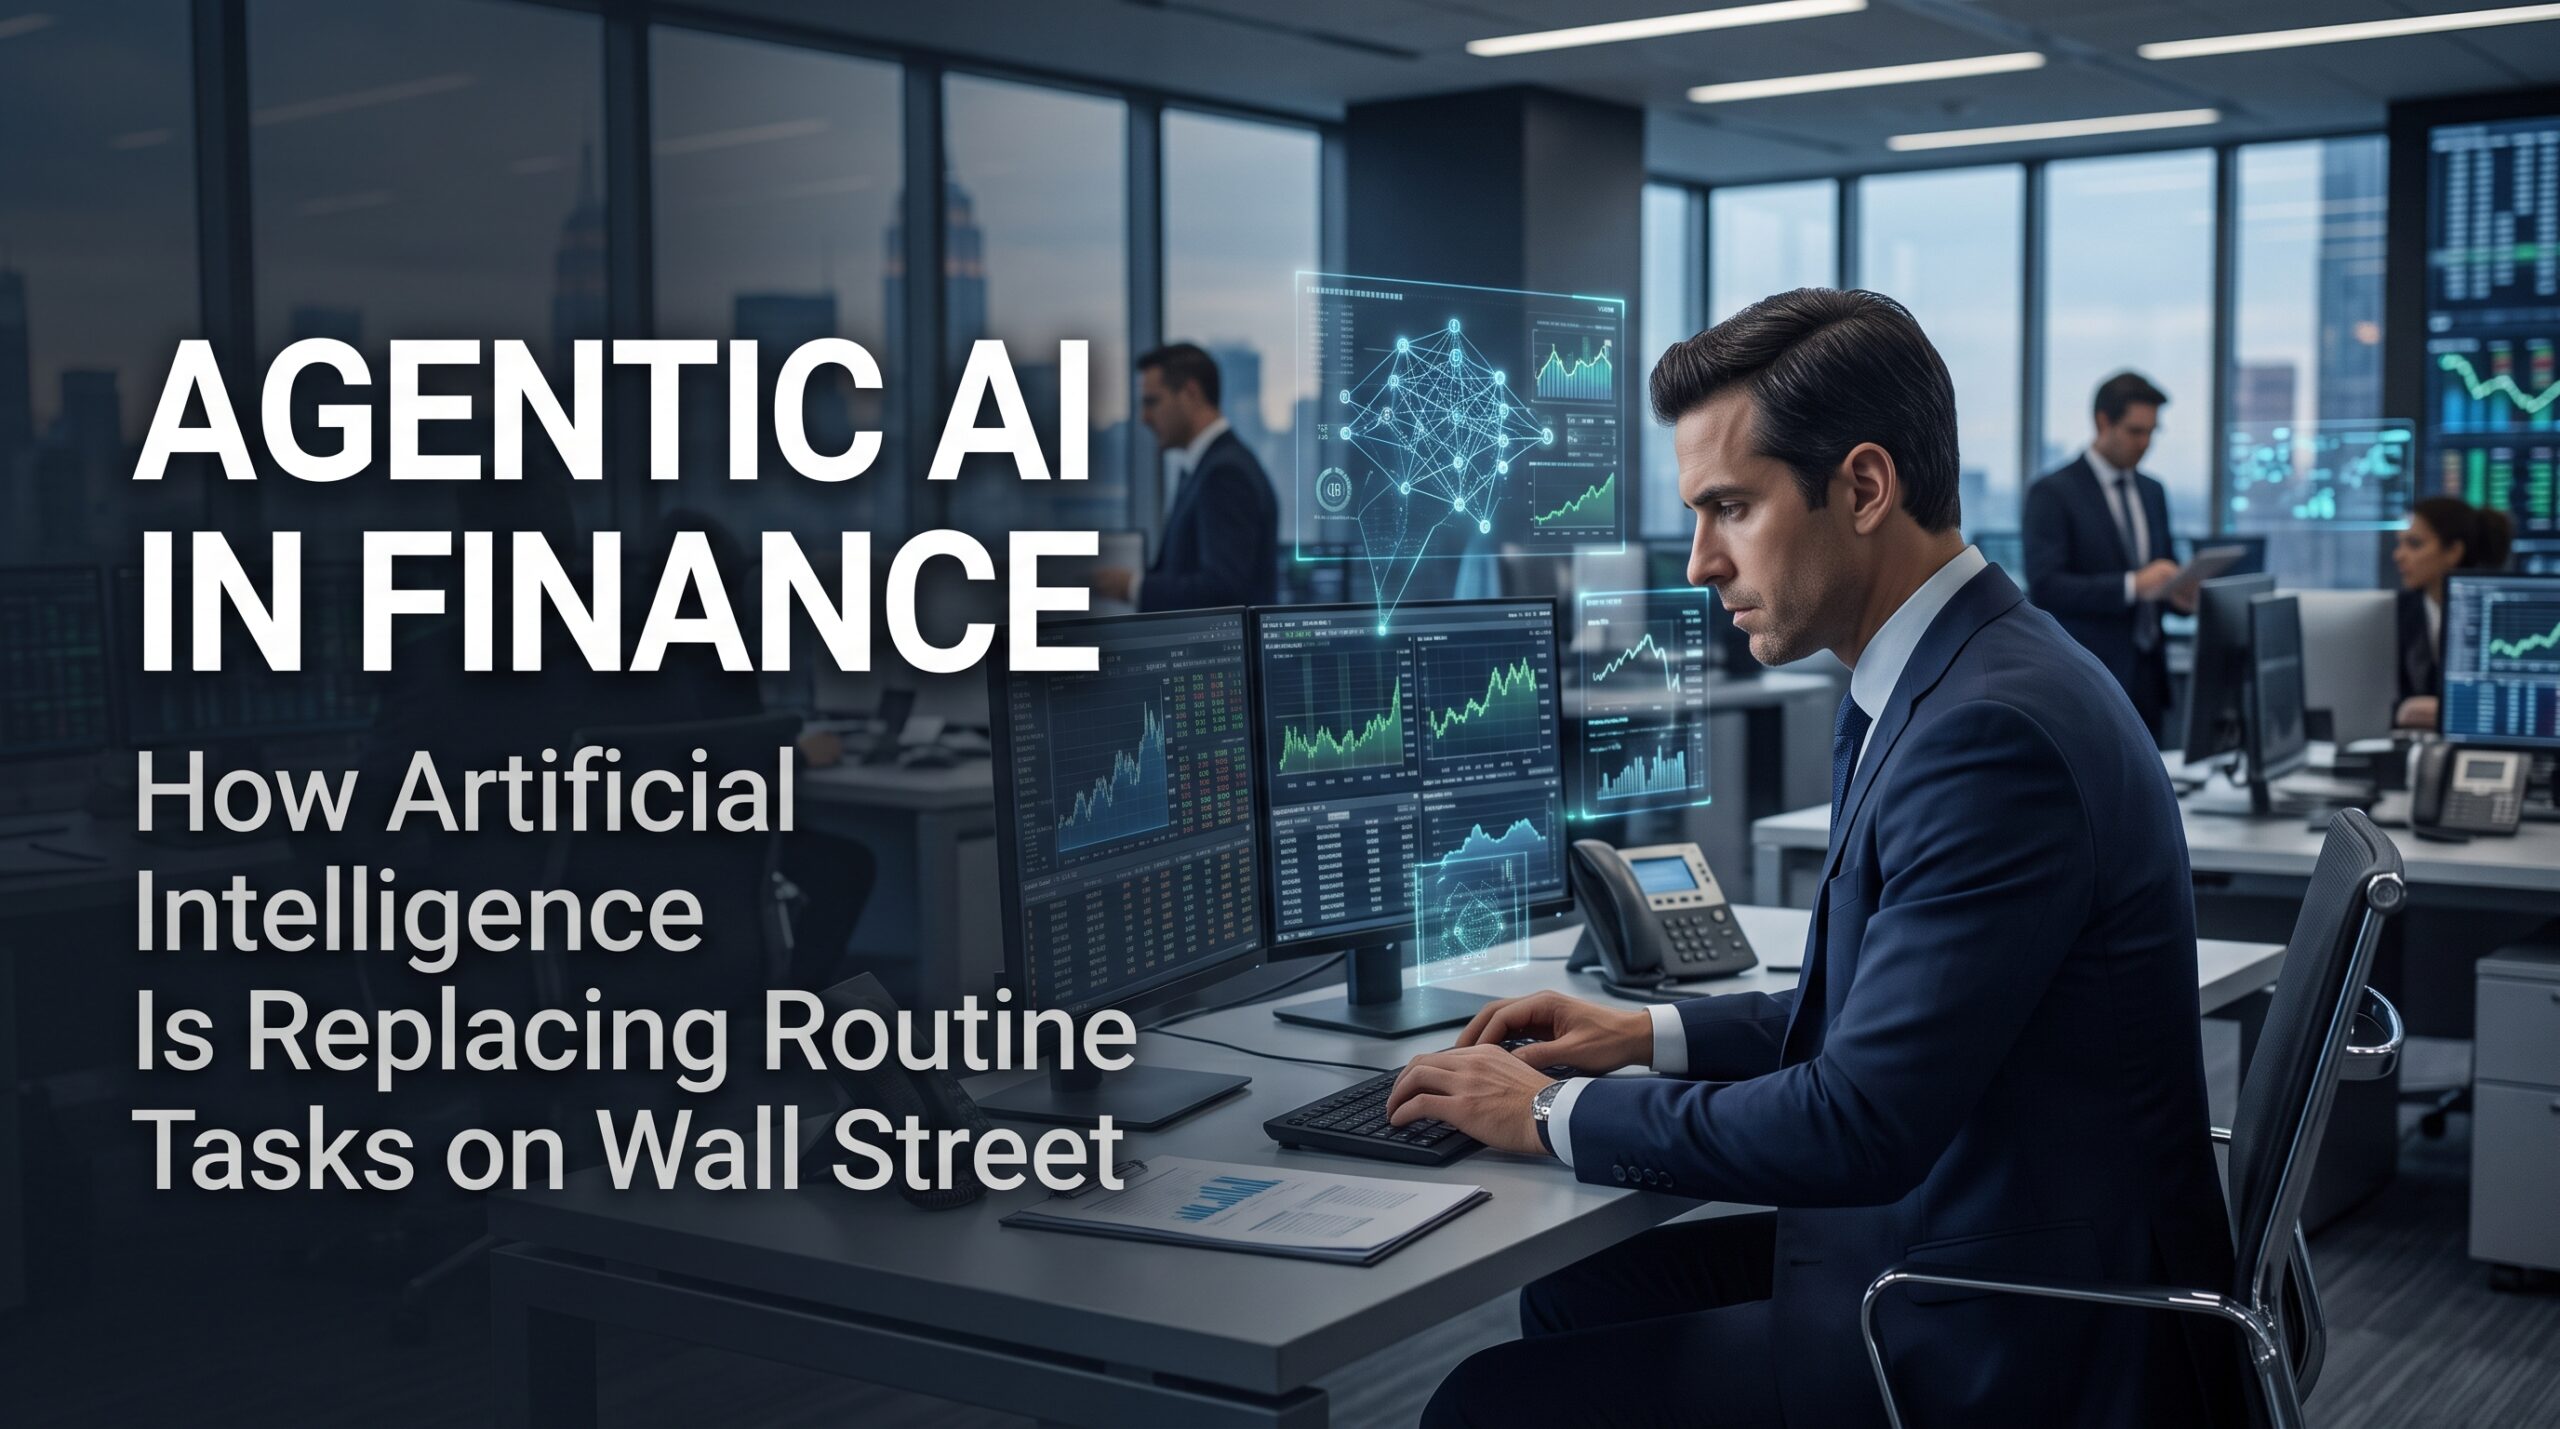
The euphemisms ended in early 2026. For years, Wall Street CEOs talked around the question of whether AI would shrink their workforces. In the first quarter of 2026, the six largest U.S. banks posted a combined $47 billion in profit — up 18% year-over-year — while cutting 15,000 jobs, and this time their chief executives said the quiet part out loud. This is the story of how agentic AI moved from pilot project to production system across the financial industry, and what it’s actually doing to headcount, cost structure, and the traditional career pipeline into banking.
From Assistive Tools to Autonomous Agents
The distinction matters. For the past several years, “AI in finance” meant chatbots answering balance inquiries, machine learning models scoring credit risk marginally faster, and robotic process automation pushing documents through predictable, rules-based workflows — assistive tools that helped humans work faster but still required a human to initiate and oversee each step. According to NeuralCoreTech’s 2026 analysis, agentic AI represents a structural shift: systems that plan, reason, and execute multi-step workflows with minimal human initiation, already deployed at scale by institutions including JPMorgan and Goldman Sachs across fraud detection, compliance, and operations.
Accenture’s Top Banking Trends for 2026 report, published in January, forecast that AI model advances and maturing enterprise deployment tools would let banks “take greater advantage of agentic AI” throughout the year, with adoption growing beyond early pilots into broader production use, according to Banking Dive. The same report found nearly half of banks and insurers were creating dedicated roles specifically to supervise AI agents — a new job category that didn’t meaningfully exist two years earlier.
The Q1 2026 Inflection Point: Banks Stop Hedging
The clearest evidence that agentic AI has moved from theory to balance-sheet reality came in Q1 2026 earnings season. The six largest U.S. banks — JPMorgan Chase, Citigroup, Bank of America, Wells Fargo, Goldman Sachs, and Morgan Stanley — shed a combined 15,000 jobs while posting $47 billion in collective profit, according to reporting from The Next Web. Crucially, executives stopped hedging on the cause. JPMorgan CEO Jamie Dimon said plainly that AI “will eliminate jobs” and that people should “stop sticking their heads in the sand.” Wells Fargo CEO Charlie Scharf went further, saying anyone claiming AI won’t reduce headcount “either does not know what they are talking about or is not being totally honest.”
JPMorgan’s disclosed AI productivity metrics (Q1 2026):
| Metric | Figure |
|---|---|
| 2026 technology spending | $19.8 billion (+$2B YoY) |
| Productivity gain in AI-using divisions | ~6% (double pre-deployment rate) |
| Operations roles trimmed | -4% |
| Support function roles trimmed | -2% |
| Client-engagement/revenue roles | +4% |
That last line is the part most coverage misses: JPMorgan isn’t simply shrinking — it’s reallocating. Dimon described the shift as “a huge redeployment” rather than a pure contraction, with headcount losses concentrated in operations and support functions while revenue-generating and client-facing roles actually grew.
The Junior Analyst Problem
The most consequential — and most structurally risky — shift has hit the traditional entry point into investment banking. Goldman Sachs, JPMorgan, Citigroup, and Barclays are reportedly cutting junior analyst cohorts, with reductions reaching as much as two-thirds at some institutions, according to reporting cited by TechJack Solutions. Standard Chartered has reportedly targeted 7,800 role eliminations by 2030.
The structural paradox here is significant. Junior analyst classes have historically been the primary talent pipeline for the quantitative roles, data science positions, and internal AI development teams banks now depend on to build and maintain the very automation replacing those same analysts. As TechJack Solutions frames it: “cutting them creates a capability deficit the automation itself can’t fill” — the engineers who build and customize agentic AI systems have to come from somewhere, and banks may be eliminating their own future talent pipeline in pursuit of near-term efficiency.
Employment lawyer David Parsons of Mishcon de Reya told Bloomberg that this wave of automation reaches further up the org chart than prior waves: “It’s fair to say middle office is vulnerable,” according to HR Chief Magazine’s coverage. Parsons also flagged a legal risk executives are reportedly underpricing: cutting large numbers of junior or administrative staff — roles often disproportionately held by women — carries “huge discrimination risks.”
Not every bank is retreating from entry-level hiring, however. Bank of America has committed to 2,000 summer interns and another 2,000 full-time recruits even while holding overall headcount flat and leaning on AI for efficiency gains elsewhere, per the same report — suggesting a meaningful strategic split within the industry on how aggressively to cut the traditional pipeline.
The Economics: Real, But Concentrated
The macro numbers on agentic AI’s financial impact are large but should be read carefully. According to PwC data cited by Neurons Lab, finance teams using agentic AI extensively are spending more time generating insights and less time on automatable tasks, delivering nearly 25% in cost savings. McKinsey’s broader banking-industry estimate suggests AI could reduce certain cost categories by as much as 70%, though the net industry-wide effect — after accounting for rising AI technology costs themselves — is closer to 15%–20%, or $700–800 billion globally. IDC separately reports organizations achieve an average 2.3x return on agentic AI investment within 13 months.
The caveat NeuralCoreTech’s research emphasizes is important: “AI ROI is real but concentrated, condition-dependent, and often misrepresented by those with commercial interests in broad adoption narratives.” Adoption itself remains uneven — McKinsey’s late-2025 data found adoption highest in risk, legal, and compliance functions, with more than half of institutions still piloting rather than actively deploying agentic AI as of that survey, according to Statista.
Governance: The Open Problem
Agentic AI’s autonomy is also its biggest unresolved risk. Systems making consequential decisions in credit, fraud, and compliance must produce auditable reasoning traces, but multi-step LLM-based reasoning is inherently harder to explain than older rule-based models, according to NeuralCoreTech. The EU AI Act classifies both credit scoring and fraud detection AI as “high-risk,” requiring specific documentation, oversight, and human review — a regulatory bar that U.S. and UK banking regulators are separately reinforcing through formal model risk governance requirements, including independent validation and ongoing performance monitoring. Most bank CIOs reportedly expect their AI agents to operate under a centralized governance model rather than being deployed department-by-department without oversight.
The Wider Context: A Multi-Year Trend, Not a Single Event
It’s worth situating 2026’s cuts against the broader trend line. Bloomberg reported that Wall Street’s six largest firms eliminated a combined 10,600 jobs in 2025 alone — the steepest annual reduction since 2016 — bringing combined headcount across the group to 1.09 million, the lowest since 2021. A Challenger data brief published in June 2026 found that AI-attributed job cuts across all sectors in 2026 had already exceeded the entire 2025 total, according to TechJack Solutions — underscoring that this is an accelerating, not stabilizing, trend.
Final Verdict
Agentic AI’s impact on Wall Street in 2026 is best understood as reallocation with a real net contraction at the entry level, not wholesale job elimination across the board. Operations and middle-office roles are shrinking measurably, junior analyst classes are being cut by as much as two-thirds at some firms, and executives have stopped pretending otherwise — but revenue-generating and client-facing headcount is simultaneously growing at firms like JPMorgan, and the economic gains, while genuinely substantial in specific functions, remain concentrated rather than uniform across the industry. The unresolved question hanging over the entire trend is structural: if banks hollow out the junior talent pipeline that has historically produced their AI engineers, quants, and future senior bankers, the efficiency gains booked in 2026 may come with a talent-development bill due later in the decade.
Key Takeaways
- Chip stocks tumbled Monday, September 14, 2026, after the CEOs of Anthropic, OpenAI, and xAI publicly aligned behind a call to slow the pace of frontier AI capability development — an unusual moment of unity among fierce industry rivals.
- Nvidia fell 3.4% and the Philadelphia Semiconductor Index (PHLX) sank almost 6%, its worst single day since early July, even as the broader Nasdaq Composite closed down a more modest 0.56%.
- The catalyst was an essay from Anthropic CEO Dario Amodei, titled “We Must Pace the Frontier,” proposing independent outside evaluators be given internal access to frontier AI labs, alongside industry-wide cooperation and government coordination.
- OpenAI CEO Sam Altman confirmed in a Fortune interview that OpenAI will not pursue an IPO in 2026, calling the current safety environment an “ill-advised moment” to go public — pushing one of the most anticipated listings in tech history to 2027 at the earliest.
- The episode followed the resignation of a researcher who had worked at both Anthropic and OpenAI, who warned publicly that people building the technology “earnestly believe it could kill us all by the end of the decade” — a post that drew over 150 million views and prompted more than 20 lawmakers to call for tougher AI regulation.
A rare display of unity among Silicon Valley’s most competitive AI labs sent a jolt through markets this week, as semiconductor stocks logged their worst day in over two months following public calls from the industry’s top executives to deliberately slow the development of increasingly powerful AI systems.
What Triggered the Selloff
The catalyst was an essay published Saturday, September 12, by Anthropic CEO Dario Amodei, titled “We Must Pace the Frontier.” In it, Amodei argued that unchecked acceleration in frontier AI development — driven in part by the risk of recursive self-improvement, where AI systems increasingly assist in designing their own successors — is outpacing the industry’s ability to keep those systems aligned and secure. Amodei wrote that he believes AI could still “dramatically raise the quality of human life,” but argued the risks accompanying its current pace of development need to be taken seriously, proposing that even a modest slowdown of a year or two could meaningfully improve safety outcomes.
What made the essay market-moving wasn’t just its content, but who endorsed it. OpenAI CEO Sam Altman and SpaceX/xAI’s Elon Musk — two executives whose companies compete directly with Anthropic and with each other — both publicly backed Amodei’s proposal within a day. Musk wrote simply on X that “Dario is right,” a notable shift given Musk’s history of sharp public criticism of Anthropic.
The Proposal’s Substance
Amodei’s plan outlined a three-phase approach: independent safety evaluators embedded within frontier AI companies with access equivalent to internal staff (covering training processes, internal systems, and safety-protocol compliance); broader industry-wide cooperation on shared safety standards; and coordination with democratic governments on global regulatory frameworks. Anthropic said it would adopt the outside-evaluator step immediately, while Altman confirmed OpenAI would adopt comparable third-party evaluator access.
The Resignation That Set the Stage
The unity among AI executives followed a more unsettling precursor: a researcher who had previously worked at both Anthropic and OpenAI resigned the prior week, writing publicly that people building the technology “earnestly believe that it could kill us all by the end of the decade.” The post reportedly drew more than 150 million views on X and prompted more than 20 lawmakers to call for tougher AI regulation — context that appears to have accelerated the executives’ public alignment on pacing concerns.
Market Reaction: Chips Hit Hardest
Monday’s trading session showed a clear divergence in how different corners of the AI-linked market absorbed the news. Semiconductor stocks bore the brunt of the selling, given their direct exposure to the capital-expenditure cycle that rapid AI capability development has fueled. Nvidia fell 3.4%, Intel dropped 5.6%, and the Philadelphia Semiconductor Index tumbled nearly 6% — its steepest one-day decline since early July.
By contrast, shares of some larger Big Tech and software companies actually climbed on the day, leaving the broader, tech-heavy Nasdaq Composite down a comparatively modest 0.56%, after having fallen as much as 1.3% intraday before paring losses. The divergence suggests markets are interpreting a potential AI development slowdown as a more direct threat to chip demand specifically — the hardware layer most tied to the “faster, bigger” capability race — than to software and platform companies with more diversified revenue.
OpenAI’s IPO Delay: The Clearest Business Signal
Beyond the one-day stock move, the most concrete business consequence to emerge from the episode was Sam Altman’s confirmation that OpenAI will not go public in 2026. In a Fortune interview published the same weekend, Altman said an IPO “right now would be an ill-advised moment” given the current safety environment, and when asked whether 2027 was more realistic, replied simply, “I would say not 2026.” That timeline represents a real shift: OpenAI CFO Sarah Friar had told employees just a month earlier that the company would likely go public in 2027, or potentially sooner if the business continued to “inflect.”
Notably, Anthropic’s own IPO preparations are reportedly continuing on a separate track. According to reporting on the matter, Anthropic — confidentially valued at $965 billion earlier in 2026 — has continued meeting with prospective investors and could begin marketing its IPO as early as October, aiming to complete the listing before the November midterm elections, even as its CEO simultaneously champions industry-wide deceleration. Observers have noted the apparent tension in pursuing an IPO while publicly urging pacing, though Amodei’s essay explicitly framed pacing as slowing capability development, not halting commercial or fundraising activity.
Market Snapshot: September 14, 2026
| Index / Stock | Move | Note |
|---|---|---|
| Philadelphia Semiconductor Index (SOX) | -5.9% | Worst day since early July |
| Nvidia (NVDA) | -3.4% | Direct AI-chip exposure |
| Intel (INTC) | -5.6% | |
| Nasdaq 100 | -0.8% | |
| Nasdaq Composite | -0.56% | Software names partially offset chip losses |
| S&P 500 | -0.5% |
Why This Matters for Technology News and Investors
This episode marks one of the first times investor sentiment around AI has moved meaningfully on a safety-driven narrative rather than a purely commercial one — competitive product launches, earnings beats, or compute-capacity announcements. For investors tracking technology news, the key signal to watch going forward is whether this represents a genuine, sustained industry pivot toward deliberate pacing (which could structurally slow the capital-expenditure supercycle currently powering semiconductor demand), or a rhetorical moment that fades once competitive pressure between OpenAI, Anthropic, xAI, and other labs reasserts itself — a tension the OpenAI-Anthropic IPO-timing contrast already illustrates.
Frequently Asked Questions
Why did semiconductor stocks fall after the AI slowdown announcement? Chip stocks are directly tied to the capital-expenditure cycle fueling rapid AI capability development, so markets interpreted a potential industry-wide pacing effort as a more direct threat to near-term chip demand than to software or platform companies.
Is OpenAI still planning to go public? Yes, but not in 2026. CEO Sam Altman confirmed OpenAI is delaying its IPO to 2027 at the earliest, citing the current AI safety environment, while OpenAI’s CFO had previously suggested 2027 was the likely target regardless.
What did Anthropic’s CEO actually propose? Dario Amodei’s essay proposed embedding independent outside safety evaluators within frontier AI companies with internal-level access, alongside broader industry cooperation on safety standards and coordination with democratic governments on regulatory frameworks — explicitly framed as pacing capability development, not halting it.
Enterprise generative AI in 2026 presents a genuine paradox: adoption is nearly universal, individual productivity gains are well-documented and real, and yet the majority of organizations still cannot point to measurable enterprise-wide financial return. Understanding that gap — not simply citing adoption statistics — is now the central strategic question for any organization evaluating its AI investment.
The Adoption-to-Impact Gap, By the Numbers
| Metric | 2026 Data | Source |
|---|---|---|
| Organizations using AI in at least one business function | 88–90% | McKinsey / Stanford AI Index |
| Organizations reporting generative AI use specifically | 70–72% | Stanford AI Index / Menlo Ventures |
| CEOs reporting “nothing” or zero measurable ROI | 56% | PwC January 2026 CEO Survey (n=4,454) |
| Organizations seeing significant ROI from generative AI | 29% | 2026 enterprise adoption survey |
| AI projects moving to production achieving positive ROI within 12 months | 44% | Forrester |
| Organizations that have scaled AI beyond pilot stage | ~33% | Multiple 2026 surveys |
| Enterprise generative AI spending growth, 2024→2025 | +222%, reaching $37 billion | Menlo Ventures |
Axis Intelligence Research’s AI Productivity Gap Index (APGI) scores the 2026 landscape at 68.4 out of 100, placing enterprise AI firmly in “Large Gap” territory — worse than the documented adoption-to-impact gaps observed during the 2011–2014 cloud computing adoption cycle or the 2013–2016 enterprise social media adoption cycle. This is a genuinely useful historical anchor: it suggests the current gap between AI deployment and AI value capture, while frustrating to executives, is not unprecedented for a fast-diffusing enterprise technology — but it is currently worse than the two most recent comparable technology cycles.
Why Individual Gains Aren’t Converting to P&L Impact
The productivity gains at the individual level are genuinely substantial and well-measured:
- Active Microsoft 365 Copilot users save 14 to 26 minutes per day, per Microsoft’s own early-user research and a UK government trial respectively.
- Active OpenAI Enterprise users save 40 to 60 minutes per day, according to Goldman Sachs’ reporting of OpenAI usage data from December 2025.
- Individual productivity gains from generative AI tools reach 5x in documented cases, per 2026 enterprise adoption survey data.
- Accenture estimates the average productivity value of generative AI tools at $7,800 per employee per year for knowledge workers.
The conversion failure happens at the aggregation layer. ModelOp’s 2026 survey of 100 senior AI enterprise leaders found that two-thirds of AI-spending organizations rely on estimates of time saved rather than measured financial outcomes to assess ROI — meaning most organizations cannot actually trace individual time savings through to a documented P&L line, even when the underlying time savings are real. PwC’s April 2026 AI Performance Study identifies what separates the top-performing 20% of organizations: they pursue growth (new products, market expansion) alongside efficiency, rather than treating AI purely as a cost-reduction lever — a strategic distinction that appears to be the single strongest predictor of realized enterprise value.
What’s Actually Driving the Failure Modes
Across the 2026 survey literature, five recurring root causes explain why individual productivity gains fail to scale into enterprise transformation:
- Isolated tactical implementation rather than enterprise-wide deployment — pockets of AI usage within specific teams that never integrate into core workflows or systems of record.
- Insufficient data quality and infrastructure — Gartner projects that 60% of AI projects unsupported by AI-ready data will be abandoned through 2026, reinforcing that the primary blocker is data readiness, not model capability.
- Misalignment between AI initiatives and business strategy — AI deployed because it’s available, not because it’s mapped to a specific, measurable business outcome.
- Inadequate change management — 54% of C-suite executives admit adopting AI is “tearing their company apart” internally, reflecting genuine organizational friction rather than pure technology limitation.
- Lack of clear measurement frameworks — the two-thirds of organizations relying on estimated rather than measured outcomes noted above is both a symptom and a cause of this failure mode.
Return-on-Investment Benchmarks Where They Exist
Despite the aggregate gap, credible ROI benchmarks do exist for organizations that have moved past pilot stage:
- McKinsey Global AI Survey: 5.8x average ROI on AI investment within 14 months of production deployment.
- IDC/Microsoft: 3.7x average return per $1 invested in generative AI.
- Forrester Total Economic Impact studies: cite cases of 333% ROI with a six-month payback period for organizations using enterprise-grade platforms with structured deployment.
- Google Cloud’s ROI of AI research: 74% of executives whose organizations use generative AI report ROI within the first year, rising to 88% among agentic-AI early adopters specifically — suggesting agentic (task-executing) AI deployments may be converting to measured ROI faster than general-purpose generative AI usage.
- KPMG’s Q1 2026 AI Quarterly Pulse Survey: 62% of U.S. organizations have achieved measurable ROI or expect it within the next 12 months.
The dispersion across these figures (3.7x to 5.8x average ROI, but also 56% of CEOs reporting zero ROI) is itself the key finding: ROI in enterprise AI is currently bimodal, not normally distributed — organizations either are capturing substantial, measured returns through structured deployment, or are capturing effectively none, with comparatively few landing in a modest-middle-ground outcome.
The Security Governance Dimension: Shadow AI
Parallel to the ROI question, 2026 has been the year enterprise AI security risk moved from theoretical to quantified and regulatory:
- IBM’s Cost of a Data Breach Report 2026 (published July 29, 2026, studying 602 breached organizations across 17 industries and 16 countries) found shadow AI — unauthorized, unapproved AI tool usage — involved in 43% of security incidents, up sharply from roughly one in five the prior year.
- Shadow AI increases average breach costs by $670,000 per incident and adds roughly 10 days to breach identification and containment timelines, per IBM’s data.
- Visibility remains the core governance failure: only 25% of organizations report comprehensive visibility into how employees actually use AI tools, while 35% describe shadow AI usage as pervasive or widespread within their organization.
- Only 37% of organizations have formal AI governance policies in place — meaning 63% are currently operating without documented guardrails, per IBM 2025 data cited across multiple 2026 governance reports.
Regulatory Timeline: The EU AI Act Compliance Clock
Governance is no longer purely a voluntary best-practice question. Under the EU AI Act implementation timeline, most remaining provisions began applying August 2, 2026, with member states now required to maintain at least one national AI regulatory sandbox. A further compliance milestone follows August 2, 2027, when Article 6(1) obligations and legacy general-purpose model compliance requirements take effect. For any organization processing EU data or serving EU customers, ungoverned AI use is now a documented regulatory exposure, not solely a security concern.
Governance Frameworks Auditors Increasingly Expect
Three frameworks have emerged as the reference points defining “reasonable care” in enterprise AI governance:
- NIST AI Risk Management Framework, structured around four functions: Govern, Map, Measure, and Manage.
- ISO/IEC 42001, the certifiable AI management system standard (published December 2023, now increasingly referenced in enterprise audits).
- NIST Cybersecurity Framework 2.0, which added a dedicated Govern function mapping directly onto AI-specific oversight requirements.
What Separates High-ROI Organizations from the 56% Reporting Nothing
Synthesizing across the 2026 research base, the organizations capturing measured, enterprise-wide ROI share a consistent pattern:
- They pursue growth use cases alongside efficiency, not efficiency alone (PwC’s top-performing-20% finding).
- They deploy approved AI tools with real-time coaching rather than blanket bans, which one healthcare-system case study found reduced unauthorized shadow AI usage by 89% while still capturing productivity gains — demonstrating that governance and productivity are not inherently in tension when implemented well.
- They measure financial outcomes directly rather than relying on estimated time-savings as a ROI proxy.
- They treat AI governance as infrastructure, not paperwork — Gartner projects AI governance spending will reach $492 million in 2026 and surpass $1 billion by 2030, reflecting genuine budget commitment rather than compliance-theater spending among leading organizations.
Bottom Line
Enterprise generative AI in 2026 has achieved near-universal adoption and well-documented individual productivity gains — but the majority of organizations still cannot convert those gains into measured, enterprise-wide financial return, with 56% of CEOs reporting zero measurable ROI even as documented benchmarks show 3.7x to 5.8x returns are achievable. The differentiator is not the technology itself but organizational execution: structured deployment paired with genuine financial measurement, growth-oriented rather than purely cost-focused use cases, and governance frameworks robust enough to manage the shadow AI risk now implicated in 43% of security incidents — all under an EU AI Act compliance clock that started running in August 2026.

The New Risk Frontier of Digital Exports
As software, AI models, digital media, and cross-border SaaS platforms dominate global trade, traditional commercial property and casualty insurance is no longer sufficient. Digital exporters face complex liabilities ranging from cross-border data privacy breaches and algorithmic bias claims to intellectual property infringement in foreign jurisdictions. In 2026, protecting a borderless digital enterprise requires specialized insurance coverage tailored to intangible asset risks.
Failing to secure robust digital export insurance can expose founders and shareholders to catastrophic lawsuits originating from overseas regulatory bodies.
Essential Coverages for Digital Export Enterprises
Cyber Liability and Algorithmic Error Coverage
If an AI model or software product exported overseas malfunctions or suffers a data breach, foreign regulators can levy severe fines under regional privacy laws. Modern cyber policies cover both regulatory defense costs and third-party damages.
Intellectual Property and Copyright Defense
Digital creators and SaaS firms operating globally are frequent targets of frivolous IP litigation in unfamiliar legal systems. Specialized IP insurance covers the exorbitant legal fees required to defend international patents and copyrights.
| Insurance Policy Type | Primary Protection Area | Target Enterprise | Average Annual Premium |
| Global Cyber Liability | Data breaches, ransomware, AI output errors | SaaS & AI Platforms | $5,000 – $18,000 |
| E&O Professional Liability | Service failures, missed deliverables | Digital Consultancies & Agencies | $3,000 – $10,000 |
| International IP Defense | Foreign copyright & patent lawsuits | Software Developers & Creators | $7,000 – $25,000 |
Securing Comprehensive Coverage: Best Practices
Navigating the insurance market for digital exports requires partnering with specialized brokers who understand intangible asset exposures.
Audit Geographic Exposures: Clearly map where your digital users reside to ensure your policy covers those specific regulatory jurisdictions.
Verify AI Exclusion Clauses: Carefully review policy wording to ensure your generative AI or automated tools are not explicitly excluded from coverage.
Maintain Incident Response Protocols: Insurers offer lower premiums to firms that demonstrate rigorous cybersecurity and data governance standards.
“Risk Management Expert Note: Your software may be intangible, but your liability in foreign markets is entirely real. Comprehensive digital export insurance is the ultimate shield for borderless growth.”
Equipping your digital export enterprise with specialized insurance safeguards your balance sheet and ensures uninterrupted global expansion.

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide

Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Is SPY Overvalued in September 2026? Fed Rate Hike Odds & Intrinsic Value
Intel 18A Foundry Strategy 2027: Capital Burn, Stock Sales & Break-Even Timeline
Trump Approval Hits 33% Low: What It Means for Markets & Midterms
Crypto Trading: Why AI Tools Are Changing Gen Z Investing
AI Creator Deals: How Contracts Protect Influencers
Gen Z AI Skills: Online Degrees That Boost Job Prospects
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
The New Executive Gold Standard: Top 10 Companies Lavishing Unprecedented Perks on CEOs and CFOs in 2025–2026
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
After Four Decades of Decline, Can Private Ownership Save Pakistan’s National Airline?
The World’s 50 Largest Economies: A 25-Year Growth Trajectory Analysis (2000-2025)
Resource Wealth and Geopolitical Vulnerability: Understanding Recent US Foreign Policy Toward Venezuela, Greenland, and Iran
-
Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis7 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Global Economy9 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
Asia9 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
AI9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
-
Global Economy9 months ago
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide