Opinion
How Fertiliser Prices Affect Food Prices and Affordability

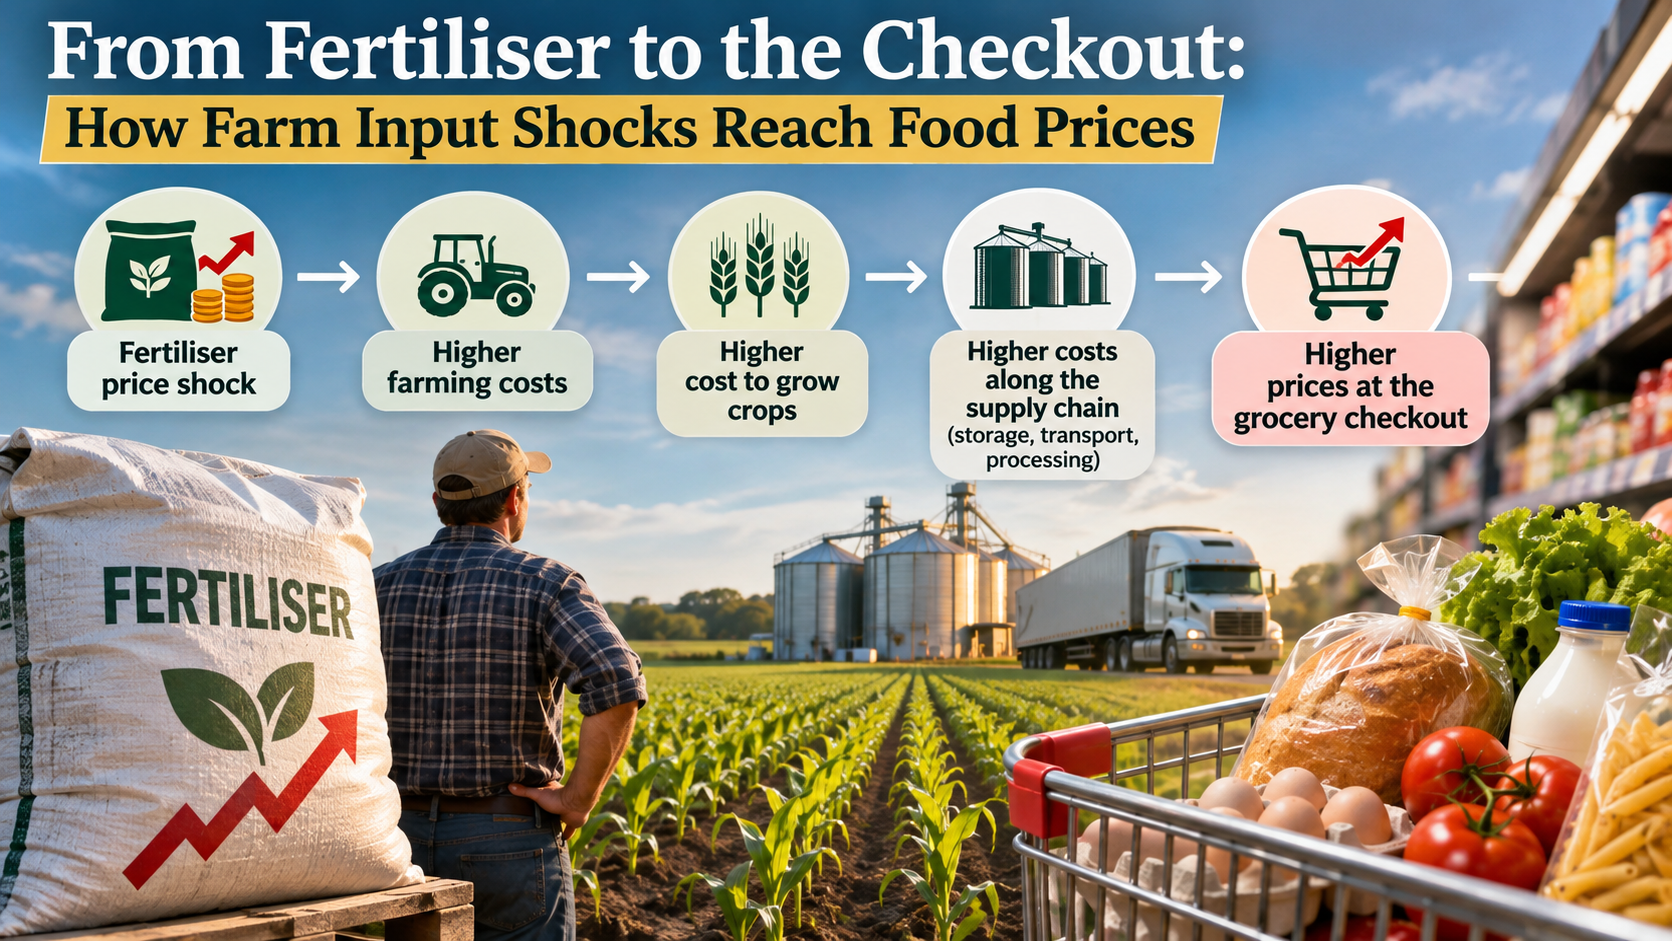
In brief: Fertiliser price increases affect food affordability through farmers’ input bills, planting choices, yields and future supply. The impact differs by crop, subsidy policy and planting calendar; it may be much slower than the effect of rising diesel on road transport. This guide draws on the World Bank’s October 2026 commodity outlook and identifies where an individual case needs additional checks.
The context
Published commodity indexes describe wholesale market movements; exchange rates, transport and the contents of a national food basket determine how households feel those movements.
Information relevant to why fertiliser price shocks affect grocery prices can be misread when a national guideline, an industry average and a reader’s particular situation are presented as though they are identical. The starting point is the dated evidence. The FAO Food Price Index, November 2026 release provides wider context, while the specific details below explain the limits of a simple answer.
How it works
Fertiliser is partly linked to natural gas costs and international shipping. When its price rises, growers may pay more per hectare or cut application, potentially changing output quality and yields. Food processors and distributors then add their own logistics, labour and retail costs before the effect reaches consumers.
This creates a useful distinction between a headline measure and the outcome that matters. The former can be quoted publicly; the latter may depend on timing, eligibility, contract terms, geography or equipment. A careful analysis names each moving part instead of pretending the same rule produces an identical result for everyone.
A worked example
Consider two farms that face the same fertiliser price rise: one buys stock before planting and absorbs higher costs immediately; the other has already purchased supplies and may not feel the change until the following season. Neither case can be reduced to an instant retail inflation percentage.
The example isolates a particular assumption rather than claiming to reproduce every real-world case. Change the date, price, document category or other relevant input, and the conclusion may change. Readers should use the calculation or scenario as a transparent method for asking better questions, not as a substitute for primary records.
What to check in practice
Track nutrient costs by crop, seasonal planting deadlines, local subsidy delivery and grain import reliance. Distinguish fertiliser price forecasts from realised retail food price changes; the two datasets measure different points in a long chain.
| Evidence | Where to look | What it establishes |
|---|---|---|
| Governing principle | World Bank October 2026 commodity outlook | The baseline rule or measured relationship |
| Broader context | FAO Food Price Index, November 2026 release | The date and wider background |
| Your individual position | Domestic prices, contracts and country-level official statistics | Whether the general explanation applies in practice |
A source can be authoritative and still be too broad to settle an individual case. When multiple documents or measurements disagree, check whether they refer to different periods, populations, definitions or activities before deciding that one must be wrong.
Where a simple answer becomes misleading
It is misleading to say fertiliser prices mechanically cause supermarket prices to rise at the same rate. Weather, crop disease, trade restrictions and global demand can dominate in some years, and the response may arrive after the current season’s harvest.
These qualifications are not minor technicalities. They are often the difference between a useful guide and a confident headline that sends the reader in the wrong direction. The safest recommendation is to describe the relevant condition precisely and then give readers a way to verify it themselves.
What the available evidence does and does not establish
The World Bank’s late-October 2026 outlook describes a different fertiliser forecast from its earlier April release, a useful example of why dated scenarios matter. Compare successive forecasts rather than citing a superseded figure as current.
The FAO Food Price Index methodology helps corroborate the wider subject, but it cannot authenticate a reader’s private documents, bills, contractual obligations or travel plan. Where the article includes an illustrative calculation, the assumptions are labelled. Where it concerns a live rule or future schedule, the controlling institution should be consulted again immediately before use.
For an independent news report on the October 2026 commodity outlook, see Reuters: World Bank October 2026 commodity outlook. This news account adds context; it is not a substitute for the directly applicable institutional source.
A short verification checklist
- Start with the specific evidence: Track nutrient costs by crop, seasonal planting deadlines, local subsidy delivery and grain import reliance.
- Challenge the default assumption: It is misleading to say fertiliser prices mechanically cause supermarket prices to rise at the same rate.
- Check the scope of the published material: The World Bank’s late-October 2026 outlook describes a different fertiliser forecast from its earlier April release, a useful example of why dated scenarios matter.
- Confirm the current version: Revisit the World Bank October 2026 commodity outlook and the original dated guidance before making an irreversible decision.
Frequently asked questions
What is the key principle?
Fertiliser price increases affect food affordability through farmers’ input bills, planting choices, yields and future supply. The relevant primary reference is World Bank October 2026 commodity outlook.
What would change the answer?
It is misleading to say fertiliser prices mechanically cause supermarket prices to rise at the same rate. Weather, crop disease, trade restrictions and global demand can dominate in some years, and the response may arrive after the current season’s harvest.
What should I verify before relying on this?
Track nutrient costs by crop, seasonal planting deadlines, local subsidy delivery and grain import reliance. Distinguish fertiliser price forecasts from realised retail food price changes; the two datasets measure different points in a long chain.
Fertiliser price increases affect food affordability through farmers’ input bills, planting choices, yields and future supply. The World Bank’s late-October 2026 outlook describes a different fertiliser forecast from its earlier April release, a useful example of why dated scenarios matter.
Online interest in impeachment and White House staffing has risen in a political environment where a few words can badly distort the underlying story. A resolution was introduced is not the same as the House voted to impeach. A press secretary was removed is not the same as the administration changed policy. Both require evidence, dates and clear procedural language.
Two verifiable developments frame the discussion as of October 25, 2026. A House impeachment resolution was tabled on September 15, and the short tenure of White House press secretary Katie Zacharia ended in mid-October, according to official congressional records and major US reporting. Neither event should be inflated into an unverified claim about new votes or a new administration decision.
The impeachment resolution: what the House actually voted on
House Resolution 1486 concerned impeachment of President Donald Trump. The US House’s official floor summary records the September 15 vote on a motion to table the measure: 232–147, with 47 members recorded as present. A successful tabling motion sets aside a measure; it is not the adoption of articles of impeachment.
This distinction is essential. A social post describing that roll call as a vote to impeach reverses the outcome. A later claim about a different resolution should be separately checked against the official Congress website and House roll-call records rather than treated as an update to an old headline without evidence.
Congressional procedure is sometimes inconvenient for trending-content production. It is also what protects the reader from misinformation. The reporter’s task is to identify the motion, the chamber, the date and the disposition before attempting broader political interpretation.
What happened to the press secretary?
CBS News reported on October 16 that Zacharia was removed from the White House press-secretary role after roughly five days. CBS cited US officials and reported scrutiny of her credentials and performance. It also noted that the White House had not yet announced a successor in that report.
A leadership change in the briefing room can be significant for how an administration communicates with journalists and the public. But personnel turnover alone does not establish a change to economic policy, foreign strategy or legal proceedings. Those substantive conclusions require separate evidence.
Why the two stories became combustible
Impeachment is a constitutionally consequential process and a powerful political symbol. White House press briefings are the main arena where officials defend decisions under questioning. When both topics circulate at once, online narratives may stitch them into a supposed constitutional crisis—even if there is no documented direct connection.
A measured account must resist that temptation. Political opponents may view impeachment proposals as necessary oversight; supporters of the president may describe them as partisan exercises. The purpose of reporting is not to resolve those disagreements by advocacy, but to distinguish political argument from verifiable institutional action.
The fact-checker’s four-part test
| Question | Evidence needed |
|---|---|
| Was an impeachment measure introduced? | Official resolution number and introduction date |
| Did the House approve articles? | Recorded vote on adopting the relevant articles |
| Was an official removed? | Direct statement or multiple reliable attributed reports |
| Who now holds the position? | Current White House announcement, not an old biography |
This is particularly important during a midterm-election year. Campaigns and commentators have incentives to present ordinary procedural setbacks as existential victories or defeats. Readers benefit from precise language instead of ever-louder adjectives.
What should international readers take from it?
For audiences in Pakistan and elsewhere in Asia, US political turmoil matters when it alters policy certainty: trade measures, sanctions, diplomacy, defence arrangements, fiscal decisions and monetary-policy appointments. None should be projected automatically from a press secretary’s dismissal or a resolution that did not pass.
It is sensible to monitor official notices, court actions and enacted policy. It is not sensible to treat search-volume spikes as proof of truth. Search trends measure curiosity, fear and newsworthiness; they do not independently confirm the event people are typing about.
Why parliamentary verbs matter
US political coverage frequently compresses filed, referred, tabled, passed and enacted into the generic word approved. Those actions are not interchangeable. A resolution can be introduced without advancing beyond committee. A motion to table is a vote about whether the chamber will proceed, not a judgment approving the underlying allegations. A measure passed by one chamber may still require further constitutional steps.
The same precision is necessary in personnel news. A spokesperson’s announced departure, a media report citing officials and a formal appointment are different evidence levels. Where the administration has not issued a replacement notice, describing a favourite online rumour as the current officeholder is poor reporting.
Public debate about impeachment also should not be reduced to the number of search queries. Search interest can be increased by critics, supporters, confused readers or social platforms circulating an old clip. It gives no reliable denominator for public opinion. A survey with a known sample and methodology is a different kind of evidence.
The best follow-up coverage would monitor official House actions and White House releases, then connect any actual policy changes to their legal basis. That approach serves readers across the political spectrum without manufacturing a crisis.
Has the September 15 House vote impeached Trump?
No. The recorded action was a successful motion to table the resolution, not a vote approving impeachment articles.
Was Katie Zacharia removed?
Yes, CBS reported her departure from the role on October 16. Any later staffing changes should be checked directly before publication.
Do impeachment trends reveal who will win the midterms?
No. Search spikes are not representative polling or an election forecast.
The standard worth keeping: precise institutional language is not timid journalism. It is the difference between telling readers what happened and telling them what a viral headline wants them to believe.

Global economic growth in 2026 is growing increasingly uneven, capital is becoming far more sensitive to financing costs, and discerning a compelling narrative from an investable asset price is crucial. Rather than promising guaranteed returns, this guide outlines essential research methods and key market risks. While the IMF’s October 2026 outlook projects global growth at 3.1% and inflation at 4.7%, its financial-stability report cautions that underlying vulnerabilities persist beneath current market resilience.
Key takeaways
- Match each investment decision to its time horizon, currency and ability to withstand losses.
- Separate observable earnings or contractual cash flows from optimistic forecasts.
- Compare diversification, fees, taxes, liquidity and regulatory restrictions before committing capital.
- Track primary institutional evidence and update assumptions when conditions change.
- Readers in Pakistan should consider rupee exposure and availability of regulated investment channels.
Why this matters now
The central question behind global recession risk 2026 is not merely what may happen next. It is which economic mechanisms could change cash flow, purchasing power or risk. The Bank for International Settlements’ 2026 review describes an economy supported by technological investment but constrained by geopolitical and fiscal pressures. A robust financial plan must therefore survive both a favourable and an adverse scenario.
Start with the baseline, not the frightening headline
The IMF forecast 3.1% global growth in 2026 and 3.4% in 2027, implying continued expansion under its baseline rather than an outright worldwide recession. Nevertheless, forecasts can miss shocks. Investors should monitor a basket of labour, credit, trade, earnings and inflation indicators rather than treating any single signal as destiny. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Yield curves and interest-rate expectations
An inverted yield curve can reflect expectations of weaker activity or future interest-rate cuts, but term premiums and central-bank balance sheets complicate interpretation. A subsequent steepening may accompany either improving growth expectations or falling short-term rates during a downturn. Context matters more than a mechanical threshold. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Credit spreads and lending conditions
Widening differences between risky and safe bond yields can reveal anxiety about defaults and funding. Banks tightening lending standards may reduce business investment and household spending. Monitor multiple jurisdictions: financial stress in one country need not translate into a worldwide contraction, but global funding networks can spread pressure. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Jobs, production and trade
Unemployment changes, hours worked, purchasing-manager surveys and industrial production indicate demand and business confidence. Trade shipment data add external perspective. Monthly releases can be revised, and some indicators lag turning points. Use three-month trends alongside annual comparisons to avoid mistaking seasonal noise for a regime change.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
What investors in Pakistan should monitor
Foreign remittances, import payments, export orders, the rupee and international oil prices transmit global stress to domestic conditions. Preserve liquidity for essential obligations and review high-leverage exposure. In uncertain markets, a disciplined allocation and rebalancing policy is usually more defensible than an all-or-nothing recession bet. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Comparison and decision framework
| Question | Stronger evidence | Warning sign |
|---|---|---|
| What drives returns? | Audited cash flows, clear contract or transparent index | Undefined or projected returns |
| What can go wrong? | Explicit scenario and downside analysis | Claims of guaranteed gains |
| Is it affordable to hold? | Low transparent fees and adequate liquidity | Leverage, costly spreads or lockups |
| Is access legitimate? | Appropriate licensing and clear legal rights | Unverified brokers or custody |
| Is the exposure diversified? | Multiple independent sources of return | One company, sector or currency |
What it means for Pakistani savers and investors
A Pakistani reader faces both international investment risk and local purchasing-power risk. For example, a foreign asset can rise in US-dollar terms while the rupee conversion and transaction costs alter the realized local outcome. The opposite can also occur. Record the starting exchange rate, applicable taxes, custody charges and capital-transfer restrictions, and confirm current requirements with the State Bank of Pakistan and the relevant securities regulator. Overseas access should not be assumed universally available.
An emergency reserve, expensive consumer debt and near-term family obligations deserve attention before any speculative allocation. A portfolio that cannot meet a sudden cash requirement may force sales at the worst moment. The objective is not to remove risk—impossible in markets—but to choose risks that fit the investor’s actual liabilities.
Risks, limitations and uncertainty
Institutional forecasts are conditional and can change after policy decisions, commodity shocks, conflict escalation or unexpectedly weak earnings. Historic correlations are not binding promises about future asset performance. The analysis does not provide live stock prices, current investment product quotes, real-time exchange rates or individualized tax advice. Prices, regulations and product eligibility should be checked on the transaction date.
Frequently asked questions
Is this a guaranteed investment opportunity?
No. Every financial asset or strategy involves uncertainty. The existence of a popular investment theme is not evidence that an individual security is fairly priced.
What should beginners examine first?
Understand the product, the financial loss you could tolerate, fees and liquidity. Verify the provider and decide whether the money may be needed soon.
How do interest rates affect the analysis?
They influence financing costs, discount rates, exchange rates and demand. The effect differs by sector, maturity and business balance sheet.
Can Pakistani residents invest in foreign markets?
Access depends on current foreign-exchange, banking, brokerage, securities and tax rules, and on the investor’s individual circumstances. Check current regulations and regulated providers rather than assuming access.
How often should this analysis be refreshed?
Review institutional economic releases monthly and re-evaluate immediately after material earnings, regulatory or policy changes. Avoid reacting mechanically to every daily market movement.
Is diversification enough to prevent losses?
No. Diversification may reduce company-specific risk but cannot eliminate broad market, currency, inflation or systemic risks.
Conclusion
Sound financial decisions begin with verifiable evidence, reasonable valuation, awareness of uncertainty and a plan that survives adverse outcomes. Readers should compare multiple independent sources and avoid letting a compelling headline substitute for due diligence.

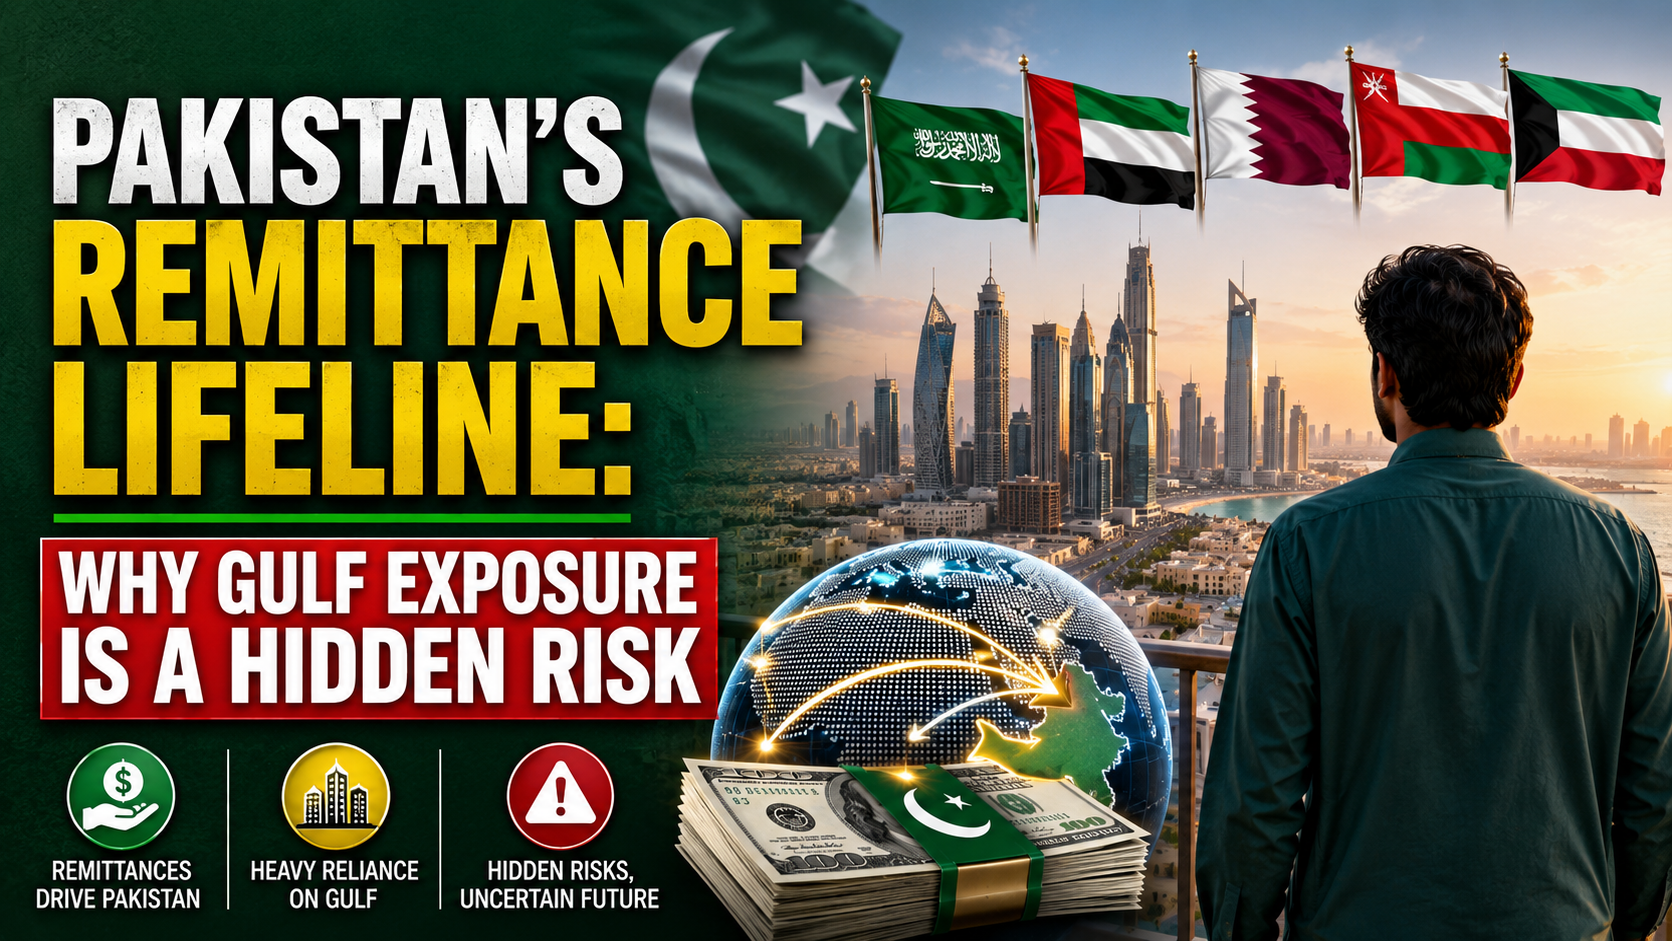
Buried inside the IMF’s latest Pakistan country report is a dependency that receives far less attention than headline GDP or inflation numbers, but arguably carries more immediate risk for millions of households: Pakistan’s economy is structurally exposed to whatever happens next in the Gulf.
The Numbers That Matter
Pakistan receives annual remittances amounting to roughly 9 percent of GDP, of which 55 percent originate from Gulf Cooperation Council countries, according to the IMF’s May 2026 country report. That single funding channel is one of the largest and most stable sources of foreign exchange available to the country — larger, in most years, than export revenue growth or foreign direct investment inflows combined.
The IMF’s own language is unambiguous about the risk this concentration creates: a significant disruption to GCC economies, or a forced return of migrant workers, could weigh heavily on these flows — a major source of financing for both household consumption and Pakistan’s broader balance of payments.
Why This Risk Is Live, Not Theoretical
This is not an abstract stress-test scenario. The Strait of Hormuz disruption, detailed extensively elsewhere in this series, has placed the entire Gulf region’s economic stability under genuine pressure for the first time in years. Should the conflict escalate further or trigger a broader regional economic slowdown, the transmission channel to Pakistan is direct and fast: fewer construction projects and reduced hiring across the GCC translates almost immediately into lower remittance flows from the millions of Pakistani workers employed there.
Capital Flows Are Already Reacting
The IMF has flagged early evidence that this dynamic is not purely hypothetical. Deteriorating global financial conditions have already resulted in capital outflows from Pakistan, which are likely to intensify further if the regional crisis extends, with the Fund specifically noting that access to short-term commercial financing — largely sourced from GCC banks — could also be affected if risk sentiment deteriorates further across the region.
This creates a double exposure that is easy to overlook in headline coverage: Pakistan depends on the Gulf both for the remittance income that supports household consumption, and for the short-term commercial bank financing that helps bridge its external funding gaps between IMF disbursements.
The State Bank’s Reserve Buffer
Pakistan’s own policy response has been to build reserves as a shock absorber. The State Bank of Pakistan has been projecting reserves to continue rising to roughly $18 billion by June 2026 on the back of planned inflows, a level implying that expected capital inflows currently exceed any current account shortfall — but only as long as Pakistan remains within an active IMF programme and maintains access to external funding on favourable terms.
The risk scenario flagged by policy researchers is specific: if monetary easing is mismanaged and confidence in Pakistan’s reform path falters, capital inflows could slow or reverse at the same time imports surge, opening an external funding gap that would draw down reserves and pressure the rupee — a scenario made materially more likely by any Gulf-region shock large enough to simultaneously dent remittances and tighten GCC bank lending.
How much of Pakistan’s remittances come from the Gulf?
Roughly 55% of Pakistan’s remittances — which fund about 9% of GDP — originate from Gulf Cooperation Council countries, making Pakistan’s balance of payments directly exposed to any economic disruption or capital-flow tightening in the Gulf region.
The Agricultural Wildcard
A related, more immediate risk sits in the agricultural supply chain. The IMF notes that disrupted DAP fertiliser supply chains linked to regional tensions could affect the Kharif planting season in June-July, with knock-on effects for food import prices — a second, more direct channel through which Gulf and broader Middle East instability could hit Pakistani households, independent of the remittance and capital-flow risks.
The Policy Takeaway
Pakistan’s economic stabilisation narrative in 2026 — a rebuilding KSE-100, falling inflation, a completed EFF review, covered in depth in our companion article — is real, but it rests on a foundation more exposed to Gulf regional stability than most headline coverage acknowledges. For policymakers in Islamabad, and for the Pakistani diaspora sending capital home each month, the Strait of Hormuz situation is not a distant geopolitical story. It is, in a very direct sense, a domestic economic risk factor.

How Fertiliser Prices Affect Food Prices and Affordability

Nvidia Stock (NVDA): When Extraordinary Growth Meets an AI Reality Check

Social Security vs SSI Payment Dates: The Differences That Matter in 2026–2027

The Fed’s 10–2 Hold: Why Two Dissenters Wanted a Rate Hike

US Impeachment Talk and White House Press Secretary Changes: What the Record Shows

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific
Intel 18A Foundry Strategy 2027: Capital Burn, Stock Sales & Break-Even Timeline
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
AI Impact on Wages 2026: Productivity Soars, Paychecks Stagnate
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained
Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts
-
Analysis5 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Markets & Finance11 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis10 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia11 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Blockchain10 months ago
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
-
Tech & AI3 months ago
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
-
Global Economy11 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact