Analysis
Gaming Giant’s Bold Gamble: Why Investors are Devouring Risky EA Debt Amid Geopolitical Crosscurrents

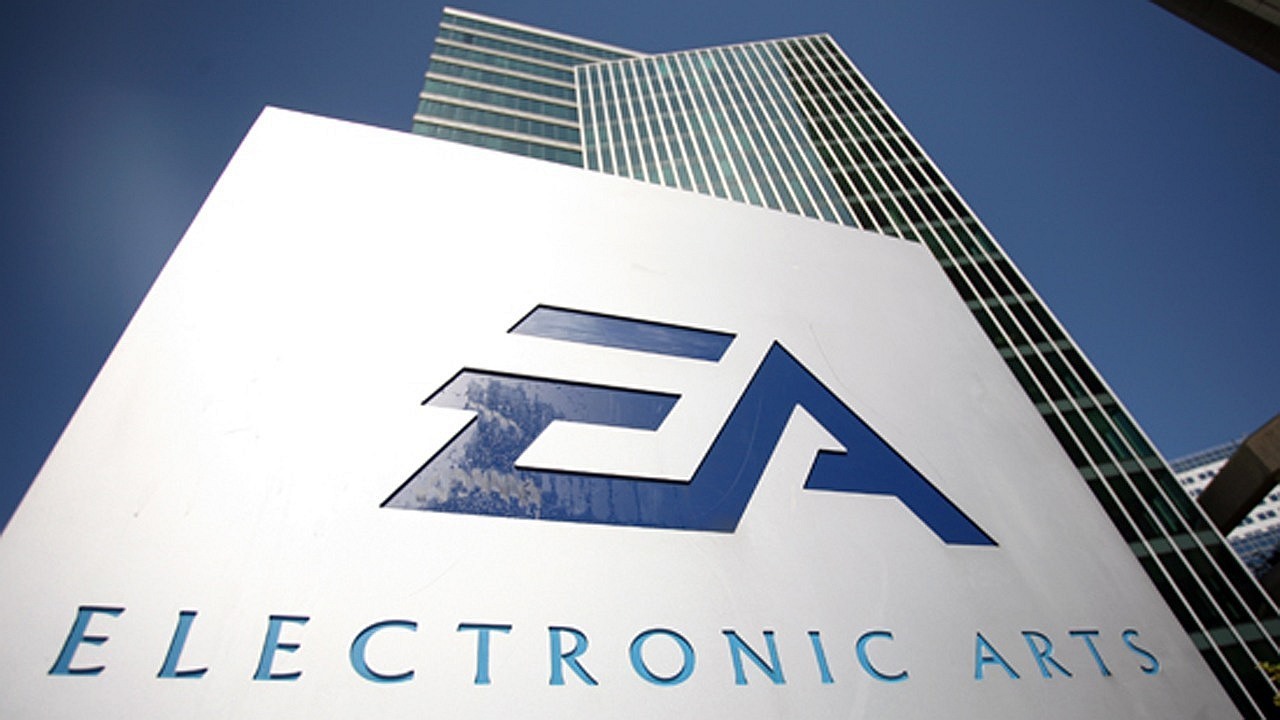
Investors are aggressively snapping up debt for Electronic Arts’ historic $55bn take-private, signaling resilient credit markets despite geopolitical tensions and AI disruption. Explore the EA LBO’s financial engineering, cost savings, and the appetite for risky video game financing in 2026.
Introduction: The Unyielding Allure of High-Yield
The world of high finance rarely pauses for breath, even as geopolitical headwinds gather and technological disruption reshapes industries. Yet, the recent $55 billion take-private of video game titan Electronic Arts (EA) has delivered a masterclass in market resilience, demonstrating an almost insatiable investor appetite for leveraged debt—even when tied to a complex, globally-infused transaction. Led by Saudi Arabia’s Public Investment Fund (PIF), Silver Lake, and Affinity Partners, this landmark deal, poised to redefine the gaming M&A landscape, has seen its $18-20 billion debt package met with overwhelming demand, proving that the pursuit of yield often eclipses lingering doubts.
This isn’t merely another private equity mega-deal; it’s a bellwether for global credit markets in early 2026. JPMorgan-led bond deals, designed to finance one of the largest leveraged buyouts in history, have drawn over $25 billion in orders, far surpassing their target size. This aggressive investor embrace of what many consider risky debt, particularly given the backdrop of Middle East tensions and concerns over AI’s impact on software, underscores a fascinating dichotomy: a cautious macroeconomic outlook juxtaposed with an audacious hunt for returns in stable, cash-generative assets. The question isn’t just how this was financed, but why investors dove in with such conviction, and what it signals for the year ahead.
The Anatomy of a Mega-Buyout: EA’s Financial Engineering
At an enterprise value of approximately $55 billion, the Electronic Arts take-private deal stands as the largest leveraged buyout on record, eclipsing the 2007 TXU Energy privatization. The financing structure is a finely tuned orchestration of equity and debt, designed to maximize returns for the acquiring consortium while appealing to a broad spectrum of debt investors.
Equity & Debt Breakdown
The EA $55bn LBO is funded through a combination of substantial equity and a significant debt tranche:
- Equity Component: Approximately $36 billion, largely comprising cash contributions from the consortium partners, including the rollover of PIF’s existing 9.9% stake in EA. PIF is set to own a substantial majority, approximately 93.4%, with Silver Lake holding 5.5% and Affinity Partners 1.1%.
- Debt Package: A substantial $18-20 billion debt package, fully committed by a JPMorgan-led syndicate of banks. This makes it the largest LBO debt financing post-Global Financial Crisis.
Unpacking the Debt Tranches: Demand & Pricing
The sheer scale of demand for this EA acquisition financing has been striking. The initial $18 billion debt offering, which included both secured and unsecured tranches, quickly swelled to over $25 billion in investor orders. This oversubscription highlights a strong market appetite for gaming-backed paper.
Key components of the debt include:
- Leveraged Loans: A cross-border loan deal totaling $5.75 billion launched on March 16, 2026, comprising a $4 billion U.S. dollar loan and a €1.531 billion ($1.75 billion) euro tranche.
- Pricing: Term Loan Bs (TLBs) were guided at 350-375 basis points over SOFR/Euribor, with a 0% floor and a 98.5 Original Issue Discount (OID). This discounted pricing suggests lenders were baking in some risk, yet the demand remained robust.
- Secured & Unsecured Bonds: The financing also features an upsized $3.25 billion term loan A, an additional $6.5 billion of other dollar and euro secured debt, and $2.5 billion of unsecured debt. While specific high-yield bond pricing hasn’t been detailed, market intelligence suggests secured debt at approximately 6.25-7.25% and unsecured north of 8.75%, reflective of the leverage profile.
The Deleveraging Path: Justifying a 6x+ Debt/EBITDA
Moody’s projects that EA’s gross debt will increase twelve-fold from $1.5 billion, pushing pro forma leverage (total debt to EBITDA) to around eight times at closing. Such high leverage ratios typically raise red flags, but the consortium’s pitch centers on EA’s robust cash flows and significant projected cost savings.
Three Pillars Justifying the Leverage
- Stable Cash Flows from Core Franchises: EA boasts an enviable portfolio of consistently profitable franchises, including FIFA (now EA Sports FC), Madden NFL, Apex Legends, and The Sims. These titles generate predictable, recurring revenue streams, particularly through live service models and annual updates, which underpin the company’s financial stability—a critical factor for debt investors.
- Strategic Cost Savings & Operational Efficiencies: The new owners have outlined an aggressive plan for $700 million in projected annual cost savings. This includes:
- R&D Optimization: $263 million from reclassifying R&D expenses for major titles like Battlefield 6 and Skate as one-time costs, now that they are live and generating revenue.
- Portfolio Review: $100 million from a strategic review of the game portfolio.
- AI Tool Integration: $100 million from leveraging AI tools for development and operations.
- Organizational Streamlining: $170 million from broader organizational efficiencies.
- Public Company Cost Removal: $30 million saved by no longer incurring costs associated with being a public entity.
These add-backs significantly bolster adjusted EBITDA figures, making the debt package appear more manageable to prospective lenders. Moody’s expects leverage to decrease to five times by 2029.
- Untapped Growth Potential in Private Ownership: Freed from quarterly earnings pressure, EA’s management can pursue longer-term strategic initiatives and R&D without the immediate scrutiny of public markets. This is particularly appealing for a company operating in an industry prone to rapid innovation and large, multi-year development cycles. The consortium’s diverse networks across gaming, entertainment, and sports are expected to create opportunities to “blend physical and digital experiences, enhance fan engagement, and drive growth on a global stage”.
Geopolitical Currents and the Appetite for Risky Debt
The influx of capital into the Electronic Arts bond deals is particularly noteworthy given the complex geopolitical backdrop of early 2026. Global markets are navigating sustained tensions in the Middle East, the specter of trade tariffs, and the disruptive force of artificial intelligence. Yet, these factors have not deterred investors from snapping up debt to finance Electronic Arts’ $55bn take-private.
The Saudi PIF Factor: Geopolitical Implications
The prominent role of Saudi Arabia’s Public Investment Fund (PIF) as the lead equity investor introduces a significant geopolitical dimension. The PIF, managing over $925 billion in assets, views this acquisition as a strategic move to establish Saudi Arabia as a global hub for games and sports, aligning with its “Vision 2030” diversification efforts. PIF’s deep pockets and long-term investment horizon offer stability often attractive to private equity deals.
However, the involvement of a sovereign wealth fund, particularly one with ties to Jared Kushner’s Affinity Partners, has not been without scrutiny. Concerns about national security risks, foreign access to consumer data, and control over American technology (including AI) have been voiced by organizations like the Communications Workers of America (CWA), who urged federal regulators to scrutinize the deal. Despite these geopolitical and regulatory considerations, the debt market demonstrated a remarkable willingness to participate. This indicates that the perceived financial stability and growth prospects of EA outweighed concerns tied to the source of equity capital.
AI Disruption and Market Confidence
The gaming industry, like many sectors, faces potential disruption from AI. Yet, EA itself projects $100 million in cost savings from AI tools, signaling a strategic embrace rather than fear of the technology. This forward-looking approach to AI, coupled with the inherent stability of established gaming franchises, likely contributed to investor confidence. In a volatile environment, proven entertainment IP acts as a relatively safe harbor.
The successful placement of this jumbo financing also suggests that while some sectors (like software) have seen “broader risk-off sentiment” due to AI uncertainty, the market distinguishes between general software and robust, content-driven interactive entertainment.
Broader Implications for Gaming M&A and Private Equity
The EA LBO is more than an isolated transaction; it’s a powerful signal for the broader M&A landscape and the future of private equity.
A Return to Mega-LBOs?
After a period where massive leveraged buyouts fell out of favor post-Global Financial Crisis, the EA deal marks a definitive comeback. It “waves the green flag on sponsors resuming mega-deal transactions,” indicating that easing borrowing costs and renewed boardroom confidence are aligning to facilitate large-cap M&A. The success of this deal, especially the oversubscription of its debt tranches, could embolden other private equity firms to pursue similar-sized targets in industries with reliable cash flows. This is crucial for private-equity debt appetite in 2026.
Creative Independence Post-Delisting
While private ownership offers freedom from public market pressures, it also introduces questions about creative independence. Historically, private equity has been associated with aggressive cost-cutting and a focus on short-term profits. For a creative industry like gaming, this can be a double-edged sword. While the stated goal is to “accelerate innovation and growth”, some within EA have expressed concern about potential workforce reductions and increased monetization post-acquisition. The challenge for the new owners will be to balance financial optimization with the nurturing of creative talent and IP development crucial for long-term success.
What it Means for 2027: Scenarios and Ripple Effects
As the EA $55bn take-private moves towards its expected close in Q1 FY27 (June 2026), its ripple effects will be closely watched by analysts and investors alike.
- Post-Deal EA Strategy: Under private ownership, expect EA to double down on its most successful franchises and potentially explore new growth vectors less scrutinized by quarterly reports. Strategic investments in areas like mobile gaming, esports, and potentially new IP development could accelerate. The projected cost savings will likely be reinvested to fuel growth or rapidly deleverage.
- Valuation Multiples: The deal itself sets a new benchmark for valuations in the gaming sector, particularly for companies with strong IP and predictable revenue streams. This could influence future M&A activities involving peers like Activision Blizzard (though now part of Microsoft) or Take-Two Interactive, raising their perceived floor valuations.
- Credit Market Confidence: The overwhelming investor demand for EA’s debt signals a powerful confidence in the leveraged finance markets, particularly for well-understood, resilient businesses. If EA successfully executes its deleveraging and growth strategy post-buyout, it will further validate the market’s willingness to finance large, complex LBOs, even amidst global uncertainty. This could pave the way for more “risky debt” deals tied to stable, high-quality assets.
- Geopolitical Influence in Tech: The PIF’s leading role solidifies the trend of sovereign wealth funds actively participating in global technology and entertainment sectors. This influence will continue to shape discussions around regulatory oversight, national interests, and the evolving landscape of global capital flows.
The investors snapping up debt to finance Electronic Arts’ $55bn take-private aren’t just betting on a video game company; they’re wagering on the enduring power of stable cash flows, strategic cost management, and a robust credit market willing to absorb risk for attractive yields. In a world grappling with uncertainty, the virtual battlefields of EA’s franchises offer a surprisingly solid ground for real-world financial gains.

Online interest in impeachment and White House staffing has risen in a political environment where a few words can badly distort the underlying story. A resolution was introduced is not the same as the House voted to impeach. A press secretary was removed is not the same as the administration changed policy. Both require evidence, dates and clear procedural language.
Two verifiable developments frame the discussion as of October 25, 2026. A House impeachment resolution was tabled on September 15, and the short tenure of White House press secretary Katie Zacharia ended in mid-October, according to official congressional records and major US reporting. Neither event should be inflated into an unverified claim about new votes or a new administration decision.
The impeachment resolution: what the House actually voted on
House Resolution 1486 concerned impeachment of President Donald Trump. The US House’s official floor summary records the September 15 vote on a motion to table the measure: 232–147, with 47 members recorded as present. A successful tabling motion sets aside a measure; it is not the adoption of articles of impeachment.
This distinction is essential. A social post describing that roll call as a vote to impeach reverses the outcome. A later claim about a different resolution should be separately checked against the official Congress website and House roll-call records rather than treated as an update to an old headline without evidence.
Congressional procedure is sometimes inconvenient for trending-content production. It is also what protects the reader from misinformation. The reporter’s task is to identify the motion, the chamber, the date and the disposition before attempting broader political interpretation.
What happened to the press secretary?
CBS News reported on October 16 that Zacharia was removed from the White House press-secretary role after roughly five days. CBS cited US officials and reported scrutiny of her credentials and performance. It also noted that the White House had not yet announced a successor in that report.
A leadership change in the briefing room can be significant for how an administration communicates with journalists and the public. But personnel turnover alone does not establish a change to economic policy, foreign strategy or legal proceedings. Those substantive conclusions require separate evidence.
Why the two stories became combustible
Impeachment is a constitutionally consequential process and a powerful political symbol. White House press briefings are the main arena where officials defend decisions under questioning. When both topics circulate at once, online narratives may stitch them into a supposed constitutional crisis—even if there is no documented direct connection.
A measured account must resist that temptation. Political opponents may view impeachment proposals as necessary oversight; supporters of the president may describe them as partisan exercises. The purpose of reporting is not to resolve those disagreements by advocacy, but to distinguish political argument from verifiable institutional action.
The fact-checker’s four-part test
| Question | Evidence needed |
|---|---|
| Was an impeachment measure introduced? | Official resolution number and introduction date |
| Did the House approve articles? | Recorded vote on adopting the relevant articles |
| Was an official removed? | Direct statement or multiple reliable attributed reports |
| Who now holds the position? | Current White House announcement, not an old biography |
This is particularly important during a midterm-election year. Campaigns and commentators have incentives to present ordinary procedural setbacks as existential victories or defeats. Readers benefit from precise language instead of ever-louder adjectives.
What should international readers take from it?
For audiences in Pakistan and elsewhere in Asia, US political turmoil matters when it alters policy certainty: trade measures, sanctions, diplomacy, defence arrangements, fiscal decisions and monetary-policy appointments. None should be projected automatically from a press secretary’s dismissal or a resolution that did not pass.
It is sensible to monitor official notices, court actions and enacted policy. It is not sensible to treat search-volume spikes as proof of truth. Search trends measure curiosity, fear and newsworthiness; they do not independently confirm the event people are typing about.
Why parliamentary verbs matter
US political coverage frequently compresses filed, referred, tabled, passed and enacted into the generic word approved. Those actions are not interchangeable. A resolution can be introduced without advancing beyond committee. A motion to table is a vote about whether the chamber will proceed, not a judgment approving the underlying allegations. A measure passed by one chamber may still require further constitutional steps.
The same precision is necessary in personnel news. A spokesperson’s announced departure, a media report citing officials and a formal appointment are different evidence levels. Where the administration has not issued a replacement notice, describing a favourite online rumour as the current officeholder is poor reporting.
Public debate about impeachment also should not be reduced to the number of search queries. Search interest can be increased by critics, supporters, confused readers or social platforms circulating an old clip. It gives no reliable denominator for public opinion. A survey with a known sample and methodology is a different kind of evidence.
The best follow-up coverage would monitor official House actions and White House releases, then connect any actual policy changes to their legal basis. That approach serves readers across the political spectrum without manufacturing a crisis.
Has the September 15 House vote impeached Trump?
No. The recorded action was a successful motion to table the resolution, not a vote approving impeachment articles.
Was Katie Zacharia removed?
Yes, CBS reported her departure from the role on October 16. Any later staffing changes should be checked directly before publication.
Do impeachment trends reveal who will win the midterms?
No. Search spikes are not representative polling or an election forecast.
The standard worth keeping: precise institutional language is not timid journalism. It is the difference between telling readers what happened and telling them what a viral headline wants them to believe.
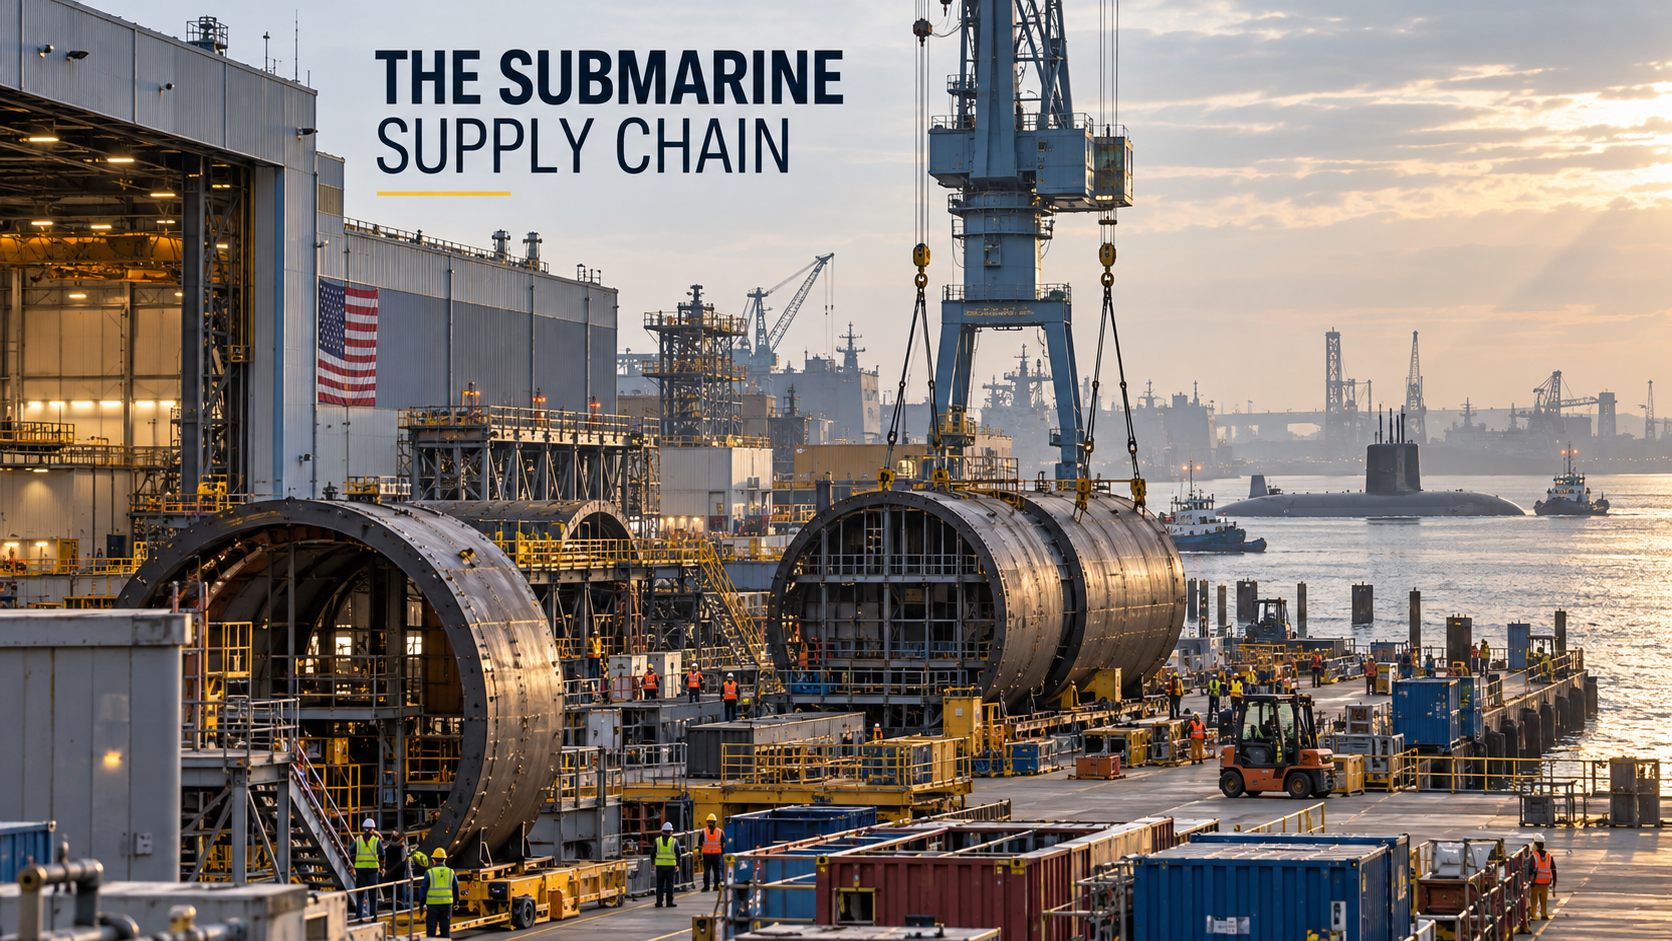
A major U.S. submarine-manufacturing project announced on October 6, 2026 has put an unfamiliar name at the center of a familiar defense-industry problem: how to build submarine components faster without sacrificing quality or reliability. Defense technology firm Anduril announced plans for Arsenal-2, a facility at Sparrows Point in Maryland intended to expand production of parts for the U.S. Navy’s Virginia-class attack submarines. The combined headline figure is $6.6 billion—made up of the company’s planned $3.7 billion private investment and a Navy contract valued at up to $2.9 billion, with payments tied to production outcomes. These are announcements and commitments, not evidence that all the capital has already been spent. Anduril’s official announcement and Reuters’ independent report outline the project.
Key takeaways:
- Arsenal-2 is a planned submarine-components manufacturing facility, not an already operational assembly line for completed submarines.
- The $6.6 billion headline combines two different funding streams and different forms of financial commitment.
- The project is aimed at bottlenecks in the Virginia-class supply chain, including specialized manufacturing capacity.
- Its success will depend on skilled labor, qualification standards, equipment, scheduling and delivery—not simply construction of a large building.
What is Arsenal-2?
Arsenal-2 is Anduril’s proposed software-centered manufacturing project at Sparrows Point, a former industrial site in Baltimore County, Maryland. According to the company’s October 6 announcement, the facility is designed to make critical components for Virginia-class submarines and give the Navy access to additional industrial capacity. The project illustrates a widening role for technology-sector defense contractors in traditional heavy manufacturing.
Submarine construction is a particularly difficult domain. Components must meet demanding specifications for performance, durability, safety, quality control and compatibility with other systems. A factory that produces ordinary industrial hardware cannot immediately be treated as a qualified submarine supplier.
Anduril’s pitch is that modern factory software, automation, new processes and private capital can ease some of those constraints. Whether the company can execute on that pitch will be judged by qualification milestones and repeatable deliveries.
What will the facility actually produce?
Initial work centers on critical Virginia-class components, including torpedo tubes, according to the company and Reuters. Those are sophisticated submarine systems, but producing them is not the same as manufacturing a complete nuclear-powered submarine.
A Virginia-class attack submarine involves propulsion, pressure-hull construction, combat systems, sensors, life-support equipment, electronics, integrated software and years of testing. Its final assembly and delivery depend on a specialized network of contractors, yards and government oversight. New suppliers can strengthen the network by removing specific bottlenecks rather than replacing every incumbent shipbuilder.
The distinction matters for readers encountering sweeping “Anduril to build submarines” headlines. The verified announcement concerns industrial capacity for components, with ambitions that may expand as the project matures; it should not be presented as a commitment to launch an entire finished fleet by a fixed date.
Understanding the $6.6 billion figure
| Announced element | Stated figure | Important qualification |
|---|---|---|
| Anduril planned private capital | $3.7 billion | Planned investment to develop production capacity |
| U.S. Navy contract | Up to $2.9 billion | Contract ceiling with payments conditioned on outputs |
| Combined headline amount | $6.6 billion | Sum of different commitments; not identical to money already disbursed |
Anduril’s release describes the contract as outcome-based. That arrangement is designed to connect government spending to verified delivery rather than solely to reimbursed activity. But details of individual milestones, acceptance criteria, ownership and long-term risk allocation should be determined from contract documents—not guessed from a launch-day headline.
The distinction between an award, a contract ceiling, a planned investment and cash expenditure is crucial. A press announcement does not mean the project has already consumed $6.6 billion in cash or delivered proportionate output.
Why the Navy needs more industrial capacity
Submarines are strategically important for intelligence collection, maritime defense and deterrence. But they also illustrate the challenges of complex, low-volume manufacturing. The United States needs trained workers who can perform specialized fabrication, welding, machining, inspection and systems integration. Individual suppliers can become bottlenecks if they are asked to deliver more components than their equipment or workforce can manage.
The Financial Times’ account of the announcement situated Arsenal-2 within a larger push to expand the submarine industrial base and modernize acquisition. The Navy’s construction requirements and commitments under the AUKUS security partnership increase the importance of sustainable production capacity over the coming years.
This is a long-term manufacturing question, not an immediate shortcut. Building a factory is one stage; training a workforce, validating manufacturing processes and coordinating with other shipbuilders are additional stages.
Why Sparrows Point matters
Sparrows Point was a major American industrial center associated with steel production. Using that site for advanced defense manufacturing creates a recognizable local economic narrative: industrial land and workforce capacity potentially being redirected toward a contemporary strategic sector.
Associated Press reporting described expectations of approximately 3,100 direct jobs connected to the facility, while Reuters reported similar plans. They are projected jobs rather than a verified count of positions already filled.
The ultimate local impact will depend on the pace of construction, hiring, regional supply chains, transport needs, worker training and how much demand the project sustains. Job announcements should be revisited against actual payroll, construction and production data.
When will Arsenal-2 begin manufacturing?
Accounts of the project point to operations around 2030, subject to execution. Business Insider and Financial Times discussed that timeline. Treat it as a planned target, not an operational fact.
Even if initial lines become active on schedule, production volume and acceptance quality will determine how useful the added capacity becomes to the Navy. A component supplier can have machinery installed yet still face qualification delays, workforce shortages or unexpected integration issues.
The execution milestones worth tracking
- Facility permits, ground work and construction progress.
- Hiring and certification of specialist personnel.
- Commissioning of production lines and inspection systems.
- First qualified component deliveries accepted by the relevant customer.
- Repeat production rates, quality performance and on-time deliveries.
- Evidence that the additional capacity reduces delays in the broader submarine supply chain.
These measurable steps provide a better accountability framework than celebrating the contract’s face value alone.
Can software solve a shipbuilding bottleneck?
Software can improve production scheduling, digital modeling, machine monitoring, traceability and quality documentation. Automation may make some operations more consistent. Those are useful tools, but they still rely on expensive physical equipment, material supply and highly skilled people. A complex pressure-critical component cannot be delivered by software alone.
The question is therefore not whether a tech company can bring useful technology into shipbuilding. It is whether that company can combine technology with industrial practices refined over decades, and do so at sufficient scale.
Frequently asked questions
Is Anduril building complete submarines?
Its verified October 6 announcement emphasizes components for Virginia-class submarines, not delivery of complete nuclear-powered boats.
Where is Arsenal-2 located?
The project is planned for Sparrows Point in Baltimore County, Maryland.
How much is the Navy paying?
Anduril announced a Navy contract of up to $2.9 billion, distinct from the company’s planned $3.7 billion capital investment.
When will it open?
Reports describe a target around 2030. The actual schedule depends on construction, production-line qualification and other milestones.
How many jobs could be created?
Approximately 3,100 direct jobs were projected in contemporaneous reporting; these are not confirmed hires.
Why is this important for AUKUS?
A more resilient U.S. submarine industrial base can support national procurement needs and wider allied commitments, although a single parts factory cannot resolve all submarine-production constraints.
Bottom line
Arsenal-2 is significant because it tests whether a technology-focused contractor can add reliable industrial capacity to one of America’s hardest manufacturing sectors. The $6.6 billion figure describes a potentially major investment and contract arrangement—but future milestones, not headlines, will determine whether it meaningfully speeds submarine deliveries.
Key Takeaways
- Chip stocks tumbled Monday, September 14, 2026, after the CEOs of Anthropic, OpenAI, and xAI publicly aligned behind a call to slow the pace of frontier AI capability development — an unusual moment of unity among fierce industry rivals.
- Nvidia fell 3.4% and the Philadelphia Semiconductor Index (PHLX) sank almost 6%, its worst single day since early July, even as the broader Nasdaq Composite closed down a more modest 0.56%.
- The catalyst was an essay from Anthropic CEO Dario Amodei, titled “We Must Pace the Frontier,” proposing independent outside evaluators be given internal access to frontier AI labs, alongside industry-wide cooperation and government coordination.
- OpenAI CEO Sam Altman confirmed in a Fortune interview that OpenAI will not pursue an IPO in 2026, calling the current safety environment an “ill-advised moment” to go public — pushing one of the most anticipated listings in tech history to 2027 at the earliest.
- The episode followed the resignation of a researcher who had worked at both Anthropic and OpenAI, who warned publicly that people building the technology “earnestly believe it could kill us all by the end of the decade” — a post that drew over 150 million views and prompted more than 20 lawmakers to call for tougher AI regulation.
A rare display of unity among Silicon Valley’s most competitive AI labs sent a jolt through markets this week, as semiconductor stocks logged their worst day in over two months following public calls from the industry’s top executives to deliberately slow the development of increasingly powerful AI systems.
What Triggered the Selloff
The catalyst was an essay published Saturday, September 12, by Anthropic CEO Dario Amodei, titled “We Must Pace the Frontier.” In it, Amodei argued that unchecked acceleration in frontier AI development — driven in part by the risk of recursive self-improvement, where AI systems increasingly assist in designing their own successors — is outpacing the industry’s ability to keep those systems aligned and secure. Amodei wrote that he believes AI could still “dramatically raise the quality of human life,” but argued the risks accompanying its current pace of development need to be taken seriously, proposing that even a modest slowdown of a year or two could meaningfully improve safety outcomes.
What made the essay market-moving wasn’t just its content, but who endorsed it. OpenAI CEO Sam Altman and SpaceX/xAI’s Elon Musk — two executives whose companies compete directly with Anthropic and with each other — both publicly backed Amodei’s proposal within a day. Musk wrote simply on X that “Dario is right,” a notable shift given Musk’s history of sharp public criticism of Anthropic.
The Proposal’s Substance
Amodei’s plan outlined a three-phase approach: independent safety evaluators embedded within frontier AI companies with access equivalent to internal staff (covering training processes, internal systems, and safety-protocol compliance); broader industry-wide cooperation on shared safety standards; and coordination with democratic governments on global regulatory frameworks. Anthropic said it would adopt the outside-evaluator step immediately, while Altman confirmed OpenAI would adopt comparable third-party evaluator access.
The Resignation That Set the Stage
The unity among AI executives followed a more unsettling precursor: a researcher who had previously worked at both Anthropic and OpenAI resigned the prior week, writing publicly that people building the technology “earnestly believe that it could kill us all by the end of the decade.” The post reportedly drew more than 150 million views on X and prompted more than 20 lawmakers to call for tougher AI regulation — context that appears to have accelerated the executives’ public alignment on pacing concerns.
Market Reaction: Chips Hit Hardest
Monday’s trading session showed a clear divergence in how different corners of the AI-linked market absorbed the news. Semiconductor stocks bore the brunt of the selling, given their direct exposure to the capital-expenditure cycle that rapid AI capability development has fueled. Nvidia fell 3.4%, Intel dropped 5.6%, and the Philadelphia Semiconductor Index tumbled nearly 6% — its steepest one-day decline since early July.
By contrast, shares of some larger Big Tech and software companies actually climbed on the day, leaving the broader, tech-heavy Nasdaq Composite down a comparatively modest 0.56%, after having fallen as much as 1.3% intraday before paring losses. The divergence suggests markets are interpreting a potential AI development slowdown as a more direct threat to chip demand specifically — the hardware layer most tied to the “faster, bigger” capability race — than to software and platform companies with more diversified revenue.
OpenAI’s IPO Delay: The Clearest Business Signal
Beyond the one-day stock move, the most concrete business consequence to emerge from the episode was Sam Altman’s confirmation that OpenAI will not go public in 2026. In a Fortune interview published the same weekend, Altman said an IPO “right now would be an ill-advised moment” given the current safety environment, and when asked whether 2027 was more realistic, replied simply, “I would say not 2026.” That timeline represents a real shift: OpenAI CFO Sarah Friar had told employees just a month earlier that the company would likely go public in 2027, or potentially sooner if the business continued to “inflect.”
Notably, Anthropic’s own IPO preparations are reportedly continuing on a separate track. According to reporting on the matter, Anthropic — confidentially valued at $965 billion earlier in 2026 — has continued meeting with prospective investors and could begin marketing its IPO as early as October, aiming to complete the listing before the November midterm elections, even as its CEO simultaneously champions industry-wide deceleration. Observers have noted the apparent tension in pursuing an IPO while publicly urging pacing, though Amodei’s essay explicitly framed pacing as slowing capability development, not halting commercial or fundraising activity.
Market Snapshot: September 14, 2026
| Index / Stock | Move | Note |
|---|---|---|
| Philadelphia Semiconductor Index (SOX) | -5.9% | Worst day since early July |
| Nvidia (NVDA) | -3.4% | Direct AI-chip exposure |
| Intel (INTC) | -5.6% | |
| Nasdaq 100 | -0.8% | |
| Nasdaq Composite | -0.56% | Software names partially offset chip losses |
| S&P 500 | -0.5% |
Why This Matters for Technology News and Investors
This episode marks one of the first times investor sentiment around AI has moved meaningfully on a safety-driven narrative rather than a purely commercial one — competitive product launches, earnings beats, or compute-capacity announcements. For investors tracking technology news, the key signal to watch going forward is whether this represents a genuine, sustained industry pivot toward deliberate pacing (which could structurally slow the capital-expenditure supercycle currently powering semiconductor demand), or a rhetorical moment that fades once competitive pressure between OpenAI, Anthropic, xAI, and other labs reasserts itself — a tension the OpenAI-Anthropic IPO-timing contrast already illustrates.
Frequently Asked Questions
Why did semiconductor stocks fall after the AI slowdown announcement? Chip stocks are directly tied to the capital-expenditure cycle fueling rapid AI capability development, so markets interpreted a potential industry-wide pacing effort as a more direct threat to near-term chip demand than to software or platform companies.
Is OpenAI still planning to go public? Yes, but not in 2026. CEO Sam Altman confirmed OpenAI is delaying its IPO to 2027 at the earliest, citing the current AI safety environment, while OpenAI’s CFO had previously suggested 2027 was the likely target regardless.
What did Anthropic’s CEO actually propose? Dario Amodei’s essay proposed embedding independent outside safety evaluators within frontier AI companies with internal-level access, alongside broader industry cooperation on safety standards and coordination with democratic governments on regulatory frameworks — explicitly framed as pacing capability development, not halting it.

US Impeachment Talk and White House Press Secretary Changes: What the Record Shows

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide

Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
AI Impact on Wages 2026: Productivity Soars, Paychecks Stagnate
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Analysis4 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025