Exclusive
The Trade Bazooka: How the EU’s Retaliatory Powers Could Reshape the US Economy in 2026 Amid Trump’s Tariffnomics

The Arctic chill descending on Nuuk this January is nothing compared to the deep freeze threatening transatlantic relations. As Greenlandic citizens march through their capital’s snowy streets protesting President Trump’s demands to purchase their homeland, a far more potent economic weapon is being primed in Brussels. The European Union stands poised to deploy what French officials have dubbed the “trade bazooka”—a never-before-used instrument that could fundamentally reshape the American economy in ways that Trump’s own tariff strategy never anticipated.
The standoff crystallizes a broader transformation in global economic governance. On one side: Trump’s “tariffnomics,” a doctrine of aggressive protectionism designed to extract concessions through economic coercion. On the other: Europe’s Anti-Coercion Instrument, legislation explicitly crafted to punish precisely this kind of behavior. As both sides escalate toward what could become the most consequential trade confrontation since the Smoot-Hawley tariffs deepened the Great Depression, the United States economy faces headwinds that even optimistic forecasters cannot dismiss.
The question is no longer whether Europe will retaliate, but how severely—and what that means for American consumers, businesses, and the broader economic trajectory of 2026.
Trump’s Tariffnomics in 2026: Greenland, Geopolitics, and Economic Nationalism
President Trump’s tariff strategy has entered unprecedented territory. On January 18, 2026, he announced that eight European nations—Denmark, Norway, Sweden, France, Germany, the United Kingdom, the Netherlands, and Finland—would face 10% tariffs beginning February 1, escalating to 25% by June 1 unless Denmark agrees to sell Greenland to the United States. The ultimatum marked a dramatic fusion of territorial ambition and trade policy unmatched in modern American history.
The timing was no accident. These tariffs target NATO allies who deployed military personnel to Greenland for joint exercises—a move Trump characterized as interference with American national security interests. “China and Russia want Greenland, and there is not a thing that Denmark can do about it,” Trump declared on social media, justifying the economic pressure as essential to prevent adversarial powers from gaining Arctic influence.
This Greenland gambit represents the latest escalation in what analysts have termed “tariffnomics”—Trump’s conviction that tariffs function not merely as trade tools but as multipurpose instruments of statecraft. Throughout 2025, the administration imposed what it called “Liberation Day” tariffs, bringing the weighted average applied tariff rate to 15.8%, the highest since 1943. The cumulative effect amounts to what the Tax Foundation estimates as a $1,500 annual tax increase per American household in 2026.
But the Greenland tariffs differ in crucial respects from previous measures. Unlike tariffs justified by national security concerns or trade imbalances, these explicitly aim to pressure a sovereign ally into ceding territory—a colonial-era objective dressed in 21st-century economic warfare. Even within Trump’s own Republican Party, the move has drawn condemnation. Senator Thom Tillis called it “great for Putin, Xi and other adversaries who want to see NATO divided,” while Senator Rand Paul rejected the notion that emergency powers could justify such unilateral taxation.
The economic rationale behind tariffnomics rests on several pillars: protecting American manufacturing, reducing trade deficits, and compelling foreign governments to make concessions. Proponents argue that decades of free trade agreements hollowed out America’s industrial base, and that aggressive tariffs—despite short-term pain—will ultimately reshore production and strengthen national resilience.
Yet as Peterson Institute economists have documented, the evidence from Trump’s first-term trade war tells a different story. Research shows that tariffs reduce US growth rates by 0.23 percentage points in 2025 and 0.62 percentage points in 2026, while temporarily raising inflation by approximately one percentage point. Employment declines most sharply in sectors most exposed to global supply chains: durable goods manufacturing, mining, and agriculture. The jobs lost often fail to materialize elsewhere, as industries cannot easily onshore complex production networks built over decades.
The Greenland tariffs compound these effects. By targeting major European economies whose combined GDP exceeds $15 trillion, Trump has effectively placed the world’s second-largest economic bloc in his crosshairs. European leaders, meeting in emergency session in Brussels, have made clear they will not accede to what Danish Prime Minister Mette Frederiksen called “blackmail.”
The EU’s Trade Bazooka Explained: How the Anti-Coercion Instrument Works
Enter the Anti-Coercion Instrument—the European Union’s most powerful economic countermeasure and one that has never been deployed in its three-year existence. Adopted in November 2023 and entering force in December of that year, the ACI was designed explicitly to deter economic blackmail by third countries seeking to influence EU policy through trade restrictions or investment threats.
The instrument’s scope extends far beyond conventional retaliatory tariffs. As EU officials have outlined, the ACI allows Brussels to:
- Restrict US suppliers’ access to the EU’s single market of 450 million consumers
- Exclude American companies from public procurement contracts across member states
- Impose limitations on foreign direct investment from the United States
- Restrict trade in both goods and services
- Target intellectual property rights and financial market access
This comprehensive toolkit earned the ACI its menacing nickname. Unlike standard tariffs that simply tax imports, the trade bazooka can effectively shut American businesses out of entire market segments. For US tech giants deriving substantial revenue from European operations, the implications are profound. For American manufacturers relying on European components or sales, the disruption could be existential.
The ACI’s procedural architecture balances deterrence with deliberation. Once triggered, the European Commission has four months to investigate whether economic coercion has occurred—defined as a third country “applying or threatening to apply measures affecting trade or investment in order to prevent or obtain the cessation, modification or adoption of a particular act by the European Union or a member state.” Following the investigation, EU member states must approve activation by qualified majority vote, removing the veto power that has historically paralyzed European trade policy.
If approved, the Commission enters a negotiation phase with the coercing country. Should diplomacy fail, Brussels can implement response measures within six months. Critically, these measures can target specific companies, sectors, or even individuals—a surgical precision that contrasts sharply with Trump’s blunt-instrument approach.
French President Emmanuel Macron has emerged as the ACI’s most vocal champion, urging immediate activation in response to the Greenland tariffs. French Finance Minister Roland Lescure stated Monday that the EU “must be prepared” to deploy the mechanism. Yet not all member states share France’s enthusiasm. Germany, heavily dependent on exports and wary of escalation, has historically resisted deploying the instrument. The debate reflects deeper tensions within European economic policy: whether to match American aggression measure-for-measure or pursue de-escalation to preserve economic stability.
The EU has already prepared substantial groundwork. During last year’s trade tensions, Brussels compiled a list of American goods worth €93 billion ($108 billion) for potential retaliation. Those targets were strategically selected to maximize political impact: bourbon from Kentucky, Harley-Davidson motorcycles from Wisconsin, aircraft components affecting Boeing’s production—products concentrated in Republican-leaning states. The EU learned from China’s 2018 playbook, which targeted agricultural products from electorally sensitive regions to pressure Trump domestically.
But the ACI goes further. Rather than simply taxing imports, it could impose what amounts to regulatory exile. American companies might find themselves barred from competing for lucrative European infrastructure projects, excluded from financial services markets, or facing restrictions on data flows that underpin digital commerce. For an American economy where services represent roughly 70% of GDP and technology companies generate enormous profits from European operations, these measures could inflict damage far exceeding traditional tariff retaliation.
The Activation Question: Will Europe Pull the Trigger?
As European leaders convene this week at the World Economic Forum in Davos, the activation debate has moved from theoretical to imminent. Reports indicate that officials are drawing up retaliation measures to provide leverage in pivotal meetings with Trump, though whether those measures will actually be implemented remains uncertain.
Several scenarios could trigger ACI deployment:
Scenario One: Graduated Retaliation. The EU might opt for proportional tariffs on the $108 billion worth of American goods identified, avoiding the more drastic measures of market exclusion. This approach preserves escalation options while demonstrating resolve. However, it also risks appearing weak—matching Trump’s tariffs dollar-for-dollar rather than exploiting Europe’s more powerful legal instrument.
Scenario Two: Full-Spectrum Response. France’s preferred approach would activate the ACI comprehensively, combining tariffs with restrictions on services, investment, and procurement access. This maximalist strategy aims to impose costs substantial enough to force Trump to recalculate. The risk: such aggressive action could trigger an all-out economic war, with Trump responding by escalating further rather than backing down.
Scenario Three: Surgical Strikes. Brussels could deploy targeted measures against specific American sectors or companies most vulnerable to European market exclusion. Technology companies like Apple, Google, Microsoft, and Amazon derive between 20-30% of revenues from Europe. Restrictions on their European operations—perhaps through stringent data localization requirements or limits on public sector contracts—could deliver concentrated pain while avoiding broader economic spillover.
Scenario Four: Strategic Delay. The EU might initiate the ACI investigation process without immediate action, using the four-month timeline as a negotiating period. This approach signals seriousness while preserving diplomatic off-ramps. However, it risks emboldening Trump, who might interpret hesitation as weakness.
The internal European debate reflects divergent economic philosophies and national interests. France, with its tradition of economic dirigisme and strategic autonomy, views the ACI as essential to defending European sovereignty. Germany, whose export-dependent economy thrives on open markets, fears that retaliation could damage its own interests as much as America’s. Smaller member states worry about becoming collateral damage in a superpower clash.
Deutsche Bank has issued stark warnings: if Trump persists with Greenland tariffs, European governments might begin selling off US assets worth approximately $8 trillion, potentially weakening both the dollar and the American economy substantially. Such capital reallocation would represent a fundamental reconfiguration of transatlantic financial relationships.
Economic Impact on the United States: GDP, Inflation, and Sectoral Disruption
To assess the potential damage, we must layer the EU’s retaliatory measures atop existing economic headwinds. The American economy enters 2026 with mixed signals: strong GDP growth driven by AI investment and consumer spending, but mounting pressures from tariff-induced inflation, slowing employment growth, and deteriorating business confidence.
Baseline Projections vs. Trade War Scenarios
The IMF projects US real GDP growth of 2.1% for 2026, with inflation gradually returning to the Federal Reserve’s 2% target. Goldman Sachs forecasts slightly higher growth at 2.6%, citing technology investment and fiscal stimulus. Morgan Stanley anticipates moderate expansion with core PCE inflation reaching 2.6% by year-end before declining in 2027.
These projections, however, assume no major trade disruptions. The Greenland tariffs and potential EU retaliation were not factored into models finalized before January. Updated assessments paint a darker picture.
Peterson Institute modeling of comprehensive trade war scenarios—combining US tariffs and foreign retaliation—estimates cumulative GDP losses of 0.4% to 0.7% relative to baseline by 2026. Their analysis shows that tariffs alone might reduce growth by 0.62 percentage points in 2026, but retaliation could more than double these losses. The total economic cost to American households from tariffs and retaliatory measures could approach $1,500 annually, with effects concentrated among middle- and lower-income families who spend larger shares of income on tradeable goods.
If the EU deploys its full ACI arsenal, the damage intensifies. Restrictions on American services exports—where the US maintains a substantial trade surplus with Europe—would hit particularly hard. Financial services, technology licensing, management consulting, and entertainment sectors could face European regulatory barriers that effectively shrink their addressable market. For companies like Goldman Sachs, JPMorgan, and major tech platforms, losing unfettered European access would directly impact bottom lines.
Inflation: The Hidden Tax of Trade Wars
The inflationary impact of tariffs represents perhaps the most insidious economic consequence. Tax Foundation estimates indicate that Trump’s tariffs will reduce after-tax incomes by 1.2% on average in 2026 through higher consumer prices. The Greenland tariffs, affecting approximately $200 billion in European imports annually, would add further upward pressure on prices for vehicles, machinery, pharmaceuticals, and consumer goods.
European retaliation compounds this effect. If Brussels targets American agricultural exports—a likely scenario given the sector’s political sensitivity—US farmers lose key markets, depressing commodity prices and farm incomes. Simultaneously, retaliatory tariffs on American machinery and technology exports raise costs for European businesses, some of which might respond by shifting production to non-US suppliers, permanently eroding American market share.
The Federal Reserve faces an unenviable dilemma. Tariff-driven inflation typically proves transitory, as one-time price level increases work through the system. But sustained trade war escalation creates persistent inflationary pressure, potentially forcing the Fed to maintain higher interest rates longer than otherwise necessary. Current projections anticipate the Fed reducing rates to 3.0-3.25% by mid-2026, but significant trade disruption could pause or reverse that easing cycle.
Higher-for-longer interest rates cascade through the economy: more expensive mortgages dampen housing markets, elevated borrowing costs constrain business investment, and the strong dollar makes American exports less competitive globally. The irony is palpable—tariffs intended to protect American industry might inadvertently strengthen the very currency that undermines export competitiveness.
Sectoral Analysis: Winners and Losers
The distributional effects of EU retaliation vary dramatically across American economic sectors:
Technology: Maximum Vulnerability
American tech giants face existential threats from comprehensive EU countermeasures. Apple, which generates approximately 25% of revenue from Europe, could see restrictions on iPhone sales, App Store operations, or regulatory requirements so burdensome that profit margins collapse. Google and Meta derive substantial advertising revenue from European markets; restrictions on data processing or targeted advertising would directly hit earnings. Microsoft’s cloud services business depends on seamless transatlantic data flows—flows that ACI measures could severely constrain.
The EU has already demonstrated willingness to challenge American tech dominance through regulations like GDPR and the Digital Markets Act. Weaponizing these regulatory frameworks within the ACI context could exclude US companies from lucrative government contracts, impose prohibitive compliance costs, or effectively balkanize digital markets. For a sector that has driven much of America’s recent GDP growth, the consequences would ripple throughout the broader economy.
Automotive: Supply Chain Catastrophe
The automotive sector operates through intricate transatlantic supply chains. A single vehicle might incorporate components sourced from a dozen countries, with engines manufactured in Germany, electronics from Taiwan, and final assembly in the United States or Mexico. EU restrictions on American auto parts exports, or retaliatory tariffs on vehicles, would disrupt these networks catastrophically.
Ford and General Motors maintain substantial European operations; both companies could face impossible choices about where to allocate investment if transatlantic commerce fragments. Tesla, despite CEO Elon Musk’s calls for free trade, operates a major manufacturing facility in Berlin—one that could become a liability if US-EU economic relations deteriorate further.
Agriculture: Political Flashpoint
American farmers have already borne significant costs from previous trade wars. China’s retaliatory tariffs during 2018-2019 devastated soybean exports, requiring tens of billions in federal bailouts to keep farms solvent. The EU commands smaller agricultural import volumes from the US than China, but the products at risk—pork, poultry, corn, and wheat—represent core commodities for American farm states.
European retaliation targeting agriculture would hit Republican strongholds particularly hard, potentially creating domestic political pressure on Trump to de-escalate. Yet history suggests Trump may double down rather than retreat, viewing farmer pain as acceptable cost for broader strategic objectives.
Financial Services: The Silent Killer
American banks and investment firms dominate global finance, with European operations contributing substantially to profits. ACI measures restricting US financial institutions’ access to European capital markets, or limiting their ability to serve European clients, would reshape the industry. While less visible to consumers than tariffs on consumer goods, such restrictions could reduce American GDP significantly given finance’s economic importance.
JP Morgan and other major banks have warned that Trump’s tariff escalation could trigger market instability. If European retaliation includes financial market restrictions, the consequences could extend to asset prices, credit availability, and overall financial stability.
Labor Markets: Job Losses and Structural Shifts
Employment effects of trade wars prove notoriously difficult to isolate, as job losses from tariffs often occur gradually and are obscured by broader economic trends. Yet Peterson Institute research provides sobering estimates. Analysis shows that trade-exposed sectors—durable goods manufacturing, mining, and agriculture—would experience the sharpest employment declines. Total employment might eventually return to baseline, but with permanent structural shifts from manufacturing to services at lower real wages.
For workers, this means that jobs lost in auto parts manufacturing or agricultural equipment production don’t return—they’re replaced by positions in healthcare or hospitality paying significantly less. The geographic concentration of these effects amplifies their impact: manufacturing job losses cluster in Midwest states already struggling with industrial decline, while service sector job growth concentrates in coastal cities with higher costs of living.
The political ramifications are profound. Trump’s core electoral coalition includes precisely the workers most vulnerable to trade war fallout. If economic pain intensifies in swing states like Pennsylvania, Michigan, and Wisconsin, the 2026 midterm elections could deliver harsh judgment.
Financial Markets: Volatility and Valuation Concerns
Stock markets have already reacted negatively to escalating trade tensions. On January 20, futures showed the Nasdaq 100 falling 2%, the S&P 500 declining 1.8%, and the Dow Jones retreating 1.6% as traders processed Trump’s Greenland threats and EU retaliation discussions. Bond markets reflected similar anxiety, with 30-year Treasury yields rising to 4.909% as investors demanded higher premiums for long-term US debt.
The volatility reflects fundamental uncertainty about policy direction. Corporate executives face impossible planning challenges when tariff rates fluctuate weekly and trade partnerships dissolve overnight. This uncertainty depresses business investment—why build a new factory when you don’t know whether your supply chain will exist next quarter?
For equity valuations, the calculus is straightforward: earnings projections decline as costs rise and revenues face pressure from retaliatory measures. Technology stocks, which drove much of 2025’s market gains, appear particularly vulnerable. If EU countermeasures meaningfully restrict European revenue streams for mega-cap tech companies, their valuations must adjust downward. Given these firms’ outsized weight in major indices, market-wide corrections could follow.
The dollar’s trajectory adds complexity. Deutsche Bank has warned that European asset sales—potentially liquidating $8 trillion in US holdings—could weaken the dollar significantly. A weaker dollar has mixed effects: it makes American exports more competitive but also raises import costs and could reignite inflation. For foreign investors holding dollar-denominated assets, currency depreciation compounds losses from declining asset prices.
Counterarguments: Could Tariffnomics Actually Work?
To present a balanced analysis, we must consider the case for Trump’s approach, however unconvincing mainstream economists find it.
Argument One: Negotiating Leverage
Proponents contend that tariff threats serve primarily as bargaining chips rather than permanent policy. Trump, they argue, is willing to inflict short-term economic pain to extract long-term concessions—whether in the form of reduced foreign tariffs, increased defense spending by allies, or territorial acquisitions like Greenland. Once adversaries recognize American resolve, they will capitulate, allowing Trump to declare victory and reduce tariffs.
This theory assumes rational actors on all sides and clear exit ramps from escalation. Yet Trump’s Greenland demands—asking Denmark to sell sovereign territory—appear non-negotiable from the European perspective. No conceivable concession short of territorial cession would satisfy the stated ultimatum, suggesting either that Trump is bluffing (undermining credibility) or that he’s committed to an escalatory path with no clear resolution.
Argument Two: Reshoring Benefits
Tariff advocates argue that even if trade wars inflict short-term costs, they accelerate the reshoring of manufacturing capacity essential for national security and economic resilience. By making foreign production more expensive, tariffs theoretically incentivize domestic investment in factories, supply chains, and worker training.
Evidence from Trump’s first-term tariffs provides limited support. While some reshoring occurred—particularly in steel and aluminum production—the magnitude fell far short of promised manufacturing renaissance. Studies by the Peterson Institute found that tariff-induced job gains in protected industries were more than offset by job losses in downstream sectors facing higher input costs. Global supply chains, built over decades, cannot be reconfigured quickly or cheaply.
Moreover, Europe’s retaliatory measures would work directly against reshoring objectives. If American companies lose European market access, they have less incentive to invest domestically for production ultimately barred from major export markets. The result might be investment flight rather than reshoring—companies relocating to third countries that maintain access to both American and European markets.
Argument Three: Exposing European Weakness
Some analysts suggest Trump is deliberately forcing Europe to choose between economic relationship with the United States and strategic autonomy. By demanding impossible concessions and threatening disproportionate retaliation, Trump may be testing whether European unity can withstand serious pressure. If the EU fractures—with Germany prioritizing trade access while France demands confrontation—American leverage increases.
This gambit carries enormous risks. European leaders across the political spectrum have expressed outrage at Trump’s Greenland demands, creating rare unity on an issue that transcends typical left-right divides. Rather than exploiting divisions, Trump may be inadvertently strengthening European cohesion around the principle that territorial sovereignty cannot be purchased or coerced.
Argument Four: Inflation is Manageable
Tariff proponents downplay inflationary concerns, noting that even with elevated tariffs, inflation has remained relatively moderate. They argue that global commodity price declines—particularly for energy—offset tariff effects, and that Federal Reserve competence ensures inflation expectations remain anchored.
This argument ignores composition effects and distributional consequences. While headline inflation might remain near target, that average masks significant divergence across product categories. Goods subject to tariffs have experienced sharp price increases, hitting lower-income households hardest. Research by the Tax Foundation shows that tariffs function as regressive taxes, placing disproportionate burdens on those least able to afford them.
Furthermore, Fed credibility depends partly on fiscal and trade policy sanity. If markets conclude that the administration will pursue economically destructive policies regardless of consequences, inflation expectations could become unanchored, forcing the Fed into painful tightening that triggers recession.
Global Ripple Effects: Beyond the Transatlantic Theater
The US-EU confrontation cannot be contained bilaterally. Trade war escalation inevitably spills over into broader global commerce, finance, and geopolitics.
China’s Strategic Opportunity
Beijing has watched transatlantic tensions with evident satisfaction. As the United States alienates traditional allies and fragments Western economic integration, China positions itself as a champion of stable multilateralism. Canada recently announced a “strategic partnership” with China including reduced tariffs and increased technology transfer, signaling that American allies may hedge by deepening relationships with Washington’s primary rival.
For China, a trade war between the US and EU delivers multiple benefits: reduced Western solidarity on issues like Taiwan and human rights, opportunities to capture market share that American companies lose in Europe, and validation of China’s narrative that American hegemony is unstable and unreliable. The EU and South America’s Mercosur bloc finalized a major trade agreement in 2025, reducing dependence on transatlantic commerce and creating alternative trade axes.
Emerging Market Vulnerability
Developing economies face collateral damage from great power trade wars. Higher US interest rates driven by tariff-induced inflation make dollar-denominated debt more expensive to service. Reduced global trade volumes shrink export markets for emerging economies dependent on commodity sales. Currency volatility increases as investors flee to safety.
The IMF notes that trade policy shifts are a key reason global growth is forecast to slow to 3.3% in 2026, down from pre-pandemic trends. For vulnerable nations with limited fiscal space, this slowdown could trigger debt crises, political instability, and humanitarian emergencies. The ripple effects of US-EU economic warfare extend far beyond wealthy nations capable of absorbing shocks.
Dollar Hegemony at Risk
Perhaps most consequentially, sustained trade conflict threatens the dollar’s role as global reserve currency. This status has afforded the United States tremendous economic and geopolitical advantages: the ability to borrow cheaply, sanction adversaries effectively, and maintain financial dominance. But reserve currency status rests on trust—trust that the United States will act predictably, honor commitments, and manage its economy competently.
Trump’s erratic trade policy and willingness to weaponize economic relationships against allies undermines that trust. If major economies begin diversifying away from dollar reserves—a process already underway as China promotes yuan internationalization and Europe considers digital euro alternatives—American economic hegemony slowly erodes. This shift might take years or decades, but once initiated, it becomes difficult to reverse.
Historical Lessons: Smoot-Hawley and the Perils of Protectionism
The parallels between Trump’s tariff escalation and the Smoot-Hawley Tariff Act of 1930 are impossible to ignore. That Depression-era legislation, raising tariffs on over 20,000 goods, sparked immediate retaliation from trading partners and contributed to a collapse in global commerce that exacerbated economic depression.
President Herbert Hoover signed Smoot-Hawley despite warnings from over 1,000 economists that protectionism would prove disastrous. Auto executive Henry Ford personally lobbied Hoover to veto the bill, calling it “economic stupidity.” J.P. Morgan’s chief executive Thomas Lamont said he “almost went down on [his] knees” to prevent passage. Hoover yielded to political pressure from his party and signed anyway.
The consequences were swift and severe. Canada imposed retaliatory tariffs on 16 products accounting for roughly 30% of US exports. France, Italy, Spain, and other European nations followed suit. American exports and imports both plummeted by approximately two-thirds between 1930 and 1933. While the Great Depression had broader causes, Smoot-Hawley unquestionably deepened and prolonged the economic catastrophe.
The political consequences were equally dramatic: Representative Hawley lost re-nomination, Senator Smoot lost his re-election bid, and Republicans suffered one of their worst Senate defeats in history. The debacle so discredited protectionism that for generations afterward, invoking Smoot-Hawley served as shorthand for economic policy malpractice.
Contemporary analysis reveals Trump’s tariffs may be even more economically destructive. While Smoot-Hawley raised average tariff rates by approximately 6 percentage points, Trump’s escalating tariffs have increased rates by nearly 13 percentage points—more than double the Depression-era increase. Economic historian Barry Eichengreen notes that Trump’s tariffs are “every bit as high” as Smoot-Hawley and carry similar risks of global trade collapse.
The key lesson from Smoot-Hawley is not that tariffs automatically cause depressions—the economic literature remains divided on causality. Rather, it’s that trade wars, once initiated, escalate unpredictably and inflict damage far exceeding initial estimates. Retaliation breeds counter-retaliation, supply chains fragment, and economic relationships that took decades to build can collapse in months.
Trump appears to believe he can avoid Smoot-Hawley’s fate through superior negotiating prowess. Yet Hoover likely believed the same—that trading partners would see reason, that economic pain would force concessions, that American economic power would prevail. History suggests such confidence is misplaced.
Policy Recommendations: Off-Ramps and De-Escalation
The current trajectory leads toward mutually assured economic destruction. Neither the United States nor Europe benefits from full-scale trade war, yet both appear committed to escalatory paths. Breaking the cycle requires political courage and strategic creativity currently absent from either side.
For the United States, the most obvious off-ramp involves abandoning the Greenland territorial demand. Trump might reframe the issue as successful pressure forcing Europe to increase Arctic security spending—declaring victory while quietly shelving annexation plans. This saves face while removing the immediate catalyst for EU retaliation. The challenge: Trump’s ego makes strategic retreat difficult, particularly on issues he’s emphasized publicly.
Alternatively, the administration could pursue sectoral trade deals addressing specific grievances while reducing overall tariff levels. Europe has signaled willingness to negotiate on issues like agricultural market access, regulatory harmonization, and technology standards. Comprehensive agreements take years to negotiate, but narrower deals on targeted issues could reduce tensions relatively quickly.
For Europe, the calculus involves balancing deterrence with pragmatism. Deploying the ACI demonstrates that economic coercion carries costs, potentially deterring future American threats. Yet full activation risks triggering escalation spirals difficult to reverse. A middle path might involve initiating the ACI investigation to signal seriousness while simultaneously proposing negotiated solutions.
Multilateral institutions could theoretically mediate, but Trump has systematically undermined bodies like the World Trade Organization, which lacks credibility as neutral arbiter. Perhaps summits like the upcoming Davos gathering provide informal venues for de-escalation discussions, though track records for resolving trade disputes through elite conferences remain poor.
The sobering reality is that resolution requires political will on both sides—will that appears scarce in the current environment. European elections in multiple member states through 2026 incentivize leaders to demonstrate toughness rather than compromise. American midterm elections in November create similar political constraints for Trump, who cannot appear weak to his electoral base.
The 2026 Outlook: Three Scenarios for Trade Bazooka Impact on the US Economy
As we navigate through January 2026, three plausible scenarios emerge for how EU retaliation might reshape the American economic landscape:
Scenario Alpha: Limited Engagement (30% Probability)
In this optimistic case, last-minute diplomatic efforts produce a face-saving compromise. Trump quietly shelves Greenland annexation while claiming European security commitments as victory. The EU imposes modest retaliatory tariffs on $20-30 billion worth of American goods—enough to demonstrate resolve without triggering full economic warfare. The ACI remains in reserve, unactivated but ready.
Economic Impact: US GDP growth slows to 1.8% for 2026 (down from 2.1% baseline), inflation peaks at 3.2% before declining, and equity markets experience 10-12% correction before recovering. Job losses total approximately 150,000, concentrated in agriculture and durable goods manufacturing. Financial markets stabilize once trade tensions plateau.
This scenario requires both sides to act rationally, prioritizing economic welfare over political posturing—a requirement that history suggests may be optimistic.
Scenario Beta: Graduated Escalation (50% Probability)
The most likely outcome sees Europe implementing substantial but not comprehensive retaliation. Brussels activates the ACI, imposes tariffs on the full $108 billion target list, and introduces selected restrictions on American services and investment. Trump responds with additional tariffs on European automobiles and pharmaceuticals. Neither side pursues maximum escalation, but both inflict significant economic damage.
Economic Impact: GDP growth falls to 1.3% as trade disruptions ripple through supply chains and business investment collapses. Inflation rises to 3.8% as tariff costs pass through to consumers, forcing the Federal Reserve to maintain higher interest rates longer. Equity markets decline 18-22%, with technology and industrial sectors most affected. Employment falls by 400,000-500,000 jobs, with manufacturing job losses partially offset by service sector growth. Consumer confidence plummets, weakening household spending in the second half of 2026.
The dollar initially strengthens as a safe haven but weakens substantially by year-end if European asset liquidation accelerates. Corporate earnings decline 8-12% as both revenue and margins compress. Small businesses dependent on imported components face potential bankruptcy as financing costs rise and revenue falls.
This scenario describes a serious recession that stops short of financial crisis—painful but manageable, especially for an economy entering from a position of relative strength.
Scenario Gamma: Full Economic Warfare (20% Probability)
In the darkest timeline, both sides pursue maximum damage. Europe deploys comprehensive ACI measures: tariffs on $108 billion in goods, severe restrictions on American tech companies’ European operations, exclusion from public procurement contracts, limits on financial services access, and potential sanctions on individual American executives. Trump retaliates with 100% tariffs on all European imports, restrictions on European investment in the US, and potential weaponization of dollar-clearing systems.
Economic Impact: The United States enters recession, with GDP contracting 0.5% to 1.2% for full-year 2026. Inflation spikes to 4.5-5.0% as supply chain disruptions and tariff costs compound. The Federal Reserve faces stagflation dilemma: recession argues for rate cuts, but inflation requires tightening. Equity markets enter bear market territory, declining 30-35%. Credit spreads widen dramatically as corporate default risks rise.
Employment falls by 1.2-1.5 million jobs, with unemployment rising from current 4.1% to approximately 5.5-6.0%. Consumer spending collapses as households simultaneously face higher prices, job insecurity, and declining wealth from market losses. Business investment essentially halts as uncertainty makes capital allocation impossible.
Financial stability concerns emerge if European asset sales trigger disorderly dollar decline. The Fed might be forced to intervene in currency markets or coordinate emergency liquidity measures with European central banks. The 2008 financial crisis playbook—coordinated global central bank action, fiscal stimulus, extraordinary market interventions—might be necessary to prevent economic catastrophe.
Geopolitically, this scenario damages American credibility irreparably. Allies conclude that economic relationships with the United States carry unacceptable risks, accelerating efforts to build alternative trade and financial architectures that exclude American dominance.
The Trade Bazooka Impact on the US Economy in 2026: A Reckoning Arrives
The fundamental question underlying this analysis is whether European retaliation can meaningfully damage the American economy—whether the “trade bazooka” represents legitimate threat or empty rhetoric.
The evidence strongly suggests the former. The European Union commands the world’s second-largest economy, the largest single market, and regulatory authority that shapes global standards. American companies derive enormous value from European operations: technology firms earn hundreds of billions in European revenue, financial services companies access critical European capital markets, and manufacturers depend on European components and customers.
The ACI’s comprehensive scope allows Brussels to inflict damage far exceeding conventional tariff retaliation. Excluding American technology companies from European public sector contracts alone could cost tens of billions annually. Restrictions on transatlantic data flows could fragment digital markets in ways that permanently reduce American tech dominance. Limits on financial services access could reshape global finance’s geography.
For individual Americans, the consequences manifest through higher prices, fewer job opportunities, and diminished economic security. The Tax Foundation’s research demonstrates that tariffs function as regressive taxation, hitting low- and middle-income households hardest. A full-scale trade war would amplify these distributional effects dramatically.
The timing compounds the challenge. The American economy has demonstrated remarkable resilience through 2025, but sustained trade war would test that resilience severely. Consumer spending—which drives roughly 70% of GDP—depends on household confidence that jobs remain secure and real incomes continue growing. Trade war erosion of both employment and purchasing power could trigger self-reinforcing contractionary dynamics.
Stock markets provide real-time assessment of trade war damage. The January 20 market decline, with the Nasdaq falling 2% on EU retaliation news, suggests investors take the threat seriously. If corporate earnings projections decline substantially due to lost European access, equity valuations must adjust. For retirement accounts heavily weighted toward stocks, these adjustments translate directly into household wealth destruction.
The dollar’s trajectory under trade war conditions remains uncertain. Traditional safe-haven dynamics might initially strengthen the currency, but European asset liquidation of potentially $8 trillion in US holdings—as Deutsche Bank has warned—would exert enormous downward pressure. Currency volatility adds another layer of uncertainty to business planning already paralyzed by trade policy unpredictability.
Conclusion: Economic Nationalism Meets Economic Reality
The Greenland standoff has crystallized fundamental tensions in early 21st-century global governance. Can nations with nuclear weapons and enormous economies subordinate short-term political objectives to long-term economic welfare? Can alliances built over seven decades survive leaders who view partnerships transactionally? Can economic interdependence prevent conflict when political actors actively seek confrontation?
The answers emerging from January 2026 are not encouraging. Trump’s tariffnomics represents a deliberate rejection of the liberal international order that American policymakers constructed after World War II. By weaponizing trade against allies, demanding territorial concessions, and dismissing economic costs as acceptable collateral damage, the administration has signaled that no norm, commitment, or relationship enjoys immunity from sacrifice.
Europe’s impending decision on whether to deploy the trade bazooka will largely determine how severely these tensions damage the American economy. If Brussels chooses comprehensive retaliation, the United States will experience economic consequences more severe than any policy-induced shock since the 2008 financial crisis. Supply chains will fragment, industries will contract, jobs will disappear, and household living standards will decline.
Yet even modest European retaliation carries substantial risks. The trade war psychology—where each side’s response seems justified to itself but appears escalatory to opponents—creates dynamics difficult to control once unleashed. Economic warfare, like military conflict, tends toward escalation rather than de-escalation. First-move advantages incentivize pre-emptive strikes; retaliatory pride prevents backing down; domestic constituencies demand victories that negotiated settlements rarely deliver.
The supreme irony is that Trump’s objective—strengthening American economic power through tariffs—will likely achieve the opposite. By alienating allies, fragmenting markets, and undermining the institutional architecture that magnifies American influence, tariffnomics may accelerate precisely the relative American decline it purports to arrest. China’s strategic patience, Europe’s growing autonomy, and emerging economies’ diversification away from dollar dependence all benefit from American economic self-isolation.
For American businesses, workers, and families, the coming months will test resilience in ways unexpected at the start of 2026. Economic forecasts released just weeks ago assumed relative stability; that assumption now appears dangerously optimistic. The trade bazooka’s destructive potential is real, and European leaders appear increasingly willing to pull the trigger.
Perhaps last-minute diplomacy will produce off-ramps from full-scale economic warfare. Perhaps cooler heads will prevail, recognizing that mutually assured destruction makes poor policy regardless of political considerations. Perhaps domestic political constraints will force both sides toward compromise before damage becomes catastrophic.
But perhaps not. The lesson of Smoot-Hawley—that protectionism, once embraced, escalates unpredictably—suggests caution about optimistic scenarios. The historical record shows that economic nationalism, given sufficient political support, can override economic rationality for years at immense cost.
As European officials gather in Brussels to debate ACI activation and American officials double down on tariff threats, the world watches to see whether 2026 will be remembered as the year when economic interdependence finally prevented great power conflict—or as the year when great powers demonstrated that interdependence cannot constrain ambition.
For the American economy, the stakes could hardly be higher. The trade bazooka is loaded, aimed, and ready to fire. Whether it gets deployed depends on decisions made in the coming weeks by leaders in Brussels and Washington. One can only hope they choose wisely, though recent evidence provides little reassurance.
The Arctic wind still blows cold across Greenland, and the economic chill threatening transatlantic relations shows no signs of thawing. The question is no longer whether the EU’s retaliatory powers can reshape the US economy in 2026—it’s how severely, and whether American policymakers will recognize the damage before it becomes irreversible.
There is a moment in every genuine geopolitical crisis when financial markets stop pretending they are merely reacting to data and begin reckoning with something more elemental: fear. That moment arrived on the morning of Saturday, February 28, 2026, when the United States and Israel launched coordinated strikes on Iran—killing Supreme Leader Ayatollah Ali Khamenei and igniting the most consequential military conflict in the Middle East in a generation. By Monday morning in New York, the world’s trading floors were measuring the aftershocks in barrels, basis points, and bullion.
What began as a targeted military operation has rapidly evolved into a multi-front conflict with cascading implications for energy markets, global supply chains, and the architecture of international finance. For investors, policymakers, and ordinary citizens watching the price of petrol rise at the pump, the central question is no longer whether markets will feel the US-Iran conflict market impact—they already are. The real question is how deep, how prolonged, and who ultimately bears the cost.
Immediate Market Reactions: Risk-Off in Real Time
The financial system’s first verdict was swift and largely predictable in its direction if not its magnitude. Stocks fell and the dollar climbed as military strikes intensified across the Middle East, sending oil to its biggest surge in four years while stoking concern that inflation will accelerate. Gold briefly topped $5,400. The S&P 500 dropped 1.1%, following losses in Europe and Asia. Airlines and cruise operators sank while energy and defense shares jumped. Bloomberg
By Monday’s open, the damage had spread more broadly. The Dow Jones Industrial Average dropped 282 points, or 0.6%. The S&P 500 lost 0.5%, and the Nasdaq Composite declined 0.4%—though the three major averages rallied off session lows as gains in technology stocks helped trim losses. At their nadir, the Dow was down about 600 points, or 1.2%. CNBC The CBOE Volatility Index—Wall Street’s so-called “fear gauge”—jumped to its highest level of 2026.
The bond market offered a counterintuitive signal. The 10-year Treasury yield was little changed Monday at 3.97%, regaining some ground after falling to an 11-month low of 3.926% on Friday. CNBC That modest move suggested bond traders are torn between two forces: a flight-to-safety impulse pulling yields lower, and an inflation anxiety—driven by soaring oil—pushing them back up. As an analyst, I’ve observed this precise tension before in conflict-driven crises: the bond market’s internal debate often telegraphs how long-lasting the disruption will prove to be.
The Strait of Hormuz: The World’s Most Expensive Bottleneck
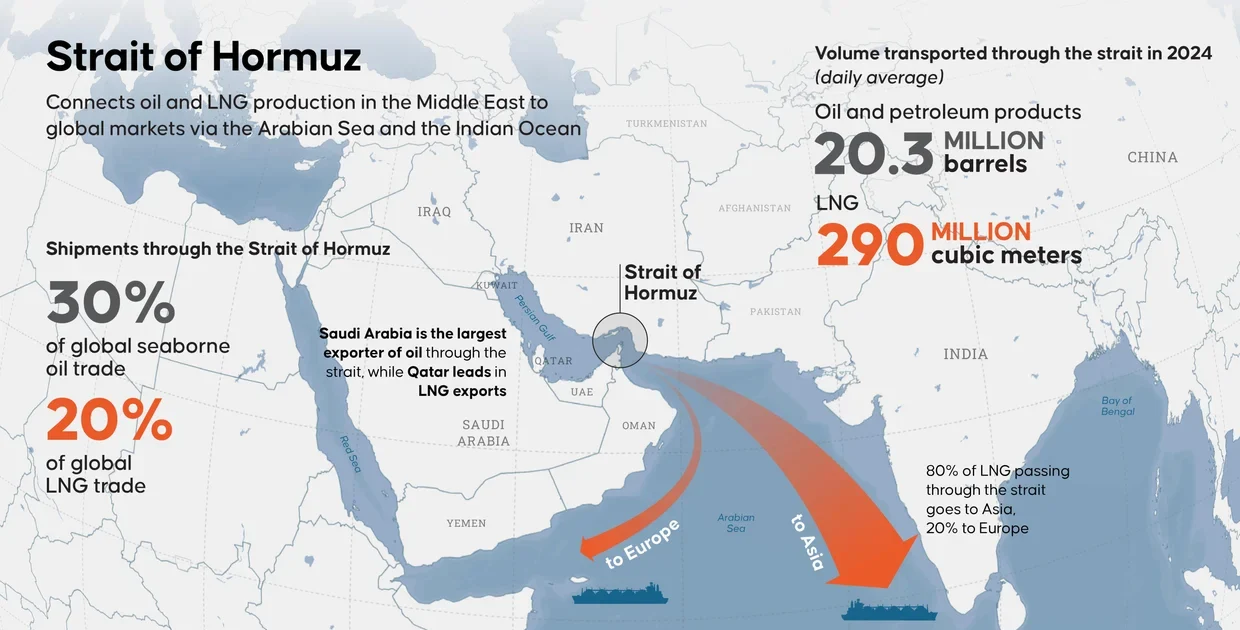
No single geographic feature looms larger over the geopolitical risks oil prices calculation than the Strait of Hormuz. This narrow waterway between Iran and Oman is, in the words of one analyst, not a “production story” but a “chokepoint story”—and chokepoints, when threatened, carry systemic implications that dwarf any single country’s output.
More than 14 million barrels per day flowed through the Strait in 2025, or roughly a third of the world’s total seaborne crude exports. About three-quarters of those barrels went to China, India, Japan and South Korea. China, the world’s second-largest economy, receives half of its crude imports through the Strait. CNBC Iran has threatened to close this waterway entirely.
About 13 million barrels per day of crude oil transited the Strait of Hormuz in 2025, accounting for roughly 31% of global seaborne crude flows, according to market intelligence firm Kpler. CNBC Container shipping giants have already responded: Maersk announced it would suspend all vessel crossings in the Strait of Hormuz until further notice, warning that services calling ports in the Arabian Gulf may experience delays. CNBC
Amrita Sen, founder of Energy Aspects, told CNBC that oil markets are likely to hold around $80 a barrel for now after an initial spike, noting stabilization, but warned that “what the U.S. will not be able to do is control these one-off attacks on tankers.” CNBC The insurance industry is already pricing in the risk: marine hull insurance in the Gulf could rise by 25 to 50 percent in the near term, according to Dylan Mortimer, marine hull UK war leader at insurance broker Marsh. CNBC Those premiums ultimately flow through to the cost of every barrel, and every barrel’s cost flows through to every economy on earth.
Sector-Specific Impacts: Winners, Losers, and the Middle Ground
The Iran tensions global economy shock has not distributed its pain—or its windfalls—evenly across sectors. The divergence is stark.
Energy and Defense: The Reluctant Beneficiaries
Several oil stocks surged following the strikes on fears the conflict could disrupt global crude production and transport. Exxon Mobil and Chevron shares gained about 4%, while ConocoPhillips was also up more than 5%. Brent crude prices hit a new 52-week high of more than $78 on Monday. CNBC Defense contractors followed suit: Lockheed Martin shares gained 6%, while Northrop Grumman was up 5%, and drone maker AeroVironment jumped more than 10%. CNBC
Travel and Hospitality: The Immediate Casualties
Travel-related stocks dropped sharply. United Airlines, most exposed to international travel of the US carriers, tumbled more than 6%. American and Delta each fell more than 5%. Marriott International slid nearly 5%, while Airbnb sank more than 3%. Online reservation platforms Expedia and Booking Holdings slid more than 4% and 3% respectively. CNBC
The human toll on aviation has been immediate. Airlines canceled thousands of flights for the week in the Middle East, with 1,560 flights scrubbed on Monday alone, or 41.28% of those scheduled for arrival in Middle East countries, according to aviation data firm Cirium. Hundreds of thousands of passengers remain stranded. CNBC
Safe-Haven Assets: Gold’s Gravity-Defying Run
Gold’s ascent has been the defining market narrative of this crisis. Gold rallied above $5,300 per ounce, hitting record highs as investors moved into safe-haven assets. JP Morgan has raised its gold price target to $6,300 per ounce by December 2026, reflecting analyst confidence that this isn’t just a temporary spike. INDmoney Precious metals and the US dollar are now functioning as the twin shock absorbers of the global financial system.
Long-Term Risks: Inflation, Fragmentation, and the Asian Dimension
Beyond the immediate volatility lies a more structurally dangerous set of pressures. Elevated oil prices, if sustained, function as a regressive global tax—hitting emerging markets, commodity-importing nations, and lower-income households hardest.
Standard Chartered’s Global Head of Research Eric Robertsen noted that investors had already been underpricing geopolitical risk, with commodity-linked currencies outperforming, suggesting markets are paying for exposure to scarce resources and terms-of-trade winners. CNBC
The implications for Asia—the region most dependent on Hormuz-transiting oil—are severe and underappreciated by Western financial commentary. China, Japan, South Korea, and India collectively import the vast majority of their crude through this corridor. Any sustained disruption would accelerate inflationary pressures across Asian manufacturing economies, potentially stalling the global export recovery that policymakers have counted on.
There is also the geopolitical fracture dimension. China and Russia have condemned the US-Israeli strikes. In a phone call with his Russian counterpart, Chinese Foreign Minister Wang Yi said it was “unacceptable for the US and Israel to launch attacks against Iran.” CNBC This fracture carries long-term implications for dollar-denominated trade systems, multilateral institutions, and the cohesion of any post-conflict reconstruction framework.
The scenario analysis from Wells Fargo is instructive. Their strategists mapped out scenarios ranging from quick de-escalation to a worst-case prolonged Hormuz closure: in their worst-case scenario, the S&P 500 could drop to 6,000 from current levels around 6,850, but their base case still targets 7,500 by year-end. INDmoney The range of that spread—nearly 25%—is itself a measure of how genuinely uncertain the endgame remains.
The Diplomatic Paradox: War Launched During Talks
Perhaps the most jarring dimension of this crisis is the diplomatic context in which it erupted. The UN Secretary-General noted that the joint military operation by Israel and the United States occurred following indirect talks between the US and Iran mediated by Oman, “squandering an opportunity for diplomacy.” UN News
Although the last round of talks ended Thursday with Iran agreeing to “never” stockpile enriched uranium, that was not enough to avert US military action. CNN Markets loathe uncertainty, but they despise diplomatic incoherence even more—because it removes the scaffolding of predictable resolution. The absence of a clear off-ramp is precisely what is keeping risk premiums elevated across asset classes.
President Trump has suggested the conflict could last four weeks, and separately told The Atlantic that Iran’s new leadership wants to resume negotiations. Trump said Iran’s new leadership wanted to resume negotiations and that he has agreed to talk to them, saying “They want to talk, and I have agreed to talk.” CNBC Markets will be parsing every diplomatic signal for evidence of de-escalation—any credible ceasefire announcement would likely trigger a sharp oil selloff and equity recovery.
Investor Implications and Strategic Considerations
For portfolio managers navigating Middle East conflict investment strategies, several principles apply in this environment.
Overweight energy and defense selectively. The oil price tailwind for integrated majors and defense contractors is real, but entry points matter. Much of the initial upside is already priced in.
Reduce exposure to aviation, hospitality, and emerging-market importers. Nations like India, South Korea, and Japan face disproportionate energy import cost pressures, which will compress corporate margins and strain current accounts.
Monitor the Strait obsessively. David Roche of Quantum Strategy framed the market impact in terms of duration and whether Iran would attempt to close the Strait of Hormuz—if the conflict is short and contained, the risk-off move and oil spike could be brief; if it turns into a three-to-five-week regime change endeavor, markets would react “rather badly.” CNBC
Gold remains the structural hedge. With JP Morgan targeting $6,300 by year-end and central bank demand for bullion already at historical highs entering 2026, gold’s role as the geopolitical insurance policy of last resort appears set to deepen.
Conclusion: A Conflict That Will Rewrite Risk Premiums
The US-Iran conflict of February-March 2026 is not merely another geopolitical flare-up to be absorbed and forgotten within a trading week. The assassination of Khamenei, the direct involvement of US military forces, the threatened closure of the world’s most critical energy chokepoint, and the fissure it has opened between Western and non-Western powers collectively represent a structural inflection point for global markets.
In the short term, monitor Brent crude and the CBOE VIX daily as the conflict’s most sensitive barometers. In the medium term, watch whether Iran’s successor leadership follows through on negotiation signals or opts for prolonged asymmetric warfare against Gulf infrastructure. In the long term, consider how this crisis accelerates the already-underway energy transition: every $10 increase in sustainable oil prices makes renewable alternatives marginally more competitive, nudging capital allocation toward green infrastructure.
Conflict is never an opportunity to celebrate. But history teaches that periods of maximum geopolitical uncertainty are also when the contours of the next financial order begin to take shape—quietly, beneath the noise of war. The investors and institutions who read those contours correctly today will be better positioned for the world that emerges when the smoke clears over Tehran.

On a crisp January morning in Davos, as global elites gathered for their annual ritual of discussing “collaboration” and “shared prosperity,” Canadian Prime Minister Mark Carney delivered a speech that felt less like diplomacy and more like a eulogy. “We are in the midst of a rupture, not a transition,” he declared, warning that great powers now wield economic integration as weapons and tariffs as leverage. What made Carney’s address so striking wasn’t merely its candor about the death of the rules-based international order—it was the unspoken target of his critique. Though he never mentioned Donald Trump by name, everyone understood: the gravedigger of the post-1945 system isn’t primarily Beijing or Moscow. It’s Washington.
The irony is as sharp as it is unsettling. For eight decades, the United States positioned itself as the architect and guarantor of a liberal international order predicated on sovereignty, multilateral cooperation, and the peaceful resolution of disputes. Today, under Trump’s second administration, America is accelerating that order’s collapse with a ferocity that makes Russia’s revisionism look almost modest by comparison. The evidence is mounting: Trump Greenland national security threats that echo Putin’s Ukraine rationale, withdrawal from 66 international organizations, and an explicit rejection of international law itself. The world’s erstwhile hegemon isn’t pivoting—it’s demolishing its own creation.
Trump Greenland National Security: A Familiar Playbook
In late January 2026, President Trump declared that acquiring Greenland was “imperative for national and world security,” repeatedly refusing to rule out military force to seize the Danish autonomous territory. The White House press secretary confirmed that “utilizing the U.S. Military is always an option” in pursuing what Trump frames as a vital strategic objective. His justification? Greenland’s Arctic position makes it essential to defend against Russian and Chinese encroachment. Never mind that the United States already maintains a significant military presence at Pituffik Space Base under a 1951 agreement with Denmark, or that Denmark is a NATO ally bound by mutual defense commitments. Trump’s push for Greenland represents a territorial ambition dressed in the language of security—a rationale that should sound disturbingly familiar.
When Vladimir Putin ordered Russian forces into Ukraine in February 2022, he invoked strikingly similar logic. He framed the invasion as a preventive war necessitated by NATO expansion and Ukraine’s growing military cooperation with the West, which he characterized as an existential threat to Russian security. Putin claimed he was conducting a “special military operation to protect the people in the Donbas,” portraying Russia’s aggression as defensive action against Western provocations. The parallels to Trump’s Greenland rhetoric are unmistakable: both leaders invoke national security imperatives to justify territorial expansion, both dismiss the sovereignty of smaller nations as subordinate to great-power interests, and both signal willingness to use military force if diplomacy fails to deliver the desired result.
The structural similarity goes deeper than rhetoric. As scholars analyzing Putin’s preventive war logic have noted, Moscow genuinely feared that Ukraine’s westward drift would shift the balance of power irreversibly against Russia. Trump’s national security advisor reportedly framed Greenland in precisely these terms: critical minerals vital for emerging technologies and national security applications, combined with strategic positioning against peer competitors. Both cases reveal how great powers invoke security to legitimize what earlier eras would have simply called conquest. The Trump administration’s approach differs from Putin’s primarily in degree and presentation—Trump at Davos eventually backed away from tariff threats and pledged not to use force, though his broader posture suggests these were tactical retreats rather than strategic shifts.
Post-American Era: Economic Weaponization and the New Reality
Mark Carney’s Davos speech articulated what allies have whispered privately for years: the post-American era has arrived, and it arrived with American complicity. Drawing on Václav Havel’s essay on life under Soviet totalitarianism, Carney argued that middle powers had long placed metaphorical signs in their windows—participating in the rituals of the rules-based order while politely ignoring the gap between American rhetoric and reality. That bargain no longer works because great powers have begun using economic integration as weapons, tariffs as leverage, financial infrastructure as coercion, and supply chains as vulnerabilities to be exploited.
The economic weaponization Carney describes isn’t hypothetical. Trump has threatened 25% tariffs on European goods unless Denmark cedes Greenland, withdrawn from dozens of international organizations, and explicitly stated in a New York Times interview: “I don’t need international law.” These actions represent a systematic dismantling of the institutional architecture that Washington itself constructed after 1945. When the United States freezes all foreign assistance, blocks judges at the International Criminal Court with sanctions, and contemplates military seizure of allied territory, it’s not reforming the liberal international order—it’s demolishing it.
What distinguishes American norm erosion from Chinese or Russian revisionism is its devastating effect on the order’s legitimacy. Beijing and Moscow have long been external challengers, states that never fully bought into liberal principles and therefore were always viewed with suspicion by the system’s defenders. But when the United States—the order’s founding architect, military guarantor, and self-proclaimed exemplar—abandons multilateralism for transactionalism and sovereignty for spheres of influence, it removes the keystone from the entire edifice. As observers at Chatham House note, Trump’s assertion that he personally determines when the United States should comply with rules that bind others represents a fundamental repudiation of the reciprocity on which international law depends.
Trump Greenland Putin Ukraine Parallels: Great Powers Unchained
The parallels between Trump’s Greenland ambitions and Putin’s Ukraine invasion illuminate a broader pattern: the return of great-power politics unmoored from international legal constraints. Both leaders frame territorial expansion as defensive necessity, both invoke the language of security to mask strategic opportunism, and both signal contempt for the sovereignty of smaller neighbors. Yet the comparison also reveals asymmetries that make the American case more corrosive to global order.
Putin’s Russia, while destabilizing and aggressive, operates largely as expected from a revanchist power still nursing post-Cold War grievances. Moscow’s invasion of Ukraine, though catastrophic, surprised few serious analysts of Russian strategic culture. The Kremlin has consistently prioritized spheres of influence over sovereign equality, and its use of force, while illegal and brutal, aligns with historical patterns of Russian imperial behavior. International reaction to the Ukraine invasion—sanctions, isolation, unified NATO response—demonstrated that the international community still recognizes and punishes brazen violations of territorial integrity, even when committed by a nuclear-armed permanent Security Council member.
Trump’s America, by contrast, represents something more dangerous: the defection of the system’s hegemon. When the United States threatens military action against Greenland while simultaneously positioning itself as a defender of peace, when it withdraws from multilateral frameworks while demanding allies shoulder greater security burdens, it doesn’t just violate norms—it delegitimizes them. The hypocrisy is the point. By demonstrating that rules apply selectively based on power rather than principle, Washington validates every revisionist power’s cynicism about the liberal international order. Why should China respect freedom of navigation in the South China Sea when America threatens to seize Arctic territory from a NATO ally? Why should Russia accept Ukraine’s sovereignty when the United States disregards Greenland’s self-determination?
Three critical distinctions separate Trump’s approach from Putin’s and make it more systemically corrosive:
Institutional destruction vs. institutional evasion. Russia works around or against international institutions; America is actively dismantling them from within. Moscow violated the UN Charter by invading Ukraine, but it didn’t withdraw from the United Nations or sanction the International Court of Justice. Trump has done both equivalents, leaving a trail of abandoned treaties and defunded organizations.
Alliance betrayal vs. alliance expansion. Putin’s aggression strengthened NATO cohesion and prompted Finland and Sweden to join the alliance. Trump’s threats against Greenland have fractured transatlantic unity and raised existential questions about Article 5 guarantees. When a Democratic Senator observes that NATO countries might need to defend Greenland “against the U.S. if necessary,” the alliance’s foundational logic has collapsed.
Normative leadership vs. normative destruction. Russia never claimed to champion a rules-based order; its revisionism involves no ideological betrayal. America’s abandonment of principles it once preached—sovereignty, peaceful resolution of disputes, multilateral cooperation—represents a betrayal that undermines those principles’ global legitimacy. As analysis from the Carnegie Endowment notes, Trump’s policies signal a shift from American leadership of a liberal order to America operating as just one great power in a post-Western world.
US Undermining World Order: The Venezuela Test Case
If Trump’s Greenland threats represented rhetorical escalation, the January 2026 military operation in Venezuela provided brutal proof of concept. U.S. forces abducted Venezuelan President Nicolás Maduro and his wife in a large-scale raid on Caracas, with Trump declaring the United States would “run” Venezuela and was “not afraid of boots on the ground.” The operation violated every principle of sovereignty, non-intervention, and peaceful dispute resolution enshrined in the UN Charter—principles the United States spent decades promoting as universal norms.
The Venezuela intervention accelerated Trump’s Greenland campaign precisely because it demonstrated that consequences for American lawlessness remain minimal. International condemnation came, predictably, from South America and the Global South. But the muted response from European allies—whose own security depends on American credibility—revealed how thoroughly Trump has inverted the traditional logic of alliances. Rather than America’s allies constraining its behavior through institutional commitments and shared values, Trump has weaponized alliance dependence to extract concessions and silence criticism. When Denmark responded to Greenland threats by deploying elite troops to the territory, Trump threatened tariffs. When those tariffs materialized, European unity fractured.
This is economic coercion masquerading as alliance management, and it represents a profound departure from postwar American statecraft. Previous administrations occasionally pressured allies on defense spending or trade disputes, but they operated within an accepted framework of reciprocal obligations and institutional constraints. Trump has discarded that framework entirely, replacing it with a transactional model where America’s overwhelming power—military, economic, financial—becomes a cudgel for extracting unilateral advantage. The rules-based order assumed that power would be self-limiting, channeled through institutions and constrained by enlightened self-interest. Trump’s foreign policy demonstrates that assumption was always fragile.
Decline of Liberal International Order: Middle Powers and Adaptation
Carney’s speech represented more than elegant critique—it outlined a survival strategy for what he termed “middle powers” navigating the wreckage of American-led order. His prescription: stop invoking the “rules-based international order” as though it still functions as advertised, acknowledge that great powers now pursue unhindered power and interests, and build coalitions among less powerful states to create “a third path with impact.”
This vision of middle-power resilience through collective action offers both hope and warning. Hope, because it suggests the complete collapse into great-power spheres of influence isn’t inevitable—that states between the giants retain agency if they coordinate effectively. Warning, because it implicitly concedes that the universal rules-based order is dead, replaced by a more fragmented, regionalized system where justice and security depend on coalition strength rather than law.
Canada’s response under Carney illustrates this adaptation in practice. Within months of taking office, he signed trade and security agreements across four continents, doubled defense spending, and positioned Canada as a champion of the multilateral system that Washington is abandoning. Other middle powers are following similar playbooks. European nations are accelerating integration and boosting military capacity, recognizing they can no longer outsource security to an increasingly unreliable America. ASEAN states are diversifying partnerships, hedging between Washington and Beijing rather than betting exclusively on either. Even traditional American allies like South Korea and Japan are exploring greater strategic autonomy.
Yet this proliferation of hedging strategies and defensive regionalisms carries its own risks. A world organized around competing regional blocs and ad hoc coalitions may prove more stable than unconstrained great-power rivalry, but it represents a significant step backward from the aspirations of 1945. The postwar order, for all its flaws and hypocrisies, at least established the principle that international law should constrain power—that might shouldn’t automatically make right. When middle powers abandon appeals to universal norms in favor of balance-of-power politics, they validate the very great-power cynicism that necessitated their adaptation.
Rules-Based Order Collapse: The Path Forward
The uncomfortable truth that Carney articulated and Trump embodies is that nostalgia offers no strategy. The liberal international order that emerged from World War II—multilateral institutions, free trade, collective security, democratic solidarity—was always more aspiration than reality, particularly for those outside the Western security community. Its genuine achievements, from unprecedented economic growth to the avoidance of great-power war, coexisted with profound inequalities, selective application of rules, and a persistent gap between universalist rhetoric and particularist practice.
What made the system workable wasn’t perfection but American willingness to embed its hegemony within institutional constraints that at least gestured toward reciprocity and legitimacy. When Washington championed the WTO even when rulings went against it, when it built coalitions rather than dictating terms, when it defended smaller allies’ sovereignty even at cost to short-term interests, it sustained the fiction that rules could constrain power. Trump has shattered that fiction with remarkable efficiency.
The consequences extend far beyond Greenland or Venezuela. Every authoritarian regime now possesses a ready-made justification for territorial ambitions: “If America can threaten to seize allied territory for national security reasons, why can’t we?” Every middle power calculating its security posture must now account for the possibility that American protection is conditional, transactional, and reversible. Every international institution confronts an existential question: what purpose do rules serve when the most powerful player explicitly rejects their authority?
Three scenarios appear plausible for the international system’s evolution:
Fragmented regionalism: The current trajectory, where overlapping regional orders—European integration, Asian hedging, Western Hemisphere proximity to American power—replace the aspiration of universal rules. This is Carney’s “third path,” potentially more stable than pure great-power rivalry but far less protective of smaller states’ sovereignty and far less conducive to addressing global challenges like climate change or pandemic response.
Spheres of influence: Trump’s apparent preference, where great powers divide the world into exclusive zones and police their peripheries without interference. This arrangement might reduce great-power conflict through mutual recognition, but it would formalize the subordination of smaller states and legitimize territorial expansion for security reasons—essentially returning to 19th-century concert politics with 21st-century technology.
System collapse into conflict: The nightmare scenario, where the erosion of institutional restraints and proliferation of territorial grievances creates cascading crises that overwhelm great powers’ capacity for management. This is the path that led from the Congress of Vienna’s breakdown to World War I, and while nuclear weapons change the calculus, they don’t eliminate the risk of miscalculation and escalation.
None of these futures resembles the liberal international order’s promise. None offers the combination of sovereignty protection, economic openness, and collective security that defined postwar aspirations. And crucially, the United States isn’t drifting into these scenarios through inattention or incompetence—it’s actively accelerating toward them through deliberate policy choices that prioritize short-term advantage over long-term stability.
The Greengrocer’s Sign: Legitimacy and the Future
Carney’s invocation of Havel’s greengrocer serves as this moment’s most potent metaphor. For decades, allies participated in rituals celebrating the rules-based order even as they privately recognized its imperfections and hypocrisies. They placed the sign in the window—”Workers of the world, unite” or “Sovereignty matters” or “International law binds us all”—not out of conviction but to avoid trouble, signal compliance, and preserve the system’s veneer of legitimacy.
Trump has removed America’s sign. By explicitly stating “I don’t need international law,” by threatening force against allies, by withdrawing from institutions and agreements, he’s acknowledged what cynics always suspected: that American support for the liberal order was conditional on American advantage, and when that calculus shifted, the principles would be abandoned.
The question now is whether other powers will follow America’s example and remove their own signs, embracing naked interest and power politics, or whether they’ll attempt to sustain some version of rules-based order without American leadership. Early evidence suggests a mixture: some states, particularly in the Global South, are invoking international law more vigorously now that Washington has abandoned it, seeing an opportunity to constrain great powers through collective legal action. Others are pursuing the hedging strategies Carney advocates, building resilience through diversification rather than relying on rules.
What seems increasingly unlikely is a return to the comfortable fiction of the past seven decades—that a benign American hegemon would voluntarily constrain its power through institutional commitments and provide global public goods while asking relatively little in return. That fiction required American buy-in, and Trump has made clear that at least one major faction of American politics views it as a sucker’s bargain. Even if a future administration attempts to restore elements of liberal internationalism, allies will remember 2025-2026 and hedge accordingly.
The great tragedy of Trump’s Greenland obsession and broader assault on international order isn’t that it reveals American hypocrisy—serious observers always knew the gap between principle and practice. The tragedy is that it destroys whatever practical value that hypocrisy once served. When America claimed to support sovereignty while occasionally violating it, at least smaller states could appeal to those stated principles as leverage. When America framed alliances as partnerships rather than protection rackets, at least allies could assume some baseline of reliable commitments. Trump has stripped away the hypocrisy and left only the power politics beneath.
In doing so, he hasn’t made America weaker—the United States remains overwhelmingly powerful militarily and economically. But he has made the world more dangerous, more fragmented, and less capable of addressing collective challenges. And he has ensured that when historians write the story of the liberal international order’s collapse, they will identify not Beijing or Moscow as the primary accelerant, but Washington. The United States, having led the West in building an international order after 1945, now leads it in tearing that order down.
Carney’s warning deserves the final word: “The old order is not coming back. We should not mourn it. Nostalgia is not a strategy. But from the fracture, we can build something better, stronger and more just.” Whether middle powers can actually construct that better order while great powers pursue unhindered ambitions remains the decade’s defining question. But one thing is certain: they’ll be building it without the United States—or more precisely, despite the United States.
Trump files $5B lawsuit against JPMorgan and CEO Jamie Dimon over alleged political debanking after Jan. 6. Inside the explosive legal battle reshaping Wall Street.
The Lawsuit That Could Redefine Banking’s Political Boundaries
On a crisp January morning in 2026, Donald Trump—now barely two weeks into his second presidency—fired what may prove to be one of the most consequential legal salvos against Wall Street in modern American history. The $5 billion lawsuit, filed in Florida state court on January 22, targets not only JPMorgan Chase, America’s largest bank, but also its formidable CEO Jamie Dimon, alleging “political debanking” in the aftermath of the January 6, 2021 Capitol riot.
The complaint centers on a stark allegation: that JPMorgan, under Dimon’s leadership, closed Trump’s personal and business accounts in February 2021 not for legitimate compliance reasons, but as political retaliation. According to The New York Times, the lawsuit characterizes the bank’s actions as a “coordinated effort to weaponize financial access against political opponents,” invoking Florida’s recently enacted anti-debanking statute to claim unprecedented damages.
The timing is extraordinary. Trump returns to the Oval Office with an ambitious agenda of financial deregulation and tariff restructuring, yet immediately finds himself in open warfare with the very institution that once helped finance his real estate empire. For Jamie Dimon—often described as the most powerful banker in America—the lawsuit represents an uncomfortable collision between his role as a nonpartisan financial steward and the increasingly politicized landscape of corporate America.
This case transcends a dispute between a former president and his banker. It strikes at fundamental questions about the boundaries of corporate power, the role of banks as gatekeepers to the financial system, and whether access to banking can—or should—be conditioned on political considerations. The reverberations will be felt far beyond Palm Beach and Manhattan.
The Fracture: From Business Partners to Courtroom Adversaries
The Pre-2021 Relationship
The relationship between Donald Trump and JPMorgan Chase was never warm, but it was functional. Throughout the 2000s and 2010s, JPMorgan maintained various banking relationships with Trump Organization entities, though the bank had reportedly scaled back its exposure following Trump’s 1990s casino bankruptcies. Unlike Deutsche Bank, which became Trump’s primary lender during years when major Wall Street institutions avoided him, JPMorgan maintained a cautious but present role—managing accounts, processing transactions, facilitating international transfers for his global properties.
Jamie Dimon, for his part, navigated the Trump presidency with characteristic pragmatism. The JPMorgan CEO publicly supported aspects of Trump’s 2017 tax reform, attended White House business councils, and maintained cordial relations even as he occasionally criticized specific policies. It was classic Dimon: engage with power, advocate for business interests, avoid unnecessary confrontation.
The January 6 Turning Point
Then came January 6, 2021. As rioters stormed the Capitol and the nation reeled, corporate America faced a reckoning. According to The Washington Post, JPMorgan’s risk management and compliance teams initiated an urgent review of all Trump-related accounts in the riot’s immediate aftermath. The bank’s concerns reportedly centered on three factors: reputational risk, regulatory scrutiny, and potential exposure to sanctions or legal complications given ongoing investigations into the events of that day.
By February 2021, JPMorgan had made its decision. In a series of terse notifications—described in the lawsuit as “cold and peremptory”—the bank informed Trump and several affiliated entities that their accounts would be closed within 30 days. No detailed explanation was provided beyond boilerplate language about “business decisions” and “risk tolerance.”
Trump, then a private citizen banned from major social media platforms and facing his second impeachment, had few immediate options for recourse. But he evidently did not forget.
Inside the Lawsuit: Claims, Legal Strategy, and the Florida Debanking Law
The Core Allegations
The 87-page complaint, filed in Palm Beach County Circuit Court, makes sweeping allegations of political discrimination and viewpoint-based financial censorship. Bloomberg reports that Trump’s legal team argues JPMorgan violated Florida Statutes Section 542.336, a law enacted in 2023 that prohibits financial institutions operating in the state from denying services based on political views, religious beliefs, or social credit scores.
The lawsuit claims that JPMorgan’s decision was “pretextual and politically motivated,” pointing to several pieces of circumstantial evidence:
- Timing: The account closures came mere weeks after January 6, suggesting a direct causal link.
- Selective application: The complaint alleges other high-profile clients with controversial political profiles or legal troubles maintained their JPMorgan accounts.
- Lack of explanation: JPMorgan allegedly refused to provide substantive justification beyond generic risk management language.
- Public statements: The lawsuit references internal communications and public comments by JPMorgan executives about corporate responsibility and ESG commitments following January 6.
The $5 Billion Question
The astronomical damages figure—$5 billion—is based on claims of reputational harm, business disruption, and punitive damages. Trump’s attorneys argue that being “debanked” by America’s largest financial institution inflicted severe damage on his business empire, complicating transactions, raising costs, and signaling to other institutions that he was an unacceptable client. Forbes notes that the complaint specifically cites lost opportunities, increased borrowing costs, and the “digital scarlet letter” of being rejected by JPMorgan.
Legal experts interviewed by multiple outlets express skepticism about the damages calculation, noting that proving direct financial harm from account closures—particularly for someone with Trump’s access to alternative banking options—will be extraordinarily difficult. Yet the symbolic value of the number is clear: this is warfare, not negotiation.
Jamie Dimon in the Crosshairs: Personal Liability and Corporate Leadership
Why Sue Dimon Personally?
The inclusion of Jamie Dimon as an individual defendant elevates this from a routine corporate dispute to something far more personal. The Financial Times reports that Trump’s complaint alleges Dimon was directly involved in the decision to close the accounts, citing board meeting minutes and internal communications that purportedly show the CEO weighing in on Trump-related risk management decisions in early 2021.
This is unusual. CEOs of major banks typically insulate themselves from individual account decisions through layers of compliance, legal, and risk management infrastructure. Piercing that corporate veil requires demonstrating that Dimon personally directed or ratified the allegedly discriminatory conduct—a high bar in litigation.
Yet Trump’s team appears confident. The complaint portrays Dimon as the architect of a broader corporate strategy to distance JPMorgan from controversial political figures in the post-January 6 environment, allegedly using compliance mechanisms as cover for viewpoint discrimination.
Dimon’s Delicate Position
For Jamie Dimon, the lawsuit creates acute discomfort. He has cultivated an image as a steady hand in turbulent times—someone who can navigate political crosscurrents while keeping JPMorgan above the fray. He maintained working relationships with both the Trump and Biden administrations, advocated for practical business policies regardless of partisan source, and positioned himself as a voice of reason in polarized times.
Now he faces a lawsuit from a sitting president who commands fierce loyalty from roughly half the American electorate and who has never been shy about using his platform to wage public relations warfare. According to Reuters, JPMorgan’s initial response has been measured but firm: the bank denies all allegations and insists the account closures were based solely on “routine risk management protocols unrelated to any client’s political views.”
JPMorgan’s Defense: Risk Management or Political Censorship?
The Bank’s Rationale
JPMorgan has not yet filed a formal response to the lawsuit, but its public statements and background briefings to journalists reveal the contours of its defense. The bank argues that:
- Regulatory compliance: As a globally systemically important bank (G-SIB), JPMorgan faces extraordinary regulatory scrutiny and must maintain rigorous anti-money laundering, sanctions compliance, and risk management protocols.
- Reputational risk: The January 6 events triggered massive reputational risk assessments across corporate America. Banks routinely evaluate whether clients pose unacceptable reputational hazards—a legitimate business consideration.
- Operational independence: Account closure decisions are made by specialized risk and compliance teams using objective criteria, not by the CEO’s office based on political animus.
- Preexisting concerns: CNBC reports that sources close to JPMorgan suggest the bank had been conducting enhanced due diligence on Trump Organization accounts well before January 6, related to longstanding questions about the company’s financial practices.
The Industry Context
JPMorgan’s predicament reflects broader tensions in the banking sector. After January 6, numerous financial institutions severed ties with Trump-affiliated entities or individuals. Payment processors like Stripe stopped processing donations for Trump campaign entities. Banks conducting business with anyone connected to the Capitol riot faced intense public pressure and potential regulatory complications.
Yet this creates a troubling precedent. If banks can effectively de-person individuals from the financial system based on political controversy—however defined—where do the boundaries lie? Conservative activists have documented dozens of cases where individuals and organizations on the right claim they were “debanked” for their political views, from gun rights advocates to anti-abortion activists.
The Debanking Phenomenon: A Growing Flashpoint
What Is Political Debanking?
“Debanking” refers to financial institutions closing or denying accounts to customers based on factors unrelated to traditional banking risk—most controversially, political views or associations. The practice exists in a legal and ethical gray zone. Banks have broad discretion to choose their clients, but that discretion isn’t absolute, particularly when anti-discrimination laws or public utility considerations come into play.
The BBC describes the phenomenon as part of a broader trend in which major corporations use their market power to enforce ideological boundaries—what critics call “corporate cancel culture” and defenders characterize as legitimate risk management and values alignment.
Florida’s Anti-Debanking Law
Florida’s 2023 legislation specifically prohibits financial institutions from discriminating based on political opinions, religious beliefs, or “social credit scores”—a term borrowed from concerns about Chinese-style social monitoring systems. The law allows individuals and businesses to sue for damages if they can prove they were denied financial services for these prohibited reasons.
Trump’s lawsuit is the highest-profile test of this statute. If successful, it could open the floodgates for similar litigation and encourage other Republican-controlled states to enact comparable protections. If it fails, it may establish that banks retain broad discretion to evaluate clients holistically, including reputational and political considerations.
Wall Street’s Trump Dilemma: Navigating the Second Term
The Complicated Courtship
Wall Street’s relationship with Donald Trump has always been transactional and ambivalent. The financial sector enthusiastically supported his 2017 tax cuts and deregulatory agenda, yet many executives were privately appalled by his conduct and rhetoric. Jamie Dimon himself once criticized Trump’s handling of racial tensions, though he later walked back some comments.
Now, with Trump back in the White House pursuing an ambitious agenda that includes further banking deregulation, financial institutions face an uncomfortable calculus. Antagonizing the president risks regulatory retaliation, but appearing to capitulate to political pressure undermines their claims to operational independence.
The lawsuit intensifies this dilemma. If JPMorgan settles quickly or backs down, it may embolden Trump to use similar pressure tactics against other institutions. If the bank fights aggressively, it risks a protracted public battle with a president who thrives on conflict and commands a megaphone unlike any other.
Regulatory and Legislative Implications
The Trump administration’s financial regulatory appointees will be watching this case closely. While the lawsuit is a civil matter in state court—not subject to federal intervention—the broader questions it raises about banking access and political neutrality could inform federal policy.
Congressional Republicans have already signaled interest in federal anti-debanking legislation, modeled on Florida’s law. If Trump’s lawsuit gains traction, it could accelerate those efforts and create a new front in the ongoing culture wars over corporate America’s role in policing political speech and association.
Economic and Market Implications
Short-Term Market Reaction
JPMorgan’s stock barely flinched on news of the lawsuit—testimony to investors’ view that the case poses minimal financial risk to the bank. The $5 billion figure, while eye-catching, represents less than two weeks of JPMorgan’s typical quarterly profit. Legal fees and reputational damage are the more realistic concerns.
Long-Term Structural Questions
The deeper economic question is whether this lawsuit accelerates fragmentation in the financial services industry along political lines. Some conservative entrepreneurs are already building “anti-woke” banking alternatives, positioning themselves as havens for customers who fear political discrimination by mainstream institutions.
If successful, these parallel financial infrastructures could reduce efficiency, increase costs, and fragment liquidity in the banking system. Alternatively, they might introduce healthy competition and discipline for incumbent institutions that have grown complacent about customer service and political neutrality.
The Precedent Problem: Where Does This End?
Slippery Slopes on Both Sides
Both sides in this dispute can point to troubling hypotheticals. If banks cannot consider political factors at all in client selection, can they be forced to serve individuals or entities under sanctions, involved in ongoing criminal investigations, or credibly accused of financial fraud—provided those targets can frame their situation as political persecution?
Conversely, if banks have unlimited discretion to debank based on ideology, couldn’t conservative-led institutions refuse to serve progressive clients? Couldn’t banks in certain regions effectively exclude entire classes of politically disfavored customers?
The lawsuit forces courts to grapple with these questions without clear precedent. Banking law has traditionally granted financial institutions broad discretion in client selection, but those principles were developed in an era when banking and politics occupied more separate spheres.
What Happens Next: Legal Timeline and Likely Outcomes
Procedural Roadmap
JPMorgan will likely move to dismiss the case, arguing that Trump has failed to state a valid legal claim and that the bank’s actions fall within its protected business judgment. Florida’s anti-debanking law remains largely untested in litigation, so courts will have to interpret its scope and application.
If the case survives dismissal, discovery could be explosive. Trump’s attorneys would gain access to JPMorgan’s internal communications, risk assessments, and decision-making processes around the account closures. The bank would similarly probe Trump’s actual financial damages and alternative banking relationships.
Most legal analysts expect the case to settle rather than go to trial, though Trump’s litigious history and Dimon’s institutional resolve make predictions hazardous. A settlement could include no admission of wrongdoing but might involve JPMorgan agreeing to clearer, more transparent account closure policies.
The Political Calculus
Trump appears to view the lawsuit as both a genuine grievance and a useful political narrative. The “debanking” story resonates with his base’s sense that elite institutions weaponize their power against conservatives. Whether the case has legal merit may matter less than its political utility in reinforcing that narrative.
For JPMorgan, the priority will be containing damage—to its reputation, its regulatory standing, and its relationships with both political parties. The bank cannot afford to be seen as capitulating to political pressure, but neither can it afford a years-long public brawl with the President of the United States.
Conclusion: Banking, Power, and the Politics of Access
The Trump-JPMorgan lawsuit crystallizes tensions that extend far beyond one controversial president and one powerful bank. At its heart, this case asks who controls access to the infrastructure of modern capitalism—and on what terms.
Financial institutions occupy a quasi-public role in democratic societies. They are private enterprises with shareholder obligations, yet they also serve as gatekeepers to essential economic participation. When banks exercise that gatekeeping power based on political considerations—whether explicitly or through the malleable language of risk management—they enter contested terrain.
Trump’s lawsuit, whatever its ultimate legal fate, has already succeeded in forcing this question onto the national agenda. It challenges the post-January 6 consensus among corporate leaders that distancing from Trump carried no serious institutional cost. And it previews what may be a defining feature of Trump’s second term: the use of litigation, regulation, and executive power to reshape corporate America’s relationship with political controversy.
Jamie Dimon, who has navigated financial crises, regulatory transformations, and political upheavals with unusual dexterity, now faces perhaps his most delicate challenge. The lawsuit is a reminder that in contemporary America, even the most powerful banker cannot fully insulate his institution from the gravitational pull of politics.
The $5 billion question is ultimately not about damages—it’s about boundaries. Where does legitimate risk management end and political discrimination begin? The answer will reverberate through boardrooms and courtrooms for years to come.

US Impeachment Talk and White House Press Secretary Changes: What the Record Shows

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide

Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
AI Impact on Wages 2026: Productivity Soars, Paychecks Stagnate
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Analysis4 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025