Geopolitics
Trafigura’s Venezuelan Oil Gambit: When Geopolitics Meets Market Mechanics

How a landmark crude sale from Caracas signals the collision of energy pragmatism, sanctions architecture, and hemispheric power dynamics
The commodity trading world rarely produces moments of genuine geopolitical significance. Yet when Trafigura Group CEO Richard Holtum stood before President Donald Trump at the White House on January 9, 2026, announcing preparations to load the first Venezuelan crude shipment “within the next week,” he was signaling far more than a routine commercial transaction. This landmark sale represents the most consequential shift in Western Hemisphere energy flows since sanctions severed direct Venezuelan crude trade with the United States seven years ago.
What unfolded in that White House gathering—with nearly 20 industry representatives present—was nothing less than the reconfiguration of Atlantic Basin petroleum markets. The implications ripple across refinery economics in Louisiana and Texas, Canadian heavy crude pricing, geopolitical calculations in Beijing, and the future trajectory of a nation holding the world’s largest proven oil reserves yet producing barely one million barrels daily.
For students of political economy and commodity markets alike, this development offers a masterclass in how commercial incentives, regulatory frameworks, and strategic interests intersect—and occasionally collide.
The Commercial Architecture of an Unprecedented Deal
Trafigura, the world’s third-largest physical commodities trading house behind Vitol and Glencore, has spent decades cultivating expertise in jurisdictional complexity. Operating across 150 countries with revenues exceeding $230 billion annually, the Geneva-based trader has built its reputation on navigating precisely the kind of regulatory labyrinths that Venezuela now presents.
The company’s approach to this Venezuelan engagement reveals sophisticated risk management. According to Reuters, Trafigura and rival Vitol have secured preliminary licenses from the U.S. government authorizing Venezuelan oil imports and exports for an 18-month period. These authorizations, structured through the Treasury Department’s Office of Foreign Assets Control (OFAC), represent a calibrated shift in sanctions enforcement rather than wholesale relief.
The trading houses are not purchasing Venezuelan crude for their own account in the traditional sense. Instead, they’re providing logistical and marketing services at the U.S. government’s request—a crucial legal distinction. This structure allows Washington to maintain nominal control over Venezuelan oil flows and revenue distribution while leveraging private sector expertise in shipping, blending, and market placement.
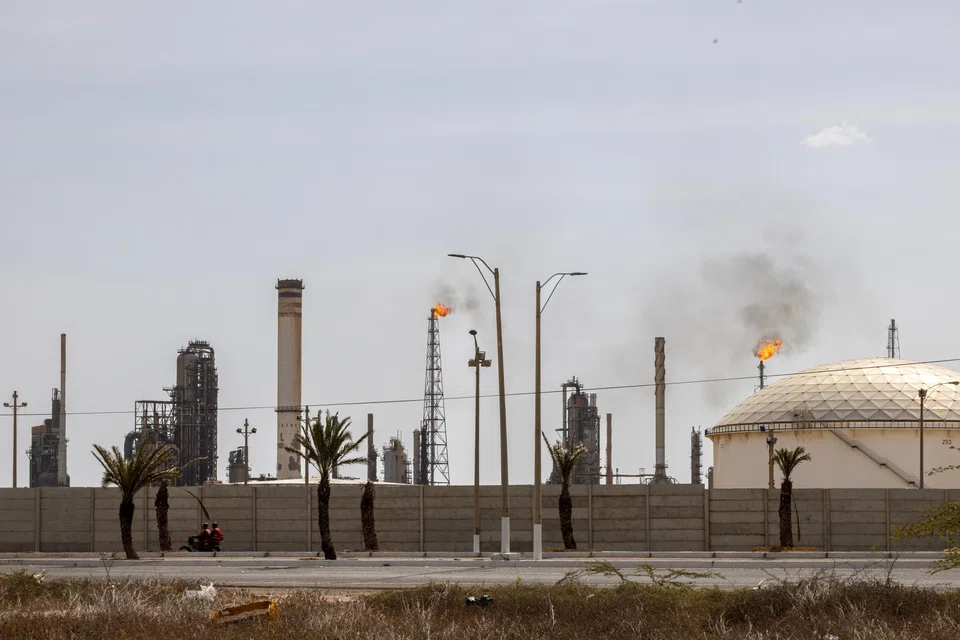
Industry sources familiar with the arrangements suggest initial shipment volumes in the range of 400,000 to 600,000 barrels per Very Large Crude Carrier (VLCC), with Venezuelan grades including Merey 16, BCF-17, and potentially upgraded Hamaca crude from the Orinoco Belt. These extra-heavy grades, with API gravity below 16 degrees and sulfur content exceeding 2.5%, require specialized refinery configurations—precisely what Gulf Coast facilities were designed to handle.
Venezuela’s Petroleum Paradox: Abundance Without Capacity
The disconnect between Venezuela’s resource endowment and production reality represents one of the starkest industrial collapses in modern energy history. With 303 billion barrels of proven reserves—surpassing even Saudi Arabia’s 267 billion—Venezuela theoretically controls nearly 18% of global recoverable petroleum resources, according to the U.S. Energy Information Administration.
Yet current production hovers around 1.1 million barrels per day, down from 3.5 million bpd achieved in the late 1990s. This represents a 68% decline from peak capacity—a deterioration driven by chronic underinvestment, workforce attrition, infrastructure decay, and the compounding effects of U.S. sanctions imposed since 2019.
Rystad Energy, a leading petroleum research firm, estimates that approximately $53 billion in upstream and infrastructure investment would be required over the next 15 years merely to maintain current production levels. Restoring output to 3 million bpd by 2040—the level Venezuela last sustained in the early 2000s—would require approximately $183 billion in total capital expenditure, or roughly $12 billion annually.
The Orinoco Belt region, containing the densest concentration of reserves, has seen production plummet from 630,000 bpd in November to 540,000 bpd in December 2025, reflecting systemic infrastructure vulnerabilities. Upgraders designed to convert extra-heavy crude into more marketable synthetic grades operate far below capacity or lie completely idle. According to industry assessments, PDVSA’s pipeline network has received virtually no meaningful updates in five decades.
For context, Venezuela’s deteriorated production infrastructure means that even with political stability and sanctions relief, energy analytics firm Kpler projects output could reach only 1.2 million bpd by end-2026—a modest 400,000 bpd increase requiring mid-cycle investment and repairs at facilities like the Petropiar upgrader operated by Chevron.
The Refinery Calculus: Why Gulf Coast Operators Are Paying Attention
Louisiana’s 15 crude oil refineries, accounting for one-sixth of total U.S. refining capacity with processing ability near 3 million barrels daily, were engineered with one primary feedstock in mind: heavy sour crude from Latin America, particularly Venezuela. Most facilities were constructed in the 1960s and 1970s, then retrofitted with advanced coking capacity and corrosion-resistant metallurgy to handle the high-sulfur, low-API gravity crudes that Venezuelan fields produce.
The economics are compelling. Bloomberg analysis indicates that highly complex refiners with substantial coking capacity—including Valero Energy, Marathon Petroleum, Phillips 66, and PBF Energy—can achieve 33% distillate yields versus 30% for medium-complexity plants. Venezuelan Merey crude from the Orinoco Belt, among the highest in sulfur content globally, maximizes the competitive advantage of these specialized facilities.
The U.S. Gulf Coast currently imports approximately 665,000 bpd of heavy crude with API gravity below 22 degrees from sources including Canada (Western Canadian Select), Mexico (Maya), and Middle Eastern producers. Energy Intelligence estimates that U.S. refiners could absorb an additional 200,000 bpd of Venezuelan crude relatively quickly, with potential to increase that figure substantially after equipment adjustments and supply contract renegotiations.
At the start of this century, U.S. refiners were importing approximately 1.2 million bpd of Venezuelan oil—much of it upgraded bitumen. Current infrastructure and refinery configurations could theoretically support a return to those volumes, though logistics, pricing, and regulatory clarity would need to align.
For refiners, Venezuelan crude offers several advantages. First, proximity translates to freight economics: shipping from Venezuelan terminals to Gulf Coast ports requires roughly 5-7 days versus 30-45 days from Middle Eastern sources. Second, Venezuelan grades typically trade at discounts to benchmark crudes, potentially widening crack spreads—the difference between crude costs and refined product values. Third, these heavy grades yield higher proportions of diesel and fuel oil, products currently commanding premium pricing due to renewable diesel conversions reducing traditional distillate supply.
The counterargument, however, involves operational adjustments. Many Gulf Coast refiners have spent the past 15 years optimizing their configurations for the glut of light sweet shale crude produced domestically. Pivoting back toward heavier feedstocks requires time and capital—industry sources suggest 3-6 months per processing unit, with costs potentially exceeding $1 per barrel in margin improvement to justify the investment.
Trafigura’s Strategic Positioning in Complex Markets
What distinguishes Trafigura in this Venezuelan engagement extends beyond balance sheet capacity. The company has cultivated a decades-long specialization in jurisdictionally difficult environments—precisely the combination of political risk, infrastructure constraints, and regulatory complexity that Venezuela epitomizes.
Trafigura’s historical Venezuela operations predate sanctions. Before 2019, the trader was among the most active marketers of Venezuelan crude, establishing relationships with PDVSA and building operational knowledge of loading terminals, crude quality variations, and blending requirements. That institutional memory proves invaluable now.
The company’s approach to compliance has been tested repeatedly. Trafigura has faced scrutiny over operations in sanctioned jurisdictions before, including settlements with the U.S. Department of Justice for bribery allegations related to Brazilian operations and with the Commodity Futures Trading Commission for gasoline market manipulation in Mexico. These experiences have necessitated robust compliance infrastructure—a prerequisite for operating under OFAC licenses where violations carry severe civil and criminal penalties.
Trafigura’s business model—focused on logistics, blending, and market arbitrage rather than production assets—aligns well with the current Venezuelan opportunity. The company can deploy expertise in vessel chartering, crude quality analysis, and customer matching without requiring the massive upstream capital that would deter integrated oil majors.
Competitor Vitol, the world’s largest independent oil trader, brings similar capabilities. Vitol’s participation signals industry-wide assessment that Venezuelan crude flows, under U.S. oversight, present acceptable risk-adjusted returns despite ongoing political uncertainty.
The Sanctions Architecture: Calibrated Control, Not Wholesale Relief
Understanding the current regulatory framework requires precision. The Trump administration has not lifted Venezuelan oil sanctions. Rather, OFAC has issued specific licenses to selected trading houses, creating a controlled channel for Venezuelan crude to reach international markets under explicit conditions.
This represents a dramatic evolution from the sanctions regime imposed in January 2019, when OFAC designated PDVSA for operating in Venezuela’s oil sector pursuant to Executive Order 13850. That designation froze all PDVSA property subject to U.S. jurisdiction and prohibited American entities from transacting with the company without authorization.
Treasury Department statements emphasize that current arrangements aim to “control the marketing and flow of funds in Venezuela so those funds can be used to better the conditions of the Venezuelan people.” This framing positions the U.S. government as de facto revenue manager rather than sanctions enforcer—a subtle but significant shift.
The legal mechanism involves General Licenses and specific licenses issued through OFAC. General License 41, which had authorized Chevron to resume restricted operations since November 2022, was amended in March 2025 requiring the company to wind down operations. Most other specific licenses expired concurrently. The new licenses to Trafigura and Vitol represent a different model: government-directed marketing rather than production partnerships.
The Treasury’s recent actions underscore that enforcement remains vigorous against non-authorized actors. In December 2025, OFAC sanctioned six shipping companies and identified six vessels as blocked property for operating in Venezuela’s oil sector without authorization. These companies were part of the “shadow fleet” that has historically moved Venezuelan crude to China and other buyers at steep discounts.
The sanctions architecture creates market segmentation: licensed traders operating under U.S. oversight versus shadow fleet operators facing interdiction risk. This bifurcation should theoretically compress discounts for licensed flows while maintaining sanctions pressure on regime-linked networks.
Geopolitical Dimensions: Rebalancing Hemispheric Energy Flows
The strategic implications extend far beyond commercial calculations. For decades, China has absorbed the lion’s share of Venezuelan oil exports through opaque arrangements involving state-owned enterprises and lesser-known intermediaries. These flows, estimated at 400,000 bpd in 2025 according to Kpler, often occurred at significant discounts and through non-transparent payment structures linked to debt repayment.
Redirecting Venezuelan crude to U.S. Gulf Coast refiners accomplishes several objectives simultaneously. It provides Washington with leverage over Venezuelan revenue streams, reduces Beijing’s monopsony position in Venezuelan petroleum markets, and offers Gulf Coast refiners access to feedstocks compatible with their infrastructure at potentially attractive pricing.
The timing coincides with broader Trump administration efforts to reshape hemispheric relationships. Following the controversial detention of Venezuelan officials and increased naval presence in Caribbean waters, the Venezuelan oil arrangement represents the economic component of a multi-dimensional strategy toward Caracas.
For Canada, the implications prove more ambiguous. Western Canadian Select (WCS) crude competes directly with Venezuelan heavy grades in Gulf Coast markets. If Venezuelan volumes increase substantially, WCS could face pricing pressure—though Canadian producers might compensate by redirecting flows westward through the expanded Trans Mountain pipeline to Pacific markets serving Asian buyers.
OPEC dynamics add another layer. Venezuela remains an OPEC member despite production far below its quota. Restoration of Venezuelan output, even to 1.5-2 million bpd, would introduce additional heavy crude supply into global markets already experiencing oversupply conditions. Brent crude has been trading near $60 per barrel, with analysts projecting potential pressure toward $50 if Venezuelan production ramps significantly.
The International Energy Agency projects that global oil demand growth will decelerate through 2026, driven by electric vehicle adoption, efficiency improvements, and economic headwinds. In this context, additional Venezuelan supply could pressure prices—benefiting consumers and refiners while challenging higher-cost producers.
Infrastructure Realities: The Time Dimension of Production Recovery
Commodity traders and refinery executives can move relatively quickly. Geopolitics shifts in weeks or months. But petroleum infrastructure operates on a different timeline entirely.
Venezuela’s production capacity deterioration reflects decades of deferred maintenance, equipment failures, workforce departures, and technological obsolescence. Restoring output isn’t a matter of flipping switches—it requires systematic well workovers, pipeline repairs, upgrader rehabilitations, and power system stabilization.
Industry assessments suggest that approximately 300,000 bpd of additional supply could be restored within 2-3 years with limited incremental spending, primarily through well intervention in the Maracaibo Basin and completion of deferred maintenance at existing facilities. This represents the “low-hanging fruit”—production that can be recovered through operational optimization rather than major capital deployment.
Reaching 1.7-1.8 million bpd by 2028 would require substantial upstream capital spending and the restart of idled upgraders in the Orinoco Belt, according to Kpler. Without sweeping institutional reform at PDVSA and new upstream contracts with foreign operators, output exceeding 2 million bpd appears unlikely within this decade.
The investment calculus hinges on political risk assessment. American oil companies—despite White House encouragement—have shown limited appetite for committing billions to Venezuelan operations absent legal framework certainty, property rights clarity, and political stability guarantees. Chevron, currently the only U.S. major with meaningful Venezuelan presence, has tempered expansion plans given regulatory uncertainty.
International operators face additional considerations. Environmental, Social, and Governance (ESG) commitments have become central to institutional investor relations. Venezuelan exposure—given corruption perceptions, human rights concerns, and environmental track records—creates reputational risks that many companies find difficult to justify regardless of commercial returns.
Market Mechanics: Pricing, Logistics, and Competitive Dynamics
The petroleum markets pricing Venezuelan crude provides crucial context. Venezuelan grades trade on a netback basis from Gulf Coast values, with adjustments for quality differentials, freight costs, and risk premiums. Historically, Merey crude traded at discounts of $8-15 per barrel versus West Texas Intermediate benchmark, reflecting its inferior quality and higher processing costs.
Under the new arrangement with U.S. government oversight, several factors should theoretically compress discounts. First, removal of sanctions risk reduces the premium required to compensate buyers for regulatory exposure. Second, official sales channels eliminate the opacity and logistical complications associated with shadow fleet operations. Third, greater volume certainty allows refiners to optimize processing schedules rather than treating Venezuelan crude as opportunistic.
However, Venezuelan crude must still compete with established alternatives. Western Canadian Select typically trades at $15-20 discounts to WTI. Mexican Maya, another heavy sour grade, trades at $3-6 discounts. Middle Eastern grades like Arab Heavy and Basrah Heavy carry their own pricing dynamics based on quality and freight economics.
The logistics dimension proves equally complex. Venezuela’s export infrastructure has deteriorated alongside production capacity. Loading terminals at Jose and Bajo Grande have experienced periodic outages. VLCC (Very Large Crude Carrier) availability fluctuates based on insurance market willingness to cover Venezuelan waters. Blending requirements—mixing extra-heavy crude with diluents to achieve transportable viscosity—add operational complexity and cost.
For Trafigura and Vitol, success requires optimizing each dimension: sourcing crude at competitive prices, securing appropriate tonnage, blending to meet refinery specifications, timing deliveries to match refinery turnaround schedules, and managing counterparty credit risk. These trading houses excel precisely because they’ve built systems to coordinate these moving parts across global supply chains.
Refinery Sector Response: Cautious Interest, Conditional Commitment
Gulf Coast refinery executives express measured enthusiasm tempered by pragmatic concerns. Conversations with industry sources reveal a consistent pattern: interest in Venezuelan crude availability exists, but commitment requires clarity on volume reliability, price competitiveness, and regulatory stability.
Valero Energy, one of the Gulf Coast’s largest independent refiners with significant heavy crude coking capacity, has historical experience processing Venezuelan grades. The company’s complex refineries in Texas and Louisiana could theoretically absorb substantial volumes. Similarly, Marathon Petroleum, Phillips 66, and PBF Energy—all identified by Bloomberg as having advantaged positions—have begun preliminary discussions with traders.
The private calculus involves margin analysis. Refiners model crack spreads—the difference between crude acquisition costs and refined product revenue—under various scenarios. Venezuelan crude must offer sufficient discounts to justify the operational adjustments required to process it relative to current feedstock slates.
One refinery consultant suggested that processing Venezuelan heavy sour could improve margins by more than $1 per barrel for optimally configured facilities—a meaningful improvement in an industry where quarterly earnings often hinge on single-digit margin shifts. However, realizing those economics requires locking in regular supplies and completing equipment modifications.
The other consideration involves alternative destinations. If Venezuelan crude doesn’t offer competitive economics to Gulf Coast refiners, it could flow to Indian or Spanish facilities—both have historical experience with Venezuelan grades and could potentially absorb volumes. This global optionality constrains how aggressively refiners can negotiate, as traders maintain leverage through alternative placement channels.
Forward-Looking Scenarios: Mapping Possible Trajectories
Projecting Venezuelan oil’s trajectory requires scenario planning across multiple dimensions. Consider three plausible pathways:
Scenario One: Controlled Ramp (Most Probable) Venezuelan crude exports to U.S. Gulf Coast increase gradually to 300,000-400,000 bpd by end-2026, facilitated by licensed traders under government oversight. Production reaches 1.2 million bpd through operational optimization without major capital deployment. Revenues flow through supervised channels, with incremental stability allowing limited foreign investment. This scenario implies modest pressure on Canadian heavy crude pricing, marginal tightening of heavy-light differentials, and sustainable if unspectacular commercial returns for trading houses.
Scenario Two: Accelerated Recovery (Optimistic) Political consolidation and institutional reform unlock significant foreign investment. Production accelerates toward 1.7-1.8 million bpd by 2028 as upgraded infrastructure comes online. U.S. and international oil companies commit tens of billions in upstream capital, viewing Venezuelan reserves as strategic long-term assets. In this pathway, Venezuelan crude becomes a major factor in Atlantic Basin markets, materially impacting WCS pricing and potentially displacing Middle Eastern imports. However, this scenario requires sustained political stability—historically elusive in Venezuela.
Scenario Three: Partial Reversal (Bearish) Operational challenges, infrastructure failures, or political instability constrain production recovery. Volumes remain below 1 million bpd despite initial optimism. Sanctions enforcement against non-licensed actors proves inconsistent, allowing shadow fleet operations to continue. Limited revenue transparency and governance failures deter major investment. In this scenario, Venezuelan crude remains a niche supply source rather than transformative market factor, with Trafigura and Vitol managing modest volumes under challenging conditions.
The probability-weighted outcome likely falls between scenarios one and three—meaningful but constrained growth, subject to political volatility and infrastructure limitations that prevent full potential realization.
The Institutional Question: Can PDVSA Be Reformed?
Perhaps the most fundamental uncertainty involves Petróleos de Venezuela (PDVSA) itself. The state oil company, once among Latin America’s premier petroleum enterprises, has become synonymous with mismanagement, corruption, and operational dysfunction.
PDVSA’s decline predates sanctions, as noted by Carole Nakhle, CEO of Crystol Energy: “The collapse predates sanctions. Chronic mismanagement, politicization and underinvestment weakened the industry long before restrictions were imposed.” Sanctions accelerated deterioration but didn’t originate it.
Restructuring PDVSA would require addressing systemic issues: depoliticizing hiring and operations, implementing transparent financial reporting, establishing commercial rather than political decision-making processes, and potentially restructuring approximately $190 billion in outstanding debt obligations owed to creditors including China, Russia, and bondholders.
Without comprehensive institutional reform, foreign companies remain reluctant to commit capital. Joint ventures and service contracts require enforceable legal frameworks and predictable fiscal terms—precisely what Venezuela has lacked for two decades. Some analysts suggest that meaningful recovery might require PDVSA’s effective dismantling and reconstruction from first principles—a politically fraught proposition that successive governments have proven unwilling to undertake.
Broader Implications: Lessons for Energy Geopolitics
This Venezuelan oil saga offers several insights applicable beyond the immediate case:
First, sanctions prove most effective when they change incentive structures rather than simply imposing costs. The current approach—using licensed trading as a control mechanism—represents an evolution from blanket prohibition toward calibrated engagement. Whether this proves more effective at achieving policy objectives remains to be seen.
Second, commodity trading houses occupy a unique position in global energy systems. Their expertise in logistics, risk management, and market arbitrage makes them valuable intermediaries when geopolitical objectives intersect with commercial imperatives. Trafigura and Vitol aren’t merely profit-seekers; they’re providing functionality that governments and national oil companies cannot easily replicate.
Third, infrastructure constraints impose real limits on geopolitical flexibility. Regardless of political developments, Venezuelan production cannot snap back quickly. The physical reality of deteriorated wells, corroded pipelines, and idled upgraders defines what’s possible over relevant timeframes.
Fourth, global oil markets have evolved toward abundance, reducing the strategic leverage that petroleum once provided. With U.S. shale production, Canadian oil sands, Brazilian deepwater, and Guyana offshore fields all contributing supply, Venezuelan barrels matter less than they did when the country produced 3.5 million bpd. This reduces the urgency from both commercial and geopolitical perspectives.
Conclusion: Pragmatism Ascendant, With Caveats
Trafigura’s preparation to load Venezuelan crude represents pragmatism superseding ideology in energy policy—at least provisionally. The arrangement acknowledges that Gulf Coast refiners can utilize Venezuelan heavy crude efficiently, that managed engagement might generate better outcomes than isolation, and that commodity trading expertise can facilitate complex transactions that governments struggle to execute directly.
Yet pragmatism operates within constraints. Infrastructure realities limit how quickly production can recover. Political uncertainties create investment hesitancy. Institutional dysfunction at PDVSA poses ongoing operational challenges. Global supply abundance reduces commercial urgency. These factors collectively suggest that Venezuelan crude will return to international markets, but gradually and conditionally rather than transformatively.
For market observers, several variables warrant monitoring: actual loading volumes versus projections, refinery uptake rates and processing economics, OFAC enforcement consistency against unauthorized actors, and infrastructure investment commitments from international oil companies. These indicators will reveal whether this Venezuelan engagement represents substantive change or merely incremental adjustment at the margins.
The intersection of energy markets and geopolitics rarely produces clean narratives. What unfolds in Venezuela over coming months will test whether commercial incentives can overcome institutional dysfunction, whether controlled engagement proves more effective than isolation, and whether pragmatism in energy policy can be sustained amid inevitable political turbulence.
For now, Trafigura prepares to load crude. Refiners evaluate economics. Policymakers calibrate oversight mechanisms. And the fundamental tension persists: between Venezuela’s immense petroleum potential and its demonstrated inability to realize it. That tension—not any single shipment—defines the Venezuelan oil story. Everything else is execution detail.
The author analyzes commodity markets and energy geopolitics with expertise in petroleum economics, sanctions policy, and hemispheric trade dynamics. Views expressed represent independent analysis informed by premium sources and industry consultation.

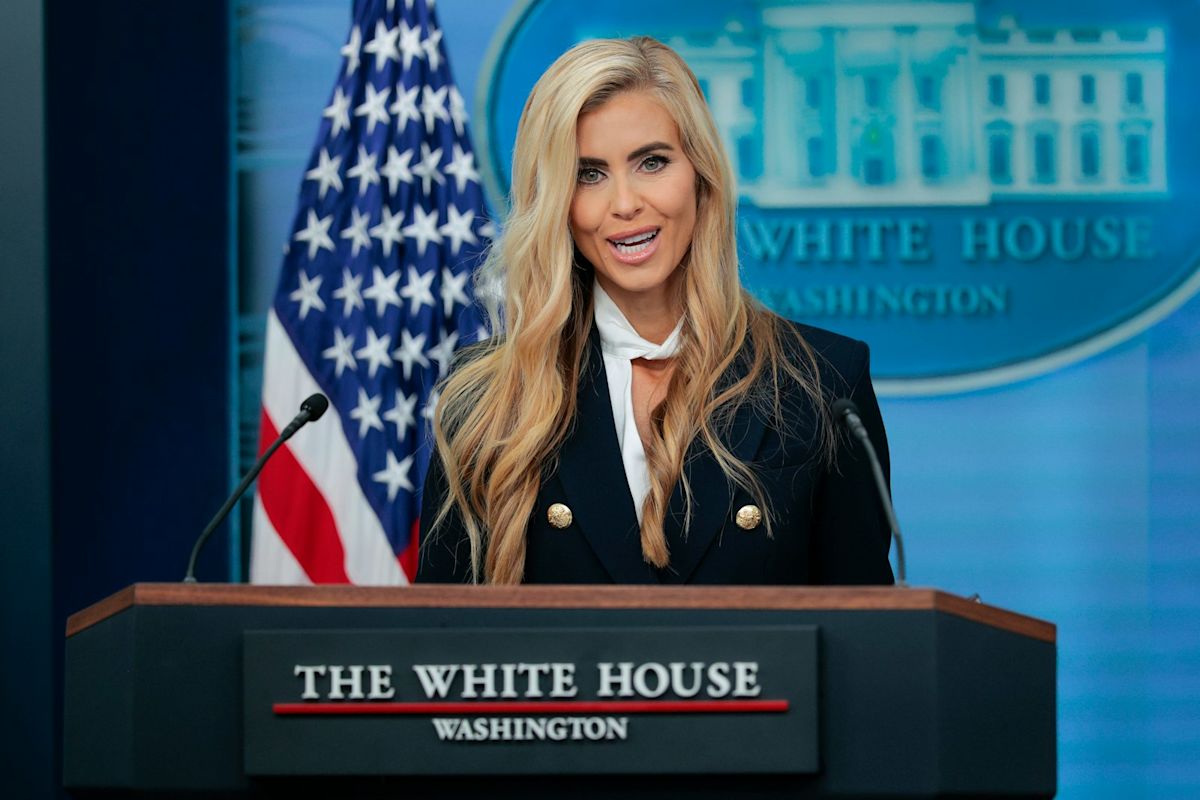
Online interest in impeachment and White House staffing has risen in a political environment where a few words can badly distort the underlying story. A resolution was introduced is not the same as the House voted to impeach. A press secretary was removed is not the same as the administration changed policy. Both require evidence, dates and clear procedural language.
Two verifiable developments frame the discussion as of October 25, 2026. A House impeachment resolution was tabled on September 15, and the short tenure of White House press secretary Katie Zacharia ended in mid-October, according to official congressional records and major US reporting. Neither event should be inflated into an unverified claim about new votes or a new administration decision.
The impeachment resolution: what the House actually voted on
House Resolution 1486 concerned impeachment of President Donald Trump. The US House’s official floor summary records the September 15 vote on a motion to table the measure: 232–147, with 47 members recorded as present. A successful tabling motion sets aside a measure; it is not the adoption of articles of impeachment.
This distinction is essential. A social post describing that roll call as a vote to impeach reverses the outcome. A later claim about a different resolution should be separately checked against the official Congress website and House roll-call records rather than treated as an update to an old headline without evidence.
Congressional procedure is sometimes inconvenient for trending-content production. It is also what protects the reader from misinformation. The reporter’s task is to identify the motion, the chamber, the date and the disposition before attempting broader political interpretation.
What happened to the press secretary?
CBS News reported on October 16 that Zacharia was removed from the White House press-secretary role after roughly five days. CBS cited US officials and reported scrutiny of her credentials and performance. It also noted that the White House had not yet announced a successor in that report.
A leadership change in the briefing room can be significant for how an administration communicates with journalists and the public. But personnel turnover alone does not establish a change to economic policy, foreign strategy or legal proceedings. Those substantive conclusions require separate evidence.
Why the two stories became combustible
Impeachment is a constitutionally consequential process and a powerful political symbol. White House press briefings are the main arena where officials defend decisions under questioning. When both topics circulate at once, online narratives may stitch them into a supposed constitutional crisis—even if there is no documented direct connection.
A measured account must resist that temptation. Political opponents may view impeachment proposals as necessary oversight; supporters of the president may describe them as partisan exercises. The purpose of reporting is not to resolve those disagreements by advocacy, but to distinguish political argument from verifiable institutional action.
The fact-checker’s four-part test
| Question | Evidence needed |
|---|---|
| Was an impeachment measure introduced? | Official resolution number and introduction date |
| Did the House approve articles? | Recorded vote on adopting the relevant articles |
| Was an official removed? | Direct statement or multiple reliable attributed reports |
| Who now holds the position? | Current White House announcement, not an old biography |
This is particularly important during a midterm-election year. Campaigns and commentators have incentives to present ordinary procedural setbacks as existential victories or defeats. Readers benefit from precise language instead of ever-louder adjectives.
What should international readers take from it?
For audiences in Pakistan and elsewhere in Asia, US political turmoil matters when it alters policy certainty: trade measures, sanctions, diplomacy, defence arrangements, fiscal decisions and monetary-policy appointments. None should be projected automatically from a press secretary’s dismissal or a resolution that did not pass.
It is sensible to monitor official notices, court actions and enacted policy. It is not sensible to treat search-volume spikes as proof of truth. Search trends measure curiosity, fear and newsworthiness; they do not independently confirm the event people are typing about.
Why parliamentary verbs matter
US political coverage frequently compresses filed, referred, tabled, passed and enacted into the generic word approved. Those actions are not interchangeable. A resolution can be introduced without advancing beyond committee. A motion to table is a vote about whether the chamber will proceed, not a judgment approving the underlying allegations. A measure passed by one chamber may still require further constitutional steps.
The same precision is necessary in personnel news. A spokesperson’s announced departure, a media report citing officials and a formal appointment are different evidence levels. Where the administration has not issued a replacement notice, describing a favourite online rumour as the current officeholder is poor reporting.
Public debate about impeachment also should not be reduced to the number of search queries. Search interest can be increased by critics, supporters, confused readers or social platforms circulating an old clip. It gives no reliable denominator for public opinion. A survey with a known sample and methodology is a different kind of evidence.
The best follow-up coverage would monitor official House actions and White House releases, then connect any actual policy changes to their legal basis. That approach serves readers across the political spectrum without manufacturing a crisis.
Has the September 15 House vote impeached Trump?
No. The recorded action was a successful motion to table the resolution, not a vote approving impeachment articles.
Was Katie Zacharia removed?
Yes, CBS reported her departure from the role on October 16. Any later staffing changes should be checked directly before publication.
Do impeachment trends reveal who will win the midterms?
No. Search spikes are not representative polling or an election forecast.
The standard worth keeping: precise institutional language is not timid journalism. It is the difference between telling readers what happened and telling them what a viral headline wants them to believe.

The Pentagon rarely uses the word “unrecoverable” in an official acquisition report. It used it this August, in a Selected Acquisition Report describing the state of Boeing’s F-15EX Eagle II program — and the phrase should have every defense-sector supply chain manager, procurement officer, and B2B logistics executive paying close attention.
The core problem: a 102-day strike at Boeing’s St. Louis-area production facilities didn’t just cost the company three months of output. It broke a delivery schedule in a way the Pentagon itself now says can’t be fully undone.
The Aircraft: What the F-15EX Actually Delivers
Before the supply chain story, it’s worth understanding why the Air Force wants this jet badly enough to be publicly frustrated about delays.
The F-15EX Eagle II is the most advanced variant of the F-15 lineage ever built:
- Digital fly-by-wire flight controls and a large-area glass cockpit with touchscreen interface
- A new APG-82 AESA radar, Joint Helmet Mounted Cueing System, and EPAWSS self-defense electronic warfare suite
- Higher speed and longer range than legacy F-15 variants, with a 29,000-lb payload capacity across additional weapons stations versus older Eagles
- A per-unit flyaway cost of roughly $90–93 million, with a 30-year, 104-jet program lifecycle cost estimated at $30–35 billion — a figure that compares favorably to stealth alternatives on a pure cost basis
The Air Force has committed to replacing aging F-15C/D fleets — including 36 jets slated to permanently replace 48 legacy Eagles at Kadena Air Base, Okinawa — with the EX variant, making this as much an Indo-Pacific readiness story as a domestic manufacturing one.
The Strike: 102 Days That Broke a Production Curve
Roughly 3,000+ Boeing machinists in the St. Louis region — spanning facilities in St. Louis, St. Charles, and Mascoutah, Illinois — walked off the job on August 4, 2025. The strike didn’t end until November 13–17, 2025, a complete production halt of more than three months.
Before the walkout, Boeing’s plan was aggressive but achievable:
- Deliver a full dozen Lot 2 Eagle IIs by the end of calendar 2025
- Ramp to an assembly rate of two jets per month by early 2026
- Maintain the program’s prior track record of staying within cost, schedule, and performance baselines — with all Lot 1 aircraft already delivered on time
The strike erased that runway entirely. Then–Air Force chief of staff nominee Gen. Kenneth Wilsbach confirmed the delay in written Senate testimony well before the strike even ended, warning lawmakers that overseas deliveries — including to Kadena — would be pushed into 2026.
Why the Pentagon Called the Slip “Unrecoverable”
Here’s the detail that separates this piece from standard defense-news coverage: the August 2026 Selected Acquisition Report doesn’t just describe a delay — it describes a structural, non-recoverable schedule slip.
- Boeing’s original contract required all 12 Lot 3 jets delivered in early calendar 2026.
- Instead, only about six will arrive by year’s end.
- The report explicitly frames this shortfall as permanent — the missed units are not simply “coming later,” they represent lost production capacity the line cannot make up under current constraints.
The Real Bottleneck: Parts Shortages Compounding the Strike
This is the angle that pure aviation-hobbyist coverage tends to skip, but that matters enormously to defense-sector procurement and supply chain software buyers: the strike exposed — and worsened — a parts shortage that predates it.
- Elbit-built large-area displays and low-profile head-up displays, which give the Eagle II its signature glass cockpit, are running short.
- General Electric F110 engines, the powerplant behind the jet’s performance envelope, face their own allocation constraints.
- Collins-made ejection seat cartridges round out the list of critical, single-source components.
Stockpiled inventory built up before the strike was sufficient to cover Lot 1B production. Everything after that is exposed. The Pentagon has resorted to borrowing-and-payback arrangements with foreign military sales customers — essentially reallocating parts earmarked for allied buyers back to U.S. production lines, then repaying the debt later — just to keep the line moving. That’s not a sustainable long-term fix; it’s a stopgap that shifts risk onto allied delivery schedules instead of eliminating it.
What This Means for Defense Contractors and Suppliers
For B2B readers in the defense and aerospace supply chain space, the actionable takeaways are:
- Single-source component risk is now a headline Pentagon concern, not a theoretical one. Any supplier or integrator still running single-vendor sourcing on flight-critical components (displays, engines, ejection systems) should expect increased scrutiny — and increased opportunity for qualified second-source suppliers.
- Supply chain visibility software and multi-tier risk modeling tools are likely to see increased defense-sector procurement interest as primes try to avoid a repeat of the Elbit/GE bottleneck on other programs.
- Labor relations at unionized aerospace primes are now a directly quantifiable program risk, one the Pentagon is willing to describe in a public acquisition document. Expect this to influence how future defense contracts price in labor-disruption contingencies.
- The F-15EX buy itself may be doubling in size even as the current lots run behind — the same Selected Acquisition Report flagged new cost and schedule uncertainty tied to an expanded production run, including warnings that radar, mission computer, electronic warfare, and engine systems could become obsolete over a longer timeline, requiring a “significant redesign effort” whose full cost hasn’t yet been estimated.
What Competitors Are Missing
Most defense trade coverage of the F-15EX delays stopped reporting once the strike itself ended in November 2025. The more important story — the one buried in an August 2026 acquisition document most outlets haven’t dug into — is that the schedule damage from that strike is now classified by the Pentagon as permanent, and that a second, ongoing bottleneck (Elbit displays and GE F110 engines) means the program isn’t fully back to healthy even ten months after the picket lines came down.
Timeline at a Glance
- Aug. 4, 2025 — St. Louis strike begins
- Oct. 2025 — Wilsbach confirms delivery delays in Senate testimony
- Nov. 13–17, 2025 — Strike ends
- Nov. 26, 2025 — First post-strike F-15EX delivered (142nd Wing, Portland ANG)
- Feb. 2026 — Air Force confirms delayed Kadena Air Base deployment
- Apr.–Jun. 2026 — Boeing targets doubling production rate to two jets/month
- Aug. 2026 — Selected Acquisition Report flags “unrecoverable delays” and parts shortages
People also Ask :
Q: Why are F-15EX Eagle II deliveries delayed?
A 102-day strike at Boeing’s St. Louis-area facilities (August–November 2025) halted F-15EX production, and a 2026 Pentagon acquisition report calls the resulting schedule slip “unrecoverable” — only about six of the contracted 12 Lot 3 jets will arrive by the end of 2026 instead of all 12 in early 2026. Ongoing shortages of Elbit-built cockpit displays and GE F110 engines are compounding the delay.
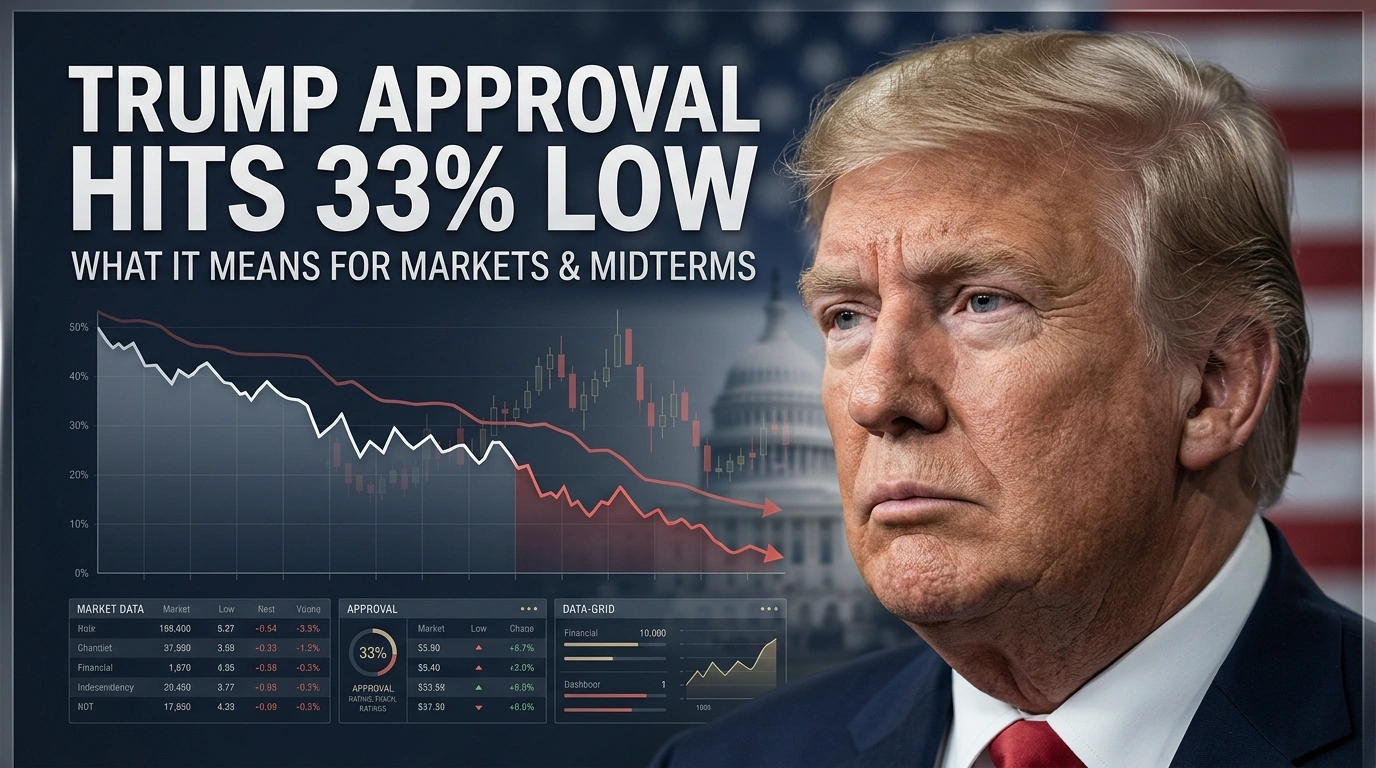
Trump’s approval rating has hit a second-term low of 33% in multiple polls this summer. Here’s what’s driving the decline, how it compares historically, and what it could mean for markets and the 2026 midterms.
Key Takeaways
- Trump’s approval rating has hit 33% in multiple independent polls this summer, including Reuters/Ipsos, The Economist/YouGov, and AP-NORC — a new low for his second term.
- The decline has been steep: Reuters/Ipsos polling shows a 14-point slide from 47% at the start of his second term to 33% now, with disapproval climbing from 41% to 65%.
- Polling averages remain somewhat higher than the lowest individual polls — the Decision Desk HQ average stood at 39.2%, illustrating the spread between different methodologies.
- The unpopular Iran conflict is a major drag: only 31% of Americans support continued U.S. military action, and 83% believe the conflict will continue for an extended period.
- Historical comparison is unfavorable: Trump’s current numbers trail his own first-term approval at the same point (41% in 2018) and are also below Biden’s comparable second-year approval (40% in August 2022).
Breaking Down the Numbers
Multiple independent polling organizations have converged on a similar, unflattering picture of President Trump’s standing heading into the 2026 midterms:
- Reuters/Ipsos: 33% approval, 65% disapproval (held steady across two consecutive surveys in mid-to-late August)
- The Economist/YouGov: 33% approval, a new low for that poll as of late August
- AP-NORC: 33% approval in a late-July survey — three points below Biden’s July 2022 approval and eight points below Trump’s own first-term July numbers
- Decision Desk HQ (DDHQ) average: 39.2%, the second-lowest since May, with 57.5% disapproving
The gap between the lowest individual polls (33%) and the polling average (around 39%) is a useful reminder for anyone tracking this story: individual polls can diverge meaningfully from methodology to methodology, and averages tend to smooth out the noise. Still, the consistent direction across virtually every major pollster — down, not up — is the more important signal than any single data point.
The Trajectory Matters as Much as the Level
According to Reuters/Ipsos tracking, Trump’s approval has fallen 14 points since the start of his second term, from 47% down to 33%, while disapproval has climbed 24 points, from 41% to 65%. That’s a significant and sustained erosion, not a single bad news cycle.
What’s Driving the Decline?
1. The Iran Conflict
An unpopular and prolonged U.S. military engagement with Iran is a significant drag on approval numbers:
- Only 31% of Americans support continued U.S. military action in Iran, down from 34% earlier in the summer and 37% in March.
- 83% of Americans believe the conflict will continue “for an extended period,” up from 80% earlier in the month — suggesting fatigue is building rather than easing.
- Approval of Trump’s handling of the Iran conflict specifically has declined even among Republicans, dropping from 71% to 61% in recent tracking, with just 48% of Republicans saying the U.S. should continue military action.
2. Economic Concerns
Polling context around the approval decline points to persistent economic anxiety among Americans as a contributing factor, compounding the foreign policy drag.
3. Historical Second-Term Pattern
Trump’s approval trajectory now trails not just his own first term, but also recent predecessors at comparable points:
| President | Approval at Comparable Point | Source |
|---|---|---|
| Trump (2026, second term) | 33% | Reuters/Ipsos |
| Trump (2018, first term, midterm year) | 41% | Reuters/Ipsos |
| Biden (August 2022) | 40% | Reuters/Ipsos |
Historical Context: What Happened Last Time Approval Was This Low Before a Midterm?
In the 2018 midterms — when Trump’s approval stood around 41%, notably higher than his current 33% — Republicans lost control of the House of Representatives, though the party gained two Senate seats. With his current approval running meaningfully below that benchmark, political analysts and Republican strategists are expressing heightened concern about the party’s ability to defend its congressional majorities in 2026.
Market and Investment Implications
Political Risk and Sector Exposure
Historically, periods of declining presidential approval heading into a midterm election can correlate with:
- Increased policy uncertainty premium in markets, particularly for sectors sensitive to potential legislative gridlock or shifts in regulatory posture.
- Elevated volatility in sectors tied to trade and foreign policy, given the Iran conflict’s direct role in the approval decline.
- Currency and bond market sensitivity to shifting expectations about fiscal policy continuity, particularly if control of Congress appears increasingly contested.
What History Suggests About Midterm-Year Market Performance
Markets have historically shown resilience through midterm election cycles regardless of which party is expected to gain seats, often pricing in political uncertainty well ahead of the actual vote. That said, sectors with direct regulatory or fiscal exposure — energy, defense, financial services, and healthcare — tend to see the most direct repricing around shifting congressional control expectations.
Actionable Takeaways for Investors and Political Observers
- Don’t overreact to a single poll. The spread between individual polls (33%) and polling averages (around 39%) illustrates why tracking multiple pollsters and trend direction matters more than any single headline number.
- Watch the Iran conflict closely as a specific, trackable driver of both approval numbers and potential market volatility — any de-escalation or further escalation is likely to move both simultaneously.
- Consider portfolio hedging strategies around sectors with direct regulatory exposure if you expect a competitive midterm environment to increase legislative gridlock risk.
- Track generic congressional ballot polling alongside presidential approval, as it offers a more direct read on likely House and Senate outcomes than approval ratings alone.
- Maintain a diversified portfolio rather than making concentrated bets based on political forecasting, given the inherent uncertainty in translating approval polling into specific electoral or market outcomes.
Frequently Asked Questions
What is Trump’s current approval rating? Multiple polls, including Reuters/Ipsos, The Economist/YouGov, and AP-NORC, have shown Trump’s approval rating at 33% as of late August 2026, while broader polling averages like Decision Desk HQ’s show a somewhat higher figure around 39%, reflecting the spread across different polling methodologies.
Why has Trump’s approval rating declined so much in 2026? Polling data points to an unpopular and prolonged U.S. military conflict with Iran, with only 31% of Americans supporting continued military action, alongside broader economic concerns, as significant contributing factors to the decline from 47% approval at the start of his second term to 33% now.
How might low presidential approval affect the stock market ahead of the midterms? Markets have historically shown general resilience through midterm election cycles, but sectors with direct regulatory or fiscal policy exposure — such as energy, defense, financial services, and healthcare — tend to experience more direct volatility around shifting expectations for congressional control, so investors may want to monitor generic ballot polling alongside approval ratings.

US Impeachment Talk and White House Press Secretary Changes: What the Record Shows

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
AI Impact on Wages 2026: Productivity Soars, Paychecks Stagnate
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Analysis4 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025