Global Economy
America’s Economy Set to Accelerate in 2026: What Monetary-Fiscal Loosening Means for You

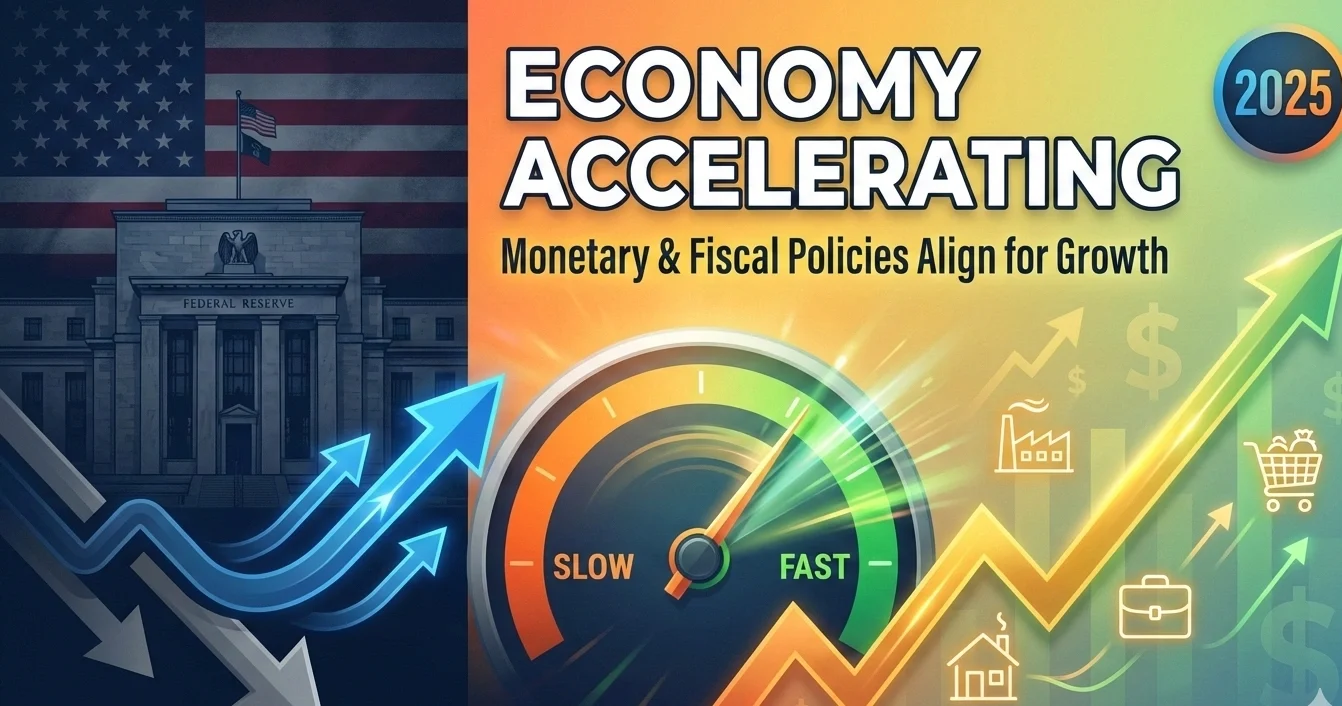
America’s economy is poised for major acceleration as monetary policy loosening combines with fiscal stimulus. Expert analysis of what this means for jobs, investments, and your financial future in 2025-2026.
Something remarkable is happening in the American economy right now. After navigating through years of inflation battles and interest rate uncertainty, we’re witnessing the formation of a powerful economic catalyst—one that only emerges when Washington’s two most influential policy levers align in the same direction.
Real GDP surged 4.3% in the third quarter of 2025, marking the strongest quarterly performance in two years. But here’s what makes this particularly significant: this acceleration is happening just as both monetary and fiscal policy are shifting toward expansion simultaneously—a coordination that historically produces outsized economic effects.
Having analyzed economic policy for over 15 years, I can tell you that these synchronized loosening cycles don’t come around often. When they do, they reshape the economic landscape in ways that create both tremendous opportunities and specific risks that every American should understand.
What is Monetary-Fiscal Loosening? [Quick Definition]
Monetary-fiscal loosening occurs when the Federal Reserve reduces interest rates or expands money supply (monetary policy) while the government increases spending or cuts taxes (fiscal policy) simultaneously. This coordinated approach pumps stimulus into the economy from both directions, typically accelerating growth, boosting employment, and increasing consumer spending. Unlike isolated policy actions, this dual approach creates multiplier effects that amplify economic activity across all sectors.
Signs of Economic Acceleration Already Emerging
The data tells a compelling story. Beyond the impressive Q3 GDP figures, several leading indicators are flashing green across the dashboard.
Consumer spending has been balanced and strong across income groups, growing around 3% from late 2023 through mid-2024. This broad-based consumption pattern suggests genuine economic momentum rather than wealth-effect distortions concentrated among affluent households.
Business confidence metrics paint an equally optimistic picture. Real new orders for core capital goods rose strongly from November to January, while surveys indicate business confidence and planned capital expenditures also increased during this period. When companies start opening their wallets for equipment and expansion, they’re signaling genuine optimism about future demand.
The labor market—often the most reliable real-time economic indicator—has shown resilience that surprised even seasoned forecasters. Payroll growth averaged 237,000 jobs from November to January, exceeding break-even pace estimates, with unemployment ticking down to 4%. These aren’t the numbers of an economy stumbling toward recession.
Perhaps most telling is the investment surge in artificial intelligence and related technologies. This isn’t speculative bubble activity—it’s productive capital deployment that enhances long-term growth potential. The AI investment boom is creating a technological foundation that could sustain above-trend growth for years.
Understanding the Monetary Policy Shift
The Federal Reserve’s pivot represents one of the most significant policy transitions in recent years. The Committee decided to lower the target range for the federal funds rate by 1/4 percentage point to 3-1/2 to 3-3/4 percent in December 2025, marking a clear shift from the restrictive stance that characterized much of 2023-2024.
But this isn’t your typical rate-cutting cycle driven by economic weakness. Instead, Fed officials are recalibrating policy as inflation pressures moderate while growth remains robust—a goldilocks scenario that allows for accommodation without reigniting price pressures.
Federal Reserve projections suggest additional rate cuts ahead as policymakers seek what they term “neutral” monetary policy—a stance that neither stimulates nor restricts economic activity. Based on current trajectories, we could see the federal funds rate settle around 3-3.5% by late 2026, down from the restrictive 5.25-5.50% range that prevailed through much of 2024.
The mechanics matter here. Lower interest rates work through multiple transmission channels. They reduce borrowing costs for businesses and consumers, making investment and spending more attractive. They boost asset prices, creating wealth effects that encourage consumption. They weaken the dollar (all else equal), supporting export competitiveness. And crucially, they ease financial conditions broadly, greasing the wheels of credit throughout the economy.
Historical precedents offer instructive lessons. During previous rate-cutting cycles—particularly those not driven by crisis conditions—the economy typically experiences a 6-12 month lag before the full stimulative effects materialize. We’re likely in the early innings of this transmission process right now.
The Fiscal Policy Component: Government Spending Returns
While monetary policy grabs headlines, the fiscal side of this equation may prove even more consequential. After years of relative restraint, federal fiscal policy is loosening substantially.
The 2025 reconciliation act represents a significant fiscal injection. The legislation reduces individual income tax liabilities and allows for full expensing of certain capital investments, projected to strengthen consumer spending and encourage private investment. Additionally, increased federal funding for defense, border security, and immigration enforcement adds direct demand to the economy.
The Congressional Budget Office estimates these changes will boost GDP growth to 2.2% in 2026, up from what would have occurred under previous law. That percentage point difference translates to hundreds of billions in additional economic activity and hundreds of thousands of additional jobs.
Infrastructure spending—authorized under the Infrastructure Investment and Jobs Act—continues flowing through state and local governments. The Bipartisan Infrastructure Law directs $1.2 trillion toward transportation, energy, and climate infrastructure projects, most distributed via state and local governments. This represents the most comprehensive federal infrastructure investment in U.S. history.
Here’s what makes infrastructure spending particularly potent as fiscal stimulus: it gets spent. Unlike tax cuts (which can be saved) or even direct payments (which vary in spending rates), infrastructure investment is guaranteed to be spent, making it extraordinarily useful for macroeconomic stabilization. Economic research consistently finds that infrastructure multipliers—the GDP increase per dollar spent—exceed those of other fiscal interventions.
The timing couldn’t be better. Infrastructure projects authorized in 2021-2022 are now hitting peak spending phases, with funds flowing to construction, materials, and labor markets across the country. This creates jobs directly while supporting demand in steel, concrete, equipment manufacturing, and dozens of related industries.
Combined Impact: When Monetary and Fiscal Policy Align
This is where things get interesting. Monetary and fiscal policy don’t simply add together—they multiply.
Think of it this way: fiscal stimulus increases demand for goods and services. That demand boost would normally push up interest rates (as increased borrowing competes for available funds) and potentially crowd out private investment. But when the Federal Reserve simultaneously cuts rates, it removes that offsetting effect. The fiscal stimulus flows through unimpeded, amplified by accommodative monetary conditions.
Historical episodes provide powerful illustrations. During the recovery from the 2008-2009 financial crisis, initial fiscal stimulus (the American Recovery and Reinvestment Act) occurred while the Fed maintained near-zero rates and engaged in quantitative easing. That coordination helped drive the longest economic expansion in American history.
Similarly, the 2020-2021 response to the COVID pandemic combined massive fiscal transfers with ultra-loose monetary policy. While that particular combination eventually contributed to inflation pressures (a risk I’ll address later), it also generated the fastest GDP recovery from recession in modern history.
Academic research backs this up. Studies examining fiscal-monetary coordination consistently find that the combined effect substantially exceeds either policy acting alone. When monetary policy accommodates fiscal expansion, fiscal multipliers can reach 1.5-2.0 or higher—meaning each dollar of government spending generates $1.50-$2.00 in total GDP growth.
The International Monetary Fund has emphasized the importance of such coordination, particularly when economic conditions support it. Right now, with inflation moderating toward target, unemployment low but stable, and growth solid, we have the ideal conditions for coordinated policy expansion.
What does this mean in practical terms? Economic forecasts project 2.5% growth in 2025, with some scenarios pushing GDP above 3% under expansionary fiscal policies. That would represent growth substantially above the long-term trend of 1.8% that prevailed before the pandemic—a meaningful acceleration that ripples through every corner of the economy.
Sector-by-Sector Analysis: Who Benefits Most
Not all sectors experience coordinated policy loosening equally. Let me break down the likely winners:
Construction and Real Estate: These interest-rate-sensitive sectors typically benefit first and most directly. Lower mortgage rates boost housing affordability, while infrastructure spending directly creates construction demand. Residential construction, commercial development, and infrastructure projects all gain tailwinds simultaneously.
Financial Services: Banks and financial institutions see net interest margins initially compress as short-term rates fall. However, increased economic activity, higher lending volumes, and improved credit quality typically more than offset this effect. Insurance companies benefit from stronger premium growth and investment returns.
Consumer Discretionary: Lower rates reduce financing costs for big-ticket purchases (vehicles, appliances, furniture) while tax cuts boost after-tax income. Retailers, restaurants, leisure companies, and consumer goods manufacturers all benefit from increased purchasing power and consumer confidence.
Technology and Innovation: The ongoing AI investment boom receives additional fuel from lower capital costs. Tech companies—particularly those requiring significant capital expenditure—find expansion projects more economically attractive. The artificial intelligence buildout represents a multi-year tailwind regardless of monetary policy, but accommodation accelerates the timeline.
Manufacturing and Industry: Infrastructure projects create direct demand for industrial materials, equipment, and components. Tax provisions favoring capital investment encourage factory modernization and capacity expansion. Export competitiveness may improve if dollar weakness materializes.
Small Businesses: This often-overlooked sector stands to gain substantially. Lower borrowing costs ease financing constraints, while stronger consumer demand lifts revenues. The National Federation of Independent Business reported rising small business optimism and increased capital expenditure plans heading into 2025.
Energy deserves special mention. Traditional fossil fuel producers benefit from economic acceleration driving energy demand, while renewable energy and grid modernization gain from infrastructure funding targeted toward climate goals. It’s one of the few sectors experiencing tailwinds from multiple policy directions simultaneously.
Risks and Considerations You Should Know
Let me be direct: this isn’t a free lunch. Coordinated monetary-fiscal loosening creates genuine risks that demand attention.
Inflation Resurgence: This represents the primary concern. With growth estimated near or possibly above long-run potential and a full-employment labor market, risks to inflation skew to the upside. If demand growth outpaces the economy’s productive capacity, price pressures could reignite.
The Federal Reserve watches inflation expectations obsessively for good reason. If households and businesses begin expecting sustained higher inflation, that expectation becomes self-fulfilling as workers demand compensating wage increases and companies preemptively raise prices. Breaking entrenched inflation expectations requires painful monetary tightening—the Volcker-era experience of the early 1980s taught that lesson brutally.
Current inflation readings show moderation but remain above the Fed’s 2% target. Tariff-related price pressures add complexity, potentially pushing consumer prices higher even as underlying demand-driven inflation cools. The pass-through from tariffs remains uneven, creating measurement challenges that complicate policy decisions.
Debt Sustainability: The Congressional Budget Office projects the federal deficit at $1.9 trillion in fiscal 2025, growing to $2.7 trillion by 2035. Those figures represent 6.2% and 5.2% of GDP respectively—historically elevated levels during economic expansion.
Rising debt burdens create multiple vulnerabilities. They reduce fiscal space to respond to future recessions or crises. They increase interest expense as a share of the budget, crowding out other spending priorities. And eventually, they could trigger concerns about fiscal sustainability that push up interest rates independent of Fed policy.
Some economists argue that current debt levels remain sustainable given America’s reserve currency status and strong institutional framework. Others warn we’re approaching dangerous territory. What’s clear is that the fiscal loosening occurring now reduces the margin for error.
Global Economic Headwinds: The United States doesn’t operate in isolation. Europe faces growth challenges and potential debt sustainability concerns. China grapples with property sector distress and deflationary pressures. Geopolitical tensions and trade policy uncertainties create downside risks to global growth that could spillback to American shores through trade and financial channels.
A strong dollar—likely if the Fed cuts less aggressively than other major central banks—could widen the trade deficit and hurt export-oriented industries. Financial market volatility stemming from international developments could tighten domestic financial conditions regardless of Fed policy.
Political and Policy Uncertainties: Economic policy rarely follows neat, predictable paths. Political dynamics could alter fiscal trajectories. Trade policies might shift. Regulatory changes could affect specific sectors dramatically. The 2026 midterm elections and positioning for 2028 inject additional uncertainty.
Business leaders consistently cite elevated uncertainty as a concern tempering investment plans. That uncertainty itself can become self-fulfilling if it causes businesses to postpone decisions and households to increase precautionary savings.
What This Means for Businesses and Investors
If you’re running a business or managing investments, this environment demands strategic positioning.
For Business Leaders:
The case for accelerating planned investments strengthens considerably. Lower borrowing costs reduce capital project hurdle rates, while stronger demand growth improves revenue projections. Companies that move decisively to expand capacity, upgrade technology, or enter new markets while financing remains attractive may build competitive advantages that persist for years.
Talent acquisition and retention deserve renewed focus. As labor markets tighten—a likely outcome if growth accelerates as projected—competition for skilled workers intensifies. Companies that invest in compensation, training, and workplace quality position themselves to attract talent that drives long-term success.
Supply chain resilience remains critical despite cyclical strength. The past several years taught painful lessons about concentration risk and just-in-time vulnerabilities. Growth environments create opportunities to diversify suppliers and build redundancy without sacrificing margins.
For Investors:
Asset allocation deserves fresh evaluation. Traditional bonds face headwinds in this environment—inflation risk and eventual rate increases (once the cutting cycle completes) threaten fixed-income returns. Equity exposure makes sense given growth acceleration, but concentration risks loom large given recent market leadership narrowness.
Sector rotation opportunities abound. Early-cycle beneficiaries (financials, industrials, materials) typically outperform as coordinated policy loosening takes hold. Small-cap stocks often show particular strength given their domestic revenue orientation and financial leverage to rate declines.
Real assets provide inflation hedges if price pressures resurface. Infrastructure funds, real estate investment trusts, commodities, and Treasury Inflation-Protected Securities all offer varying degrees of inflation protection while participating in growth.
International diversification shouldn’t be abandoned despite U.S. outperformance. Currency effects, valuation disparities, and different cycle positioning across regions create opportunities beyond American borders.
Dollar-cost averaging and systematic rebalancing become more valuable, not less, as uncertainty remains elevated. Trying to time cyclical turns perfectly rarely succeeds; maintaining disciplined, diversified exposure wins over longer horizons.
What This Means for Everyday Americans
Here’s the bottom line for your personal finances and economic well-being:
Employment Outlook: Job prospects look strong. Output multipliers around 1.5 suggest each $100 billion in infrastructure spending boosts employment by over 1 million workers. Combined with other fiscal stimulus and accommodative monetary policy, job creation should remain robust. Unemployment could trend toward 3.5-4.0% if growth accelerates as projected.
This translates to worker leverage. Labor shortages typically drive wage growth as employers compete for talent. If you’re considering career moves, negotiating raises, or exploring new opportunities, economic conditions favor workers more than they have in years.
Wage Growth Expectations: Wage gains should outpace inflation, delivering real purchasing power increases for most workers. Professional and technical fields—particularly those related to AI, infrastructure, and high-growth sectors—likely see strongest compensation growth. Even service and manual labor markets tighten as construction and logistics demand increases.
That said, wage growth varies substantially by geography, industry, and skill level. Investment in education, training, and skill development pays off more during growth phases as employers value productivity-enhancing capabilities.
Cost of Living Considerations: This represents the counterbalance. While incomes rise, so might prices—particularly for housing, services, and goods facing capacity constraints. The inflation-wage race determines whether living standards improve or stagnate.
Housing deserves particular attention. Lower mortgage rates improve affordability on one hand, but accelerated demand combined with constrained supply pushes prices higher. The net effect varies dramatically by local market—high-cost coastal cities face different dynamics than growing Sun Belt metros or rural areas.
Housing Market Implications: Mortgage rates likely trend lower over the next 12-18 months as Fed cuts flow through to longer-term rates. That improves purchasing power for buyers substantially—a one percentage point decline in rates increases buying power by roughly 10%.
However, home price appreciation may offset much of this benefit. The benchmark home price index is expected to rise 3.7% in 2025 and 3.3% in 2026, with stronger growth in outer years. First-time buyers and those in hot markets face particular challenges.
For homeowners with existing mortgages, refinancing opportunities emerge. Those locked into 6-7% rates can potentially save hundreds monthly by refinancing into 5-6% (or lower) mortgages. Calculate break-even timelines carefully accounting for closing costs.
Credit and Debt Management: Lower interest rates cut both ways. Credit card rates, auto loans, and personal loans all typically decline (though often with lags). This makes debt more manageable and consumption more affordable.
However, easy credit environments encourage over-leverage. Just because you can borrow doesn’t mean you should. Maintain emergency funds, limit high-interest debt, and avoid assuming debt loads that become problematic if economic conditions shift.
Retirement Planning: Growth environments benefit retirement portfolios—both through higher returns and improved Social Security/pension funding. However, don’t abandon risk management. Diversification, appropriate asset allocation for your time horizon, and regular rebalancing remain critical.
Those nearing retirement face particular considerations. Locking in gains through bond ladders or annuities makes sense for the portion of portfolios needed for near-term spending. Let equity exposure work for longer-term needs while protecting against sequence-of-returns risk.
The Road Ahead: Scenarios and Timeline
Let me sketch three plausible scenarios for how this unfolds:
Base Case (60% probability): Coordinated policy loosening drives GDP growth to 2.5-3.0% through 2026. Unemployment drifts to 3.7-4.0%. Inflation moderates to 2.2-2.5%, remaining slightly above target but not accelerating. The Fed completes its cutting cycle around 3.25-3.50% by late 2026, then pauses. Fiscal policy continues expansionary through 2025-2026 before modest consolidation pressures emerge. This scenario delivers solid growth without reigniting serious inflation concerns.
Upside Case (25% probability): Productivity gains from AI adoption and infrastructure modernization exceed expectations. Growth accelerates to 3.0-3.5%, unemployment drops below 3.5%, but inflation stays contained at 2.0-2.3% due to productivity offsetting demand pressures. The Fed cuts more aggressively, reaching 2.75-3.00%. Stock markets surge 20-30%. This becomes a genuine economic boom reminiscent of the late-1990s technology expansion.
Downside Case (15% probability): Policy coordination misfires. Demand stimulus overwhelms productive capacity. Inflation accelerates back toward 3.5-4.0%, forcing the Fed to reverse course and raise rates again. Growth slows sharply to 0.5-1.0% or potentially contracts. This scenario involves policy error—either too much fiscal stimulus, too much monetary accommodation, or both—creating the stagflation-lite conditions policymakers desperately want to avoid.
Timeline matters. The transmission mechanisms from policy changes to economic outcomes operate with lags. Monetary policy changes typically take 6-12 months to achieve full impact. Fiscal policy effects vary—tax cuts hit quickly while infrastructure spending builds gradually over years.
Expect the most visible acceleration during the second half of 2025 and first half of 2026 as multiple policy streams flow simultaneously. By late 2026-2027, we’ll likely enter a consolidation phase as policies stabilize and attention shifts to sustainability questions.
Final Thoughts: Opportunity with Open Eyes
America’s economy stands at an inflection point. The alignment of monetary and fiscal policy toward expansion creates genuine momentum that should deliver years of solid growth, strong employment, and rising prosperity for millions of Americans.
This isn’t merely my optimism speaking—it’s what economic history, current data, and policy trajectories consistently indicate when conditions align as they do today. The fundamentals supporting acceleration are real: technological innovation driving productivity, infrastructure investment addressing decades of underinvestment, business and consumer confidence improving, and policy coordination providing cyclical thrust.
Yet optimism should never slide into complacency. The risks outlined above—inflation, debt, global uncertainty, policy errors—aren’t hypothetical concerns but genuine possibilities that demand respect and preparation. Success requires navigating these crosscurrents skillfully at both policy and personal levels.
For policymakers, the challenge involves threading a narrow needle: providing enough accommodation to support growth without reigniting inflation, maintaining fiscal stimulus without creating unsustainable debt dynamics, and preserving flexibility to respond to surprises. The Federal Reserve has experience managing this balancing act, though perfect execution remains elusive.
For businesses, this environment rewards bold but prudent action—investing in growth while maintaining resilience, expanding capacity while controlling leverage, competing aggressively for talent while managing costs.
For individuals and families, the opportunity involves positioning for prosperity while protecting against setbacks. Participate in asset appreciation, pursue career advancement, improve skills, make thoughtful consumption and housing decisions—but maintain emergency funds, manage debt responsibly, and diversify risks.
The next two years present a potentially golden window for American economic performance. Whether we fully capitalize on this opportunity depends on policy execution, business decisions, and how millions of Americans navigate their personal economic situations.
One thing seems certain: standing still isn’t a viable strategy. This environment punishes complacency but rewards those who prepare, adapt, and position intelligently for the acceleration ahead.
Frequently Asked Questions
When will I start seeing the economic benefits in my daily life?
Most Americans should notice effects within 3-6 months. Lower interest rates flow through to consumer loans fairly quickly. Job market improvements materialize within 6-12 months as businesses respond to stronger demand. Wage increases typically lag 9-18 months as labor markets tighten.
Should I wait to buy a house until rates drop further?
Generally no—trying to time the exact market bottom rarely works. If you find suitable housing at prices you can afford with current rates, buying makes sense. You can always refinance later if rates drop further. Waiting risks home price appreciation offsetting any rate savings.
How can I protect myself against inflation if it returns?
Diversify into inflation-protected assets (TIPS, real estate, commodities). Focus on developing skills that command premium wages. Limit fixed-rate debt that becomes more valuable during inflation. Consider cost-of-living adjustments in salary negotiations. Maintain some international exposure given dollar vulnerability during inflation episodes.
Is now a good time to start a business?
Economic expansions create favorable conditions for entrepreneurship—strong consumer demand, available capital, robust labor supply for hiring. However, assess your specific market carefully. Access to startup capital should improve as rates decline and investor risk appetite increases.
Will Social Security and Medicare remain secure?
Short-term (next 5-10 years), yes. Longer-term sustainability requires reforms given demographic trends. Economic growth helps by increasing tax revenues, but doesn’t eliminate structural challenges. Stay informed about policy discussions and plan for potential benefit modifications.
Sources: Federal Reserve, Congressional Budget Office, U.S. Bureau of Economic Analysis, U.S. Department of Treasury, International Monetary Fund, Deloitte Insights, Goldman Sachs Research, EY Economics, Richmond Federal Reserve, World Bank, Economic Policy Institute, and peer-reviewed academic journals.
Disclaimer: This article provides educational information and analysis. It does not constitute financial advice, investment recommendations, or predictions of future performance. Consult qualified professionals regarding your specific financial situation. Economic forecasts involve significant uncertainty and actual outcomes may differ substantially from projections discussed.


Global economic growth in 2026 is growing increasingly uneven, capital is becoming far more sensitive to financing costs, and discerning a compelling narrative from an investable asset price is crucial. Rather than promising guaranteed returns, this guide outlines essential research methods and key market risks. While the IMF’s October 2026 outlook projects global growth at 3.1% and inflation at 4.7%, its financial-stability report cautions that underlying vulnerabilities persist beneath current market resilience.
Key takeaways
- Match each investment decision to its time horizon, currency and ability to withstand losses.
- Separate observable earnings or contractual cash flows from optimistic forecasts.
- Compare diversification, fees, taxes, liquidity and regulatory restrictions before committing capital.
- Track primary institutional evidence and update assumptions when conditions change.
- Readers in Pakistan should consider rupee exposure and availability of regulated investment channels.
Why this matters now
The central question behind global recession risk 2026 is not merely what may happen next. It is which economic mechanisms could change cash flow, purchasing power or risk. The Bank for International Settlements’ 2026 review describes an economy supported by technological investment but constrained by geopolitical and fiscal pressures. A robust financial plan must therefore survive both a favourable and an adverse scenario.
Start with the baseline, not the frightening headline
The IMF forecast 3.1% global growth in 2026 and 3.4% in 2027, implying continued expansion under its baseline rather than an outright worldwide recession. Nevertheless, forecasts can miss shocks. Investors should monitor a basket of labour, credit, trade, earnings and inflation indicators rather than treating any single signal as destiny. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Yield curves and interest-rate expectations
An inverted yield curve can reflect expectations of weaker activity or future interest-rate cuts, but term premiums and central-bank balance sheets complicate interpretation. A subsequent steepening may accompany either improving growth expectations or falling short-term rates during a downturn. Context matters more than a mechanical threshold. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Credit spreads and lending conditions
Widening differences between risky and safe bond yields can reveal anxiety about defaults and funding. Banks tightening lending standards may reduce business investment and household spending. Monitor multiple jurisdictions: financial stress in one country need not translate into a worldwide contraction, but global funding networks can spread pressure. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Jobs, production and trade
Unemployment changes, hours worked, purchasing-manager surveys and industrial production indicate demand and business confidence. Trade shipment data add external perspective. Monthly releases can be revised, and some indicators lag turning points. Use three-month trends alongside annual comparisons to avoid mistaking seasonal noise for a regime change.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
What investors in Pakistan should monitor
Foreign remittances, import payments, export orders, the rupee and international oil prices transmit global stress to domestic conditions. Preserve liquidity for essential obligations and review high-leverage exposure. In uncertain markets, a disciplined allocation and rebalancing policy is usually more defensible than an all-or-nothing recession bet. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Comparison and decision framework
| Question | Stronger evidence | Warning sign |
|---|---|---|
| What drives returns? | Audited cash flows, clear contract or transparent index | Undefined or projected returns |
| What can go wrong? | Explicit scenario and downside analysis | Claims of guaranteed gains |
| Is it affordable to hold? | Low transparent fees and adequate liquidity | Leverage, costly spreads or lockups |
| Is access legitimate? | Appropriate licensing and clear legal rights | Unverified brokers or custody |
| Is the exposure diversified? | Multiple independent sources of return | One company, sector or currency |
What it means for Pakistani savers and investors
A Pakistani reader faces both international investment risk and local purchasing-power risk. For example, a foreign asset can rise in US-dollar terms while the rupee conversion and transaction costs alter the realized local outcome. The opposite can also occur. Record the starting exchange rate, applicable taxes, custody charges and capital-transfer restrictions, and confirm current requirements with the State Bank of Pakistan and the relevant securities regulator. Overseas access should not be assumed universally available.
An emergency reserve, expensive consumer debt and near-term family obligations deserve attention before any speculative allocation. A portfolio that cannot meet a sudden cash requirement may force sales at the worst moment. The objective is not to remove risk—impossible in markets—but to choose risks that fit the investor’s actual liabilities.
Risks, limitations and uncertainty
Institutional forecasts are conditional and can change after policy decisions, commodity shocks, conflict escalation or unexpectedly weak earnings. Historic correlations are not binding promises about future asset performance. The analysis does not provide live stock prices, current investment product quotes, real-time exchange rates or individualized tax advice. Prices, regulations and product eligibility should be checked on the transaction date.
Frequently asked questions
Is this a guaranteed investment opportunity?
No. Every financial asset or strategy involves uncertainty. The existence of a popular investment theme is not evidence that an individual security is fairly priced.
What should beginners examine first?
Understand the product, the financial loss you could tolerate, fees and liquidity. Verify the provider and decide whether the money may be needed soon.
How do interest rates affect the analysis?
They influence financing costs, discount rates, exchange rates and demand. The effect differs by sector, maturity and business balance sheet.
Can Pakistani residents invest in foreign markets?
Access depends on current foreign-exchange, banking, brokerage, securities and tax rules, and on the investor’s individual circumstances. Check current regulations and regulated providers rather than assuming access.
How often should this analysis be refreshed?
Review institutional economic releases monthly and re-evaluate immediately after material earnings, regulatory or policy changes. Avoid reacting mechanically to every daily market movement.
Is diversification enough to prevent losses?
No. Diversification may reduce company-specific risk but cannot eliminate broad market, currency, inflation or systemic risks.
Conclusion
Sound financial decisions begin with verifiable evidence, reasonable valuation, awareness of uncertainty and a plan that survives adverse outcomes. Readers should compare multiple independent sources and avoid letting a compelling headline substitute for due diligence.
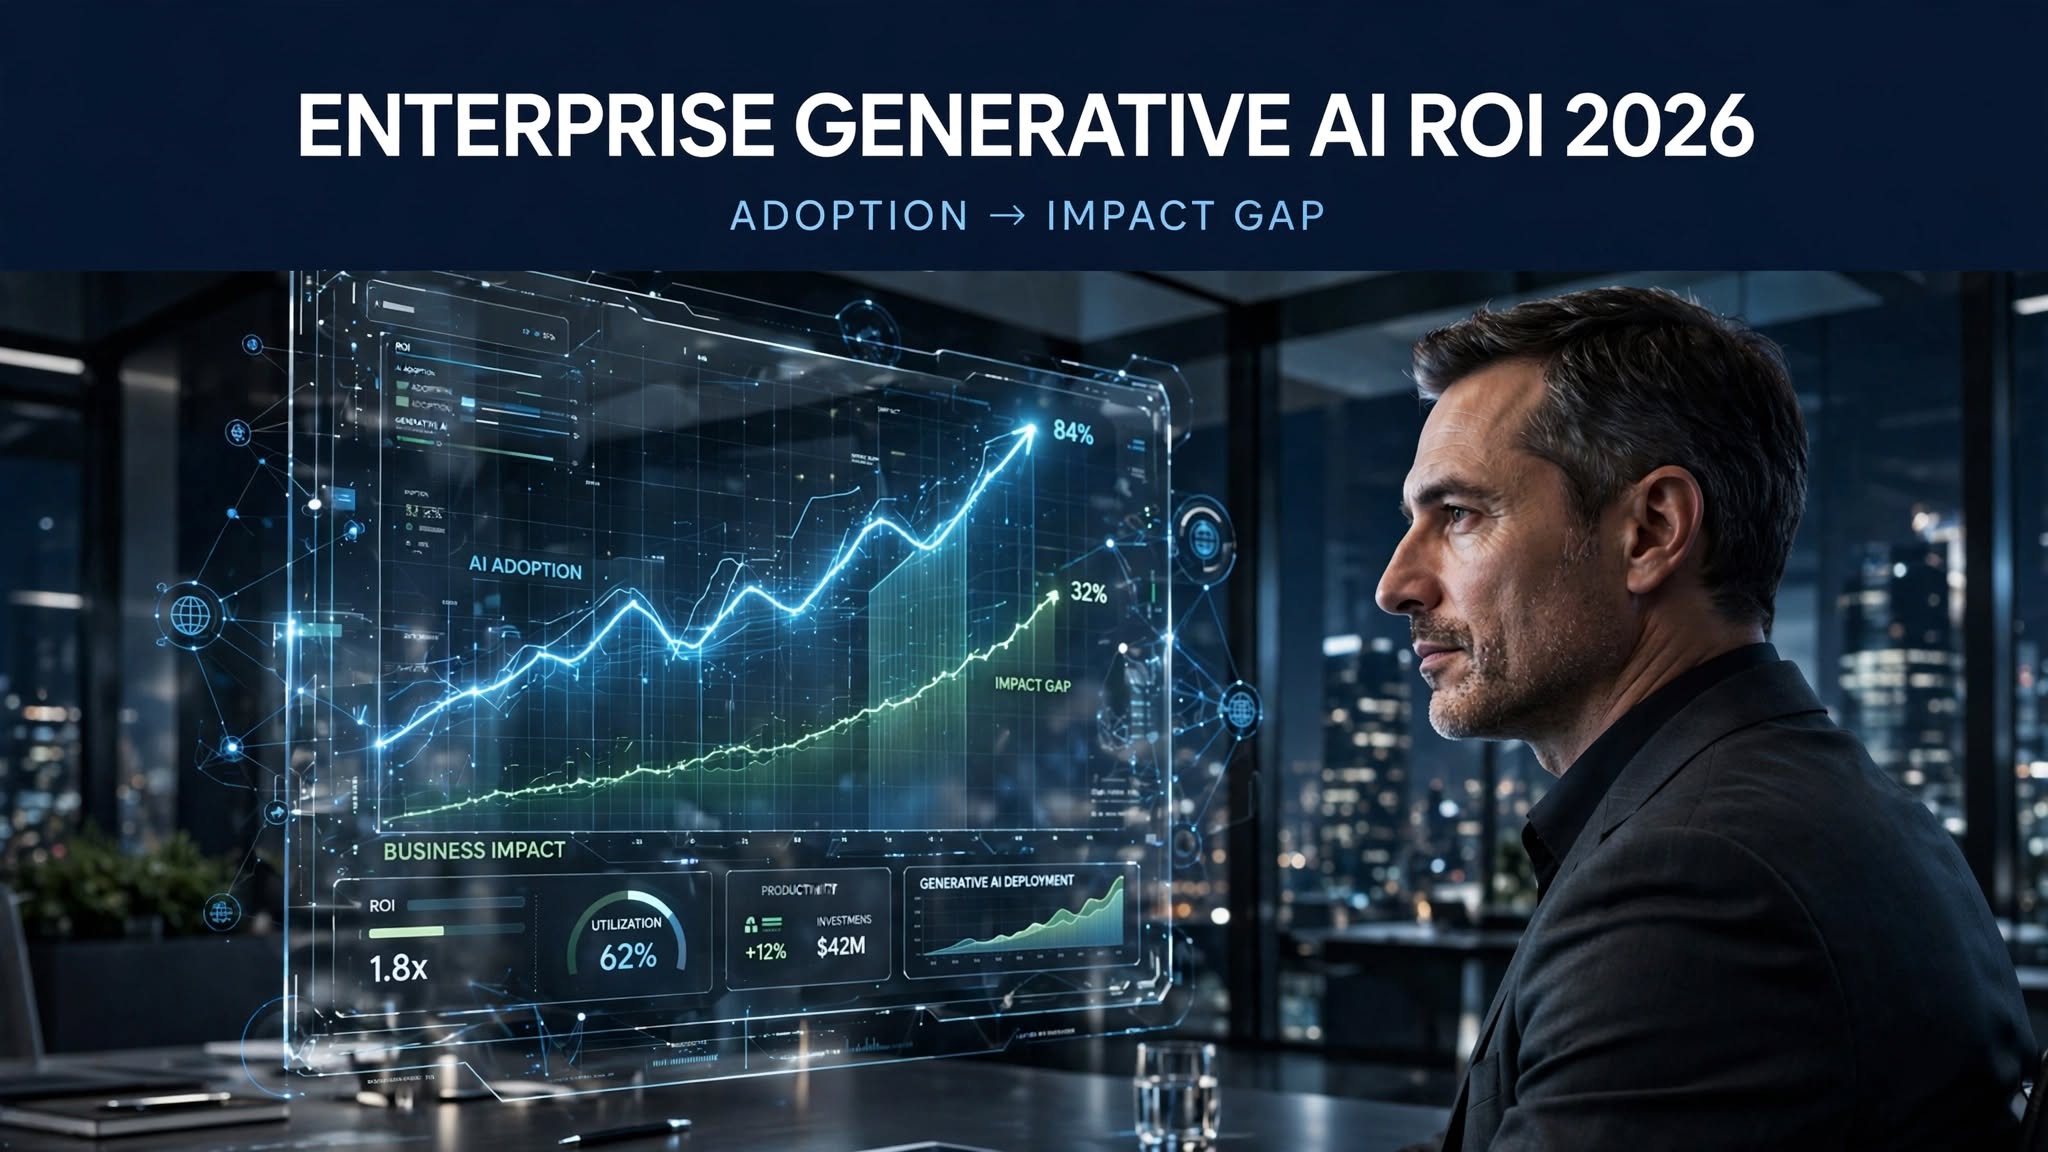
Enterprise generative AI in 2026 presents a genuine paradox: adoption is nearly universal, individual productivity gains are well-documented and real, and yet the majority of organizations still cannot point to measurable enterprise-wide financial return. Understanding that gap — not simply citing adoption statistics — is now the central strategic question for any organization evaluating its AI investment.
The Adoption-to-Impact Gap, By the Numbers
| Metric | 2026 Data | Source |
|---|---|---|
| Organizations using AI in at least one business function | 88–90% | McKinsey / Stanford AI Index |
| Organizations reporting generative AI use specifically | 70–72% | Stanford AI Index / Menlo Ventures |
| CEOs reporting “nothing” or zero measurable ROI | 56% | PwC January 2026 CEO Survey (n=4,454) |
| Organizations seeing significant ROI from generative AI | 29% | 2026 enterprise adoption survey |
| AI projects moving to production achieving positive ROI within 12 months | 44% | Forrester |
| Organizations that have scaled AI beyond pilot stage | ~33% | Multiple 2026 surveys |
| Enterprise generative AI spending growth, 2024→2025 | +222%, reaching $37 billion | Menlo Ventures |
Axis Intelligence Research’s AI Productivity Gap Index (APGI) scores the 2026 landscape at 68.4 out of 100, placing enterprise AI firmly in “Large Gap” territory — worse than the documented adoption-to-impact gaps observed during the 2011–2014 cloud computing adoption cycle or the 2013–2016 enterprise social media adoption cycle. This is a genuinely useful historical anchor: it suggests the current gap between AI deployment and AI value capture, while frustrating to executives, is not unprecedented for a fast-diffusing enterprise technology — but it is currently worse than the two most recent comparable technology cycles.
Why Individual Gains Aren’t Converting to P&L Impact
The productivity gains at the individual level are genuinely substantial and well-measured:
- Active Microsoft 365 Copilot users save 14 to 26 minutes per day, per Microsoft’s own early-user research and a UK government trial respectively.
- Active OpenAI Enterprise users save 40 to 60 minutes per day, according to Goldman Sachs’ reporting of OpenAI usage data from December 2025.
- Individual productivity gains from generative AI tools reach 5x in documented cases, per 2026 enterprise adoption survey data.
- Accenture estimates the average productivity value of generative AI tools at $7,800 per employee per year for knowledge workers.
The conversion failure happens at the aggregation layer. ModelOp’s 2026 survey of 100 senior AI enterprise leaders found that two-thirds of AI-spending organizations rely on estimates of time saved rather than measured financial outcomes to assess ROI — meaning most organizations cannot actually trace individual time savings through to a documented P&L line, even when the underlying time savings are real. PwC’s April 2026 AI Performance Study identifies what separates the top-performing 20% of organizations: they pursue growth (new products, market expansion) alongside efficiency, rather than treating AI purely as a cost-reduction lever — a strategic distinction that appears to be the single strongest predictor of realized enterprise value.
What’s Actually Driving the Failure Modes
Across the 2026 survey literature, five recurring root causes explain why individual productivity gains fail to scale into enterprise transformation:
- Isolated tactical implementation rather than enterprise-wide deployment — pockets of AI usage within specific teams that never integrate into core workflows or systems of record.
- Insufficient data quality and infrastructure — Gartner projects that 60% of AI projects unsupported by AI-ready data will be abandoned through 2026, reinforcing that the primary blocker is data readiness, not model capability.
- Misalignment between AI initiatives and business strategy — AI deployed because it’s available, not because it’s mapped to a specific, measurable business outcome.
- Inadequate change management — 54% of C-suite executives admit adopting AI is “tearing their company apart” internally, reflecting genuine organizational friction rather than pure technology limitation.
- Lack of clear measurement frameworks — the two-thirds of organizations relying on estimated rather than measured outcomes noted above is both a symptom and a cause of this failure mode.
Return-on-Investment Benchmarks Where They Exist
Despite the aggregate gap, credible ROI benchmarks do exist for organizations that have moved past pilot stage:
- McKinsey Global AI Survey: 5.8x average ROI on AI investment within 14 months of production deployment.
- IDC/Microsoft: 3.7x average return per $1 invested in generative AI.
- Forrester Total Economic Impact studies: cite cases of 333% ROI with a six-month payback period for organizations using enterprise-grade platforms with structured deployment.
- Google Cloud’s ROI of AI research: 74% of executives whose organizations use generative AI report ROI within the first year, rising to 88% among agentic-AI early adopters specifically — suggesting agentic (task-executing) AI deployments may be converting to measured ROI faster than general-purpose generative AI usage.
- KPMG’s Q1 2026 AI Quarterly Pulse Survey: 62% of U.S. organizations have achieved measurable ROI or expect it within the next 12 months.
The dispersion across these figures (3.7x to 5.8x average ROI, but also 56% of CEOs reporting zero ROI) is itself the key finding: ROI in enterprise AI is currently bimodal, not normally distributed — organizations either are capturing substantial, measured returns through structured deployment, or are capturing effectively none, with comparatively few landing in a modest-middle-ground outcome.
The Security Governance Dimension: Shadow AI
Parallel to the ROI question, 2026 has been the year enterprise AI security risk moved from theoretical to quantified and regulatory:
- IBM’s Cost of a Data Breach Report 2026 (published July 29, 2026, studying 602 breached organizations across 17 industries and 16 countries) found shadow AI — unauthorized, unapproved AI tool usage — involved in 43% of security incidents, up sharply from roughly one in five the prior year.
- Shadow AI increases average breach costs by $670,000 per incident and adds roughly 10 days to breach identification and containment timelines, per IBM’s data.
- Visibility remains the core governance failure: only 25% of organizations report comprehensive visibility into how employees actually use AI tools, while 35% describe shadow AI usage as pervasive or widespread within their organization.
- Only 37% of organizations have formal AI governance policies in place — meaning 63% are currently operating without documented guardrails, per IBM 2025 data cited across multiple 2026 governance reports.
Regulatory Timeline: The EU AI Act Compliance Clock
Governance is no longer purely a voluntary best-practice question. Under the EU AI Act implementation timeline, most remaining provisions began applying August 2, 2026, with member states now required to maintain at least one national AI regulatory sandbox. A further compliance milestone follows August 2, 2027, when Article 6(1) obligations and legacy general-purpose model compliance requirements take effect. For any organization processing EU data or serving EU customers, ungoverned AI use is now a documented regulatory exposure, not solely a security concern.
Governance Frameworks Auditors Increasingly Expect
Three frameworks have emerged as the reference points defining “reasonable care” in enterprise AI governance:
- NIST AI Risk Management Framework, structured around four functions: Govern, Map, Measure, and Manage.
- ISO/IEC 42001, the certifiable AI management system standard (published December 2023, now increasingly referenced in enterprise audits).
- NIST Cybersecurity Framework 2.0, which added a dedicated Govern function mapping directly onto AI-specific oversight requirements.
What Separates High-ROI Organizations from the 56% Reporting Nothing
Synthesizing across the 2026 research base, the organizations capturing measured, enterprise-wide ROI share a consistent pattern:
- They pursue growth use cases alongside efficiency, not efficiency alone (PwC’s top-performing-20% finding).
- They deploy approved AI tools with real-time coaching rather than blanket bans, which one healthcare-system case study found reduced unauthorized shadow AI usage by 89% while still capturing productivity gains — demonstrating that governance and productivity are not inherently in tension when implemented well.
- They measure financial outcomes directly rather than relying on estimated time-savings as a ROI proxy.
- They treat AI governance as infrastructure, not paperwork — Gartner projects AI governance spending will reach $492 million in 2026 and surpass $1 billion by 2030, reflecting genuine budget commitment rather than compliance-theater spending among leading organizations.
Bottom Line
Enterprise generative AI in 2026 has achieved near-universal adoption and well-documented individual productivity gains — but the majority of organizations still cannot convert those gains into measured, enterprise-wide financial return, with 56% of CEOs reporting zero measurable ROI even as documented benchmarks show 3.7x to 5.8x returns are achievable. The differentiator is not the technology itself but organizational execution: structured deployment paired with genuine financial measurement, growth-oriented rather than purely cost-focused use cases, and governance frameworks robust enough to manage the shadow AI risk now implicated in 43% of security incidents — all under an EU AI Act compliance clock that started running in August 2026.

On September 2, 2026, the UN Environment Programme published a report that treated something once framed as a worst-case risk as a settled outcome: the world will pass 1.5°C of warming. “Limiting Overshoot: Navigating Exceedance of 1.5°C and Pathways Towards Return” marks a deliberate shift in framing, from preventing a threshold breach to managing one already underway — with direct, quantified consequences for climate finance, carbon-removal markets, and the economics of adaptation that businesses and investors now need to plan around.
Key Takeaways
- UNEP’s September 2, 2026 report puts best-case peak warming at 1.8°C even under the most optimistic current government pledges, with a median of around 2.6°C by 2100 (range 1.9°C–3.6°C) under current policies — treating overshoot of the Paris Agreement’s 1.5°C goal as effectively locked in.
- The remaining global carbon budget for a 50% probability of staying within 1.5°C is roughly 130 gigatonnes of CO2 as of 2026 — at current annual emissions of nearly 40 GtCO2, this budget could be exhausted within approximately three years.
- Global disaster losses, including broader economic and ecological damage, already exceed $2.3 trillion annually, according to the UN’s 2026 climate report, while international climate finance reached just $136.7 billion in 2024 — a gap of well over an order of magnitude between damage and financing.
- Carbon dioxide removal (CDR) at the scale needed to return to 1.5°C will cost trillions of dollars, with per-tonne costs estimated at over $100 and ranging up to $1,000 or more depending on the removal method, according to the State of Carbon Dioxide Removal’s Third Edition (2026).
- The Fund for Responding to Loss and Damage held pledges of only around $800 million as of late 2025, a figure researchers describe as dramatically short of documented developing-country needs — underscoring the financing gap at the center of overshoot economics.
From Prevention to Management: A Deliberate Reframing
UNEP’s own annual Emissions Gap Report has tracked the shortfall between climate pledges and required pathways since 2010, but the September 2026 “Limiting Overshoot” report represents a structural change in framing rather than a change in the underlying science. Rather than treating a breach of 1.5°C as an endpoint or failure state, the report proposes an “overshoot, peak, and decline” framework: limiting the maximum level of warming reached, then working to enable a gradual return toward safer conditions over subsequent decades. As UN Secretary-General António Guterres put it in comments accompanying the report’s launch, humanity must pursue “an overshoot of ambition” — accelerating fossil fuel phaseout, slashing methane pollution, and protecting land, forests, and oceans simultaneously, rather than sequencing mitigation and adaptation as separate phases.
The report’s own numbers make clear why this reframing was considered necessary: even the most optimistic scenario incorporating all current government pledges puts expected peak warming at 1.8°C, while continuation of current policies (without stronger pledges) produces a median projection of roughly 2.6°C by century’s end, with a plausible range extending to 3.6°C. Human-induced warming is already approaching 1.4°C and increasing at roughly 0.25°C per decade — a trajectory that leaves essentially no realistic path to avoiding at least a temporary breach of the 1.5°C threshold.
The Carbon Budget Arithmetic
The remaining global carbon budget for a 50% probability of holding warming within 1.5°C stands at roughly 130 gigatonnes of CO2 as of 2026. Against current annual global emissions of nearly 40 gigatonnes, this budget could be exhausted within approximately three years at present emissions rates — a timeline that explains why the report treats exceedance as the base case for planning purposes rather than a tail risk. This arithmetic is central to why the report’s “overshoot, peak, and decline” framework requires not merely emissions reduction but active carbon dioxide removal (CDR) at scale to eventually bring atmospheric concentrations back down, rather than emissions reduction alone.
Tipping Point Risk: The Non-Linear Cost of Overshoot Duration
The UNEP report identifies four specific tipping elements where sustained warming above 1.5°C raises materially elevated risk: the West Antarctic Ice Sheet, the Greenland Ice Sheet, the Atlantic Meridional Overturning Circulation (AMOC), and the climate-biosphere system of the Amazon rainforest. Notably, the report deliberately declines to attach specific temperature thresholds to these tipping points, instead emphasizing that risk increases with both the degree and — critically for economic planning — the duration of overshoot. This duration-sensitivity is central to the report’s economic logic: the longer warming remains above 1.5°C, the greater the cumulative risk of triggering one or more of these systems, with some — such as AMOC weakening — showing model-projected recovery only on a timescale of centuries even if peak warming is later reduced.
This non-linearity matters directly for climate finance and insurance-sector risk modeling: a framework that treats overshoot duration, not just peak magnitude, as the key risk variable implies that near-term emissions reduction and carbon removal investment carry outsized value in limiting tail risk, even if 1.5°C itself is no longer avoidable as a peak.
The Financing Gap: Quantifying the Shortfall
The UN’s broader 2026 climate reporting places global disaster losses — including direct economic damage and broader ecological costs — at over $2.3 trillion annually. Against this figure, international climate finance flows reached just $136.7 billion in 2024, a gap exceeding an order of magnitude between documented damage and available financing. Climate officials have consistently framed this financing not as charitable transfer but as a protective investment against larger future losses — arguing that extreme weather, disrupted agriculture, damaged infrastructure, and displaced populations carry costs to the global economy that substantially exceed the cost of preventive action.
The financing gap is starkest in the Loss and Damage architecture specifically: the Fund for Responding to Loss and Damage held pledges of only around $800 million as of late 2025, against developing-country needs that researchers have estimated run dramatically higher — a mismatch the UNEP report explicitly identifies as an area requiring strengthened international financial commitment, particularly given the report’s emphasis on Common but Differentiated Responsibilities and Respective Capabilities (CBDR-RC) as a governing principle for how overshoot’s costs should be distributed.
The Economics of Carbon Dioxide Removal
Because the “overshoot, peak, and decline” pathway requires active carbon removal to eventually bring warming back toward 1.5°C, CDR economics have become directly material to climate finance planning in a way they were not when 1.5°C avoidance still seemed achievable through emissions reduction alone. The State of Carbon Dioxide Removal’s Third Edition (2026) estimates that many CDR approaches cost over $100 per tonne of CO2 removed, with some methods running $1,000 or more — and that deploying CDR at the annual billion-tonne scale required to meaningfully support a return to 1.5°C will cost trillions of dollars in cumulative terms, posing a genuine financial constraint on the pathway’s feasibility.
UNEP’s 2026 analysis separately and explicitly rules out solar radiation management (SRM) as a viable substitute or complement at this stage, characterizing the evidence base as limited, largely theoretical, and concentrated in a handful of countries — with significant equity implications given that SRM deployment location could produce regionally uneven climate impacts. This effectively narrows the overshoot-management toolkit to emissions reduction plus CDR, reinforcing the trillion-dollar-scale financing requirement rather than offering a lower-cost technological alternative.
Heat, Labor, and Productivity: An Underpriced Economic Risk
Beyond direct disaster losses, the UNEP report highlights heat-related productivity losses as a specific and growing economic risk channel: increasing humid heat is projected to significantly reduce outdoor labor capacity, deepening economic losses specifically in vulnerable, often lower-income countries with large outdoor and agricultural workforces. This risk channel — distinct from more visible disaster-loss categories like flooding or storm damage — represents a slower-moving but potentially larger cumulative economic cost that current climate finance flows are not clearly calibrated to address.
Implications for ESG Finance and Corporate Climate Strategy
- Adaptation finance requires a step-change, not incremental growth. The UN Secretary-General has specifically called on developed countries to triple adaptation finance and ensure it reaches those most at risk — a target that implies current adaptation financing trajectories are viewed as fundamentally inadequate given the now-explicit overshoot scenario.
- CDR investment carries genuine but expensive strategic value. With per-tonne CDR costs ranging from roughly $100 to over $1,000, ESG and climate-focused investors should differentiate between lower-cost, more scalable removal methods and premium, higher-certainty approaches when evaluating portfolio exposure to carbon removal markets.
- Loss and Damage exposure should be modeled as a growing, underfunded liability. With pledged funding around $800 million against dramatically larger documented needs, businesses operating in climate-vulnerable regions should anticipate continued political and financial pressure for expanded corporate and national contributions to this specific financing mechanism.
- Duration-sensitive tipping point risk argues for front-loaded mitigation investment. Because the UNEP framework treats overshoot duration — not just peak temperature — as the key driver of tipping-point risk, near-term mitigation spending carries a risk-reduction value that a pure peak-temperature framing would understate.
Frequently Asked Questions
Has the world already passed the 1.5°C climate threshold?
UNEP’s September 2026 report treats a temporary breach of 1.5°C as effectively locked in given current emissions trajectories, with best-case peak warming projected at 1.8°C even under optimistic government pledges, and the remaining carbon budget for a 50% chance of avoiding breach possibly exhausted within about three years.
How big is the gap between climate damage and climate finance?
Substantial — global disaster losses exceed $2.3 trillion annually according to UN 2026 reporting, while international climate finance reached only $136.7 billion in 2024, an order-of-magnitude gap between documented damage and available financing.
How much will it cost to bring warming back down to 1.5°C after overshoot?
Carbon dioxide removal at the scale needed will cost trillions of dollars cumulatively, with per-tonne costs ranging from roughly $100 to $1,000 or more depending on the removal method, according to the State of Carbon Dioxide Removal’s Third Edition (2026).
Conclusion
The UNEP’s September 2026 “Limiting Overshoot” report represents a genuine inflection point in climate policy framing — an acknowledgment that 1.5°C avoidance is no longer the operative planning assumption, replaced by a more complex “overshoot, peak, and decline” pathway with its own distinct, quantifiable economics. For climate finance, ESG investment strategy, and corporate risk planning, the practical implications are concrete: a financing gap measured in trillions rather than billions, a carbon removal market that must scale to unprecedented size at meaningful cost, and a tipping-point risk profile where the duration of overshoot — not merely its peak — will determine how much of this economic cost becomes irreversible.

US Impeachment Talk and White House Press Secretary Changes: What the Record Shows

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide

Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
AI Impact on Wages 2026: Productivity Soars, Paychecks Stagnate
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Analysis4 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025