Global Economy
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

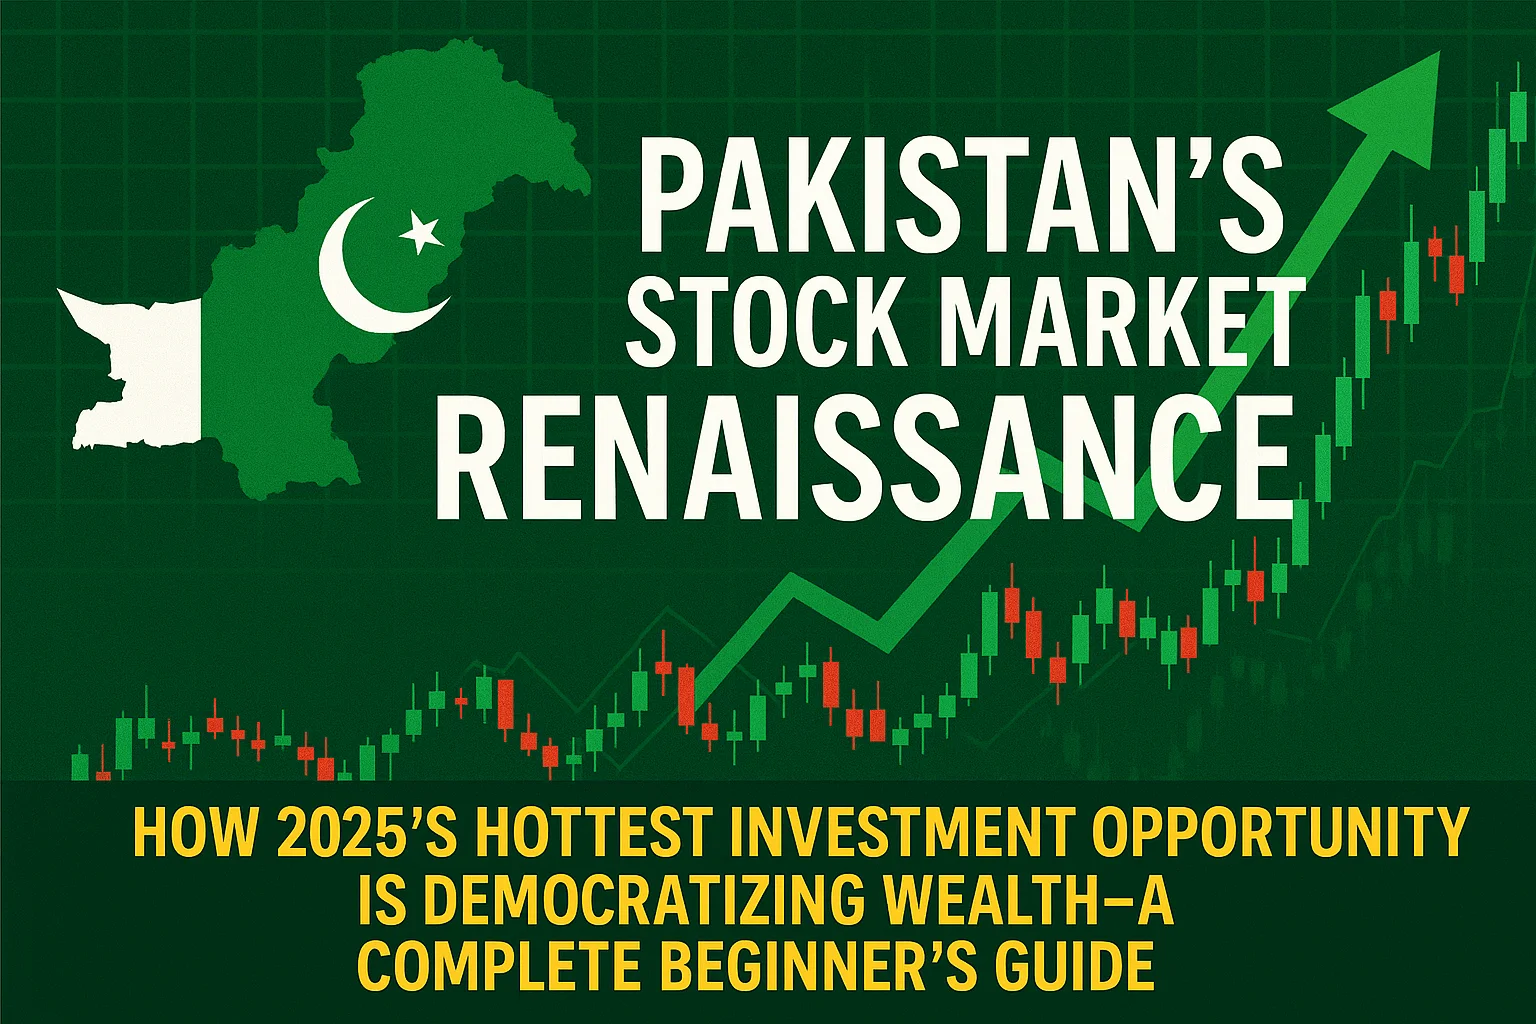
How a frontier market’s 94% surge, IMF-backed reforms, and digital transformation are creating unprecedented opportunities for retail investors
When Saba Ahmed, a 29-year-old graphic designer from Karachi, opened her CDC account in March 2025, she joined a historic wave transforming Pakistan’s investment landscape. With just PKR 50,000 saved from freelance projects, she’s now part of a retail investor revolution that helped propel the Karachi Stock Exchange’s KSE-100 Index to an all-time high of 170,719 points in December 2025—a staggering 94% increase from the previous year.
Her story isn’t unique. From Lahore university students to Islamabad housewives, Pakistanis are discovering what institutional investors have known for months: the Pakistan Stock Exchange has become one of Asia’s best-performing markets, outpacing even regional giants. Yet beneath the record-breaking headlines lies a more profound transformation—the democratization of capital markets in a country where only 0.3% of the population owns shares.
This convergence of financial inclusion, governance reform, and geopolitical positioning offers insights extending far beyond Pakistan’s borders. For policymakers examining emerging market resilience, investors seeking frontier opportunities, and citizens demanding economic participation, the PSX experiment represents a critical test case for whether structural reform can genuinely broaden prosperity.
The Landscape: From Crisis to Confidence
The Numbers That Changed Everything
The KSE-100 Index reached an all-time high of 170,719 points, with 12-month gains exceeding 46%, positioning Pakistan among Asia’s top-performing equity markets. This isn’t hollow momentum—it’s backed by fundamentals that signal genuine transformation.
As of September 2025, PSX lists 525 companies with total market capitalization of approximately PKR 18.276 trillion (about $64.83 billion USD). More significantly, the rally is broad-based: banking, energy, cement, fertilizers, and textiles all contributing, suggesting structural confidence rather than speculative bubbles.
The transformation becomes starker in comparative context. While India’s Nifty 50 delivered respectable returns and Bangladesh struggled with political instability, Pakistan’s stock market emerged as an unexpected outperformer. The PSX Dividend 20 Index—tracking top dividend-yielding companies—gained over 40% year-to-date, offering yields substantially above regional peers.
The Geopolitical Context: Reform Under Pressure
This market renaissance didn’t occur in isolation. It emerged from Pakistan’s $7 billion Extended Fund Facility (EFF) agreement with the IMF, approved in September 2024 and supplemented by a $1.4 billion Resilience and Sustainability Facility. The program imposed painful conditionalities: fiscal primary surplus targets of 2.1% of GDP, broadened tax bases including agricultural income taxes, and energy sector reforms to eliminate circular debt exceeding PKR 4.9 trillion.
Inflation fell to a historic low of 0.3% in April, while gross reserves stood at $10.3 billion at end-April, up from $9.4 billion in August 2024, projected to reach $13.9 billion by end-June 2025. These aren’t just statistics—they’re confidence signals that convinced foreign institutional investors to return after years of capital flight.
Yet risks persist. The IMF’s second review completion in December 2025 came with warnings about policy slippages, geopolitical commodity shocks, and climate vulnerabilities. Recent flooding affected 7 million people and temporarily dampened agricultural output, highlighting Pakistan’s exposure to climate risks. The delicate balancing act between reform momentum and political sustainability will determine whether this rally has legs.
Opening the Gates: Your Step-by-Step Investment Framework
Understanding the CDC Account: The Gateway to PSX
The Central Depository Company (CDC) serves as Pakistan’s securities custodian, similar to the DTCC in the United States or NSDL in India. Your CDC account holds your shares electronically, enabling settlement through the National Clearing Company of Pakistan on a T+2 basis—a system now enhanced by digital integration with the RAAST instant payment system.
Two Account Types Serve Different Needs:
The Sahulat Account targets new investors with simplified documentation. Designed for students, housewives, and small-scale investors, it requires only your CNIC (Computerized National Identity Card) and imposes a PKR 800,000 ($2,840 USD) investment ceiling. This structure eliminates income verification barriers, lowering entry thresholds that historically excluded the majority of Pakistanis from capital markets.
The Sahulat Account gives retail investors access to regular market trading without leverage or futures restrictions, requiring minimal documentation. Once your investment exceeds the ceiling, upgrading to a standard account requires income documentation—a progressive on-ramp recognizing Pakistan’s large informal economy.
The Standard CDC Investor Account offers unrestricted access but demands comprehensive Know Your Customer (KYC) compliance: CNIC/NICOP/Passport copies, bank account verification, address proof, and for Muslims, Zakat exemption declarations. The CDC digitized this process in 2024, enabling online applications through www.cdcaccess.com.pk with mobile app support.
The Practical Process: From Application to Trading
Step 1: Broker Selection and Documentation
Pakistan has 270+ registered Trading Right Entitlement Certificate (TREC) holders—brokerage firms licensed by the Securities and Exchange Commission of Pakistan. Leading digital brokers include KTrade Securities, KASB Securities, Arif Habib Limited, and AKD Securities, each offering mobile trading platforms with varying fee structures.
Brokerage commissions typically range from 0.15% to 0.30% per trade, with annual account maintenance fees between PKR 500-2,000. Capital gains tax on shares held less than one year stands at 15%, while shares held longer face no capital gains tax—a powerful incentive for long-term investing. Dividend income incurs withholding tax of 15% for filers and 30% for non-filers, creating tax incentives for formal economy participation.
Step 2: Account Opening Timeline
Individual accounts are opened within 24 hours whereas corporate accounts take 48 hours after cheque clearance. The process has accelerated dramatically since CDC’s online system launch, eliminating the need for physical office visits in most cases.
Your Account Opening Package includes:
- Transaction Order book for physical trade instructions
- CDC Relationship Number (your unique identifier)
- Access credentials for CDC Access portal and mobile app
- Registration for SMS and email alerts on all transactions
Step 3: Funding and Trading
Investors can fund accounts through bank transfers, with CDC now integrated into Pakistan’s RAAST instant payment system for real-time settlements. The minimum investment varies by stock price—theoretically one share—but practical minimums of PKR 10,000-20,000 ($35-70 USD) provide meaningful diversification.
The Pakistan Stock Exchange operates Monday-Friday with trading sessions from 9:30 AM to 3:30 PM Pakistan Standard Time. Pre-opening sessions allow order placement before market open, while post-close sessions handle uncompleted orders. Modern mobile applications from brokers provide real-time quotes, portfolio tracking, and research tools previously available only to institutional investors.
The Cost Structure: Understanding the Economics
A typical investment of PKR 100,000 faces:
- Brokerage commission: PKR 150-300 (0.15-0.30%)
- CDC fee: PKR 10-15
- SECP regulatory fee: Nominal
- National Clearing Company charges: PKR 5-10
Round-trip transaction costs (buy and sell) total approximately 0.5-0.8% excluding tax—competitive with regional markets but higher than developed economies. These costs matter less for buy-and-hold dividend strategies than for active trading.
The Dividend Aristocrats Strategy: Where Value Meets Stability
Pakistan’s Unique Dividend Culture
The PSX Dividend 20 Index tracks the performance of the top 20 dividend paying companies, ranked and weighted based on their trailing 12-month dividend yield, rebalanced semi-annually. This index provides a ready-made screening tool for income-focused investors, something mature markets offer but many frontier markets lack.
Pakistani corporate culture favors dividend distributions more than growth-focused tech sectors, reflecting the market’s composition. Oil and gas companies, banks, cement manufacturers, and Fast-Moving Consumer Goods (FMCG) firms dominate the high-yield landscape, offering dividend yields frequently exceeding 6-10% annually—substantially above Pakistan’s current inflation rate of approximately 7-8%.
Sector Analysis: Where Dividends Flow
Banking Sector Leaders
Banks like United Bank Limited, Meezan Bank, and MCB Bank have historically provided dividend yields of 6-9%, supported by net interest margin expansion as interest rates normalized from emergency highs. The sector benefited from improved credit quality as macroeconomic stability returned, with non-performing loan ratios declining throughout 2025.
Regulatory capital requirements ensure dividend sustainability, with the State Bank of Pakistan enforcing minimum capital adequacy ratios of 11.5%. Banks that maintained strong provisions during crisis years now possess the balance sheet strength to reward shareholders while funding credit growth.
Oil & Gas Sector Stability
State-owned enterprises like Oil & Gas Development Company Limited (OGDC) and Pakistan Petroleum Limited have provided consistent dividends tied to commodity prices and production volumes. With global energy prices stabilizing and domestic gas field development continuing, these companies offer inflation hedges alongside income.
The government’s 2025 policy shift toward market-determined energy pricing—a key IMF conditionality—reduces subsidy burdens while improving profitability for producers. However, investors must monitor circular debt resolution; delayed payments to power producers historically constrained some companies’ ability to distribute cash.
Fertilizer Sector: Agricultural Dependence
Fauji Fertilizer Company and Engro Fertilizers serve Pakistan’s agricultural sector, which employs 37% of the workforce. Government subsidy reforms targeting agricultural support prices create both risks and opportunities. Reduced direct subsidies may pressure demand, while improved payment discipline by government procurement agencies strengthens receivables quality.
Climate vulnerability represents a material risk—flooding can devastate crop yields, reducing fertilizer demand. Yet Pakistan’s youthful population and food security imperatives ensure long-term agricultural investment, supporting fertilizer industry fundamentals.
The Sustainability Question: Dividend Trap Risks
A sustainable payout ratio typically under 70% ensures the company isn’t over-distributing profits. Investors should verify that dividends are supported by operational cash flow rather than debt-financed distributions—a red flag common during liquidity crises.
Compare yields against government Pakistan Investment Bonds (PIBs). When 10-year PIB yields stand at 11-12%, equity dividend yields of 8-9% must be justified by growth potential or special circumstances. Excessively high yields often signal market skepticism about dividend sustainability.
Navigating the Risks: What Could Go Wrong
Political Instability Premium
Pakistan’s political volatility remains a material risk. Frequent government changes, military influence in economic policymaking, and judicial-executive tensions create uncertainty that periodically triggers capital flight. The 2025 relative stability rests partly on broad political consensus around the IMF program—a consensus that could fracture under electoral pressures or external shocks.
Investors must accept that PSX can experience 20-30% drawdowns triggered by political events unrelated to corporate fundamentals. Historical patterns show rapid recoveries once stability returns, rewarding patient capital but punishing leveraged positions.
Currency Depreciation Reality
The Pakistani Rupee has depreciated approximately 25-30% against the US Dollar over the past five years, a trend that may continue given structural current account pressures. For domestic investors, this matters less—they earn and invest in Rupees. For foreign investors or Pakistanis earning abroad, currency risk substantially affects returns.
The State Bank of Pakistan maintains a flexible exchange rate and continues to improve the functioning of the foreign exchange market and transparency around FX operations. This policy shift from controlled rates reduces central bank intervention but increases volatility. Dollar-denominated returns may significantly lag local currency returns depending on exchange rate movements.
Liquidity Considerations
Average daily trading volume on PSX exceeds PKR 35-40 billion, concentrated in top 50 companies. Mid-cap and small-cap stocks often trade thinly, with wide bid-ask spreads and difficulty executing large orders without moving prices. The introduction of circuit breakers limiting daily price movements to 5% in either direction reduces volatility but can trap investors in illiquid positions during crises.
Foreign institutional ownership remains below 10% of market capitalization, far lower than India (22%) or Indonesia (45%). While rising foreign interest supports valuations, any reversal could pressure prices given limited domestic institutional buffers—pension funds and insurance companies remain underdeveloped compared to regional peers.
Regulatory and Governance Risks
The Securities and Exchange Commission of Pakistan has strengthened enforcement, introducing corporate governance reforms and beneficial ownership disclosure requirements throughout 2024-2025. Yet governance standards still lag international benchmarks, with related-party transactions, opaque family business structures, and limited minority shareholder protections remaining concerns.
The 2025 Governance and Corruption Diagnostic report released under IMF conditionality highlighted persistent issues in procurement transparency and state-owned enterprise governance. While reforms are underway, changing institutional cultures requires years of sustained effort. Investors should favor companies with strong independent directors, transparent reporting, and established audit relationships.
The Broader Implications: What This Means Beyond Markets
Financial Inclusion as Economic Strategy
Pakistan’s 241 million people—62% under age 30—represent an enormous untapped investor base. Individual traders are turning to equities as property prices stagnate and deposit rates have halved in the past two years, illustrating how macroeconomic shifts can democratize investing when alternatives disappoint.
Expanding retail participation addresses multiple policy goals simultaneously. It channels domestic savings toward productive investment, reducing reliance on external financing. It creates middle-class stakeholders in economic stability, building political constituencies for sustained reform. And it addresses youth unemployment by providing wealth-building alternatives to government jobs or emigration.
The challenge lies in investor protection. Unsophisticated investors entering markets during euphoric periods historically suffer losses when sentiment shifts. The SECP’s emphasis on investor education through initiatives like JamaPunji—the investor education portal—attempts to build financial literacy alongside market access. Whether these efforts sufficiently prepare retail investors for inevitable downturns remains uncertain.
The China Factor: Strategic Implications
In 2017, a consortium of Chinese exchanges including Shanghai Stock Exchange, Shenzhen Stock Exchange, and China Financial Futures Exchange acquired a 40% strategic stake in PSX, making China its single largest foreign shareholder. The “China Connect” system theoretically enables cross-border capital flows, though practical implementation has lagged ambitions.
This ownership structure carries geopolitical dimensions. As Pakistan balances its traditional security relationship with China against renewed economic engagement with Western institutions through the IMF, the stock exchange becomes a symbol of competing visions. Chinese infrastructure investment through the China-Pakistan Economic Corridor could boost listed companies’ growth prospects, while Western investors remain cautious about governance and political risks.
Regional Competitive Dynamics
Pakistan competes with Bangladesh, Sri Lanka, and frontier African markets for foreign portfolio investment. Bangladesh’s current political instability provides Pakistan a temporary advantage, while Sri Lanka’s post-default recovery creates a compelling distressed opportunity narrative. Pakistan must sustain reform momentum to differentiate itself as more than a tactical trade.
The comparison with India remains inevitable and unflattering. India’s market capitalization exceeds $4 trillion compared to Pakistan’s $65 billion—a 60:1 ratio that exceeds the countries’ economic size differential. India’s success in building institutional infrastructure, retail participation, and regulatory credibility provides both a roadmap and a competitive challenge. Pakistani policymakers increasingly study India’s National Stock Exchange transformation as a model, adapted for local context.
The Path Forward: Scenarios for the Next Five Years
The Optimistic Case: Structural Transformation
If Pakistan maintains IMF program discipline through 2027 while avoiding major political disruptions, the market could sustain 15-20% annual returns through 2030. Key drivers would include:
- Privatization Pipeline: Government plans to privatize Pakistan International Airlines, several power distribution companies, and other state-owned enterprises could unlock value while demonstrating commitment to market-oriented reforms. Successful privatizations would attract strategic investors and validate governance improvements.
- Digital Transformation: Pakistan’s IT services exports exceeded $3 billion in FY2024-25 and are growing 25% annually. If even a fraction of successful tech companies pursue PSX listings instead of overseas exits, the market could develop a genuine growth sector beyond traditional industries.
- Demographic Dividend: If macro stability persists and regulatory reforms continue, Pakistan’s youthful population could drive sustained consumption growth, benefiting listed consumer companies while expanding the retail investor base.
The Pessimistic Case: Reversal of Fortunes
Conversely, political instability, reform backsliding, or external shocks could trigger rapid capital flight. Pakistan’s vulnerability to:
- Geopolitical Tensions: Escalation with India, Afghanistan spillover effects, or positioning amid US-China competition could rapidly shift investor sentiment. Defense spending imperatives could crowd out development expenditure, slowing growth.
- Climate Catastrophes: As 2025’s flooding demonstrated, Pakistan remains highly vulnerable to climate events. A major disaster could derail fiscal targets, forcing emergency spending that conflicts with IMF conditionalities.
- Reform Fatigue: The political sustainability of IMF-mandated austerity remains questionable. Provincial resistance to agricultural income taxes, business community opposition to documentation requirements, and public frustration with subsidy removal could fracture the reform coalition.
The Most Likely Outcome: Muddling Through
Pakistan’s historical pattern suggests neither sustained excellence nor complete collapse but rather cyclical progress punctuated by periodic crises. The 2025-2026 rally likely represents genuine improvement rather than a bubble, but expecting linear progress ignores structural constraints.
Smart investors will approach PSX as a tactical allocation within diversified portfolios rather than a strategic bet. The market offers compelling risk-adjusted returns for those who understand and accept the volatility, regulatory uncertainty, and currency risks. For Pakistani citizens, participating in their economy’s growth through equity ownership represents both a financial opportunity and a civic engagement act.
Practical Recommendations: How to Proceed
For Individual Investors
Start Small, Learn First: Open a Sahulat Account with minimal capital to understand market mechanics before committing substantial savings. Use the first six months as an education period, tracking your picks without emotional attachment.
Focus on Dividend Aristocrats: Top dividend paying sectors on PSX include banking, energy and fertilizers. Build a portfolio of 6-8 established dividend payers rather than chasing speculative growth. Reinvest dividends to compound returns.
Maintain Realistic Expectations: Budget for 30% drawdowns as normal market corrections. Only invest capital you won’t need for 3-5 years. Consider PSX as 10-20% of total savings, not your entire nest egg.
Stay Informed: Subscribe to PSX announcements through the official data portal. Follow quarterly results for your holdings. Understand that in Pakistan, management quality and political connections often matter more than financial ratios suggest.
For Foreign Investors
Understand Repatriation Rules: Pakistan maintains some capital control vestiges despite liberalization. While foreign portfolio investors can generally repatriate proceeds, sudden policy reversals during crises have occurred historically. Size positions accordingly.
Consider Fund Routes: Emerging market funds or Pakistan-focused funds provide professional management, local expertise, and reduced administrative burden compared to direct investing. Several international fund managers now include Pakistan in frontier market allocations.
Monitor Geopolitics: Political risk isn’t diversifiable in Pakistan—a military coup, India-Pakistan crisis, or IMF program collapse would affect all holdings simultaneously. Maintain hedges or view Pakistan as a small, speculative allocation.
For Policymakers and Regulators
Accelerate Institutional Development: Strengthen pension funds, insurance companies, and mutual funds to provide domestic institutional ballast. Currently, foreign investors and retail traders drive volatility; strong local institutions provide stability.
Enhance Transparency: Mandate beneficial ownership disclosure, strengthen auditor liability, and enforce insider trading penalties rigorously. Governance credibility determines whether Pakistan attracts long-term capital or remains a tactical trade.
Build Financial Literacy: Expand investor education beyond cities. Partner with universities, civil society organizations, and religious institutions to reach populations traditionally excluded from financial systems.
Conclusion: Democracy of Capital in Action
When Saba Ahmed checked her CDC mobile app in December 2025 and saw her modest portfolio up 35% in nine months, she joined millions of Pakistanis experiencing a rare moment—when government policy, market forces, and individual agency aligned to create genuine opportunity.
The Pakistan Stock Exchange’s 2025 renaissance isn’t merely a financial phenomenon. It represents a test of whether structural reform can broaden prosperity beyond elites, whether digital infrastructure can overcome historical exclusion, and whether a frontier market can sustain momentum against formidable headwinds.
Analysts forecast the KSE-100 Index could reach 170,000 points if macroeconomic stability and reform progress continue—a target already achieved, prompting revised estimates above 180,000 for 2026. Yet the more important question isn’t whether markets rally further, but whether this rally reflects and reinforces genuine economic transformation.
For the global community, Pakistan’s experiment offers lessons about IMF program design, financial inclusion strategies, and the political economy of reform. For investors, it presents a high-risk, high-reward opportunity in one of the world’s last major frontier markets. For Pakistanis, it offers something more fundamental—a stake in their nation’s future.
The democratization of capital is never smooth. Markets will correct, disappointments will occur, and risks will materialize. But the principle that ordinary citizens should participate in economic growth, not merely observe it from afar, represents a worthy aspiration. Whether Pakistan’s stock market revolution delivers on that promise will define more than investment returns—it will help shape a nation’s trajectory.
DISCLAIMER: This analysis is for informational and educational purposes only and should not be construed as investment advice. All investments carry risk, including potential loss of principal. Pakistan’s market involves heightened political, currency, and liquidity risks. Readers should conduct their own due diligence and consult qualified financial advisors before making investment decisions. The author has no financial interest in Pakistani securities or companies mentioned.
SOURCES & CITATIONS:
- Pakistan Stock Exchange Official Data Portal (dps.psx.com.pk)
- Central Depository Company of Pakistan (cdcpakistan.com)
- International Monetary Fund Country Reports and Press Releases (2024-2025)
- Securities and Exchange Commission of Pakistan (secp.gov.pk)
- Trading Economics Pakistan Indicators
- Bloomberg, Reuters market data
- Pakistan Bureau of Statistics
- World Bank Pakistan Development Updates


Global economic growth in 2026 is growing increasingly uneven, capital is becoming far more sensitive to financing costs, and discerning a compelling narrative from an investable asset price is crucial. Rather than promising guaranteed returns, this guide outlines essential research methods and key market risks. While the IMF’s October 2026 outlook projects global growth at 3.1% and inflation at 4.7%, its financial-stability report cautions that underlying vulnerabilities persist beneath current market resilience.
Key takeaways
- Match each investment decision to its time horizon, currency and ability to withstand losses.
- Separate observable earnings or contractual cash flows from optimistic forecasts.
- Compare diversification, fees, taxes, liquidity and regulatory restrictions before committing capital.
- Track primary institutional evidence and update assumptions when conditions change.
- Readers in Pakistan should consider rupee exposure and availability of regulated investment channels.
Why this matters now
The central question behind global recession risk 2026 is not merely what may happen next. It is which economic mechanisms could change cash flow, purchasing power or risk. The Bank for International Settlements’ 2026 review describes an economy supported by technological investment but constrained by geopolitical and fiscal pressures. A robust financial plan must therefore survive both a favourable and an adverse scenario.
Start with the baseline, not the frightening headline
The IMF forecast 3.1% global growth in 2026 and 3.4% in 2027, implying continued expansion under its baseline rather than an outright worldwide recession. Nevertheless, forecasts can miss shocks. Investors should monitor a basket of labour, credit, trade, earnings and inflation indicators rather than treating any single signal as destiny. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Yield curves and interest-rate expectations
An inverted yield curve can reflect expectations of weaker activity or future interest-rate cuts, but term premiums and central-bank balance sheets complicate interpretation. A subsequent steepening may accompany either improving growth expectations or falling short-term rates during a downturn. Context matters more than a mechanical threshold. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Credit spreads and lending conditions
Widening differences between risky and safe bond yields can reveal anxiety about defaults and funding. Banks tightening lending standards may reduce business investment and household spending. Monitor multiple jurisdictions: financial stress in one country need not translate into a worldwide contraction, but global funding networks can spread pressure. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Jobs, production and trade
Unemployment changes, hours worked, purchasing-manager surveys and industrial production indicate demand and business confidence. Trade shipment data add external perspective. Monthly releases can be revised, and some indicators lag turning points. Use three-month trends alongside annual comparisons to avoid mistaking seasonal noise for a regime change.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
What investors in Pakistan should monitor
Foreign remittances, import payments, export orders, the rupee and international oil prices transmit global stress to domestic conditions. Preserve liquidity for essential obligations and review high-leverage exposure. In uncertain markets, a disciplined allocation and rebalancing policy is usually more defensible than an all-or-nothing recession bet. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Comparison and decision framework
| Question | Stronger evidence | Warning sign |
|---|---|---|
| What drives returns? | Audited cash flows, clear contract or transparent index | Undefined or projected returns |
| What can go wrong? | Explicit scenario and downside analysis | Claims of guaranteed gains |
| Is it affordable to hold? | Low transparent fees and adequate liquidity | Leverage, costly spreads or lockups |
| Is access legitimate? | Appropriate licensing and clear legal rights | Unverified brokers or custody |
| Is the exposure diversified? | Multiple independent sources of return | One company, sector or currency |
What it means for Pakistani savers and investors
A Pakistani reader faces both international investment risk and local purchasing-power risk. For example, a foreign asset can rise in US-dollar terms while the rupee conversion and transaction costs alter the realized local outcome. The opposite can also occur. Record the starting exchange rate, applicable taxes, custody charges and capital-transfer restrictions, and confirm current requirements with the State Bank of Pakistan and the relevant securities regulator. Overseas access should not be assumed universally available.
An emergency reserve, expensive consumer debt and near-term family obligations deserve attention before any speculative allocation. A portfolio that cannot meet a sudden cash requirement may force sales at the worst moment. The objective is not to remove risk—impossible in markets—but to choose risks that fit the investor’s actual liabilities.
Risks, limitations and uncertainty
Institutional forecasts are conditional and can change after policy decisions, commodity shocks, conflict escalation or unexpectedly weak earnings. Historic correlations are not binding promises about future asset performance. The analysis does not provide live stock prices, current investment product quotes, real-time exchange rates or individualized tax advice. Prices, regulations and product eligibility should be checked on the transaction date.
Frequently asked questions
Is this a guaranteed investment opportunity?
No. Every financial asset or strategy involves uncertainty. The existence of a popular investment theme is not evidence that an individual security is fairly priced.
What should beginners examine first?
Understand the product, the financial loss you could tolerate, fees and liquidity. Verify the provider and decide whether the money may be needed soon.
How do interest rates affect the analysis?
They influence financing costs, discount rates, exchange rates and demand. The effect differs by sector, maturity and business balance sheet.
Can Pakistani residents invest in foreign markets?
Access depends on current foreign-exchange, banking, brokerage, securities and tax rules, and on the investor’s individual circumstances. Check current regulations and regulated providers rather than assuming access.
How often should this analysis be refreshed?
Review institutional economic releases monthly and re-evaluate immediately after material earnings, regulatory or policy changes. Avoid reacting mechanically to every daily market movement.
Is diversification enough to prevent losses?
No. Diversification may reduce company-specific risk but cannot eliminate broad market, currency, inflation or systemic risks.
Conclusion
Sound financial decisions begin with verifiable evidence, reasonable valuation, awareness of uncertainty and a plan that survives adverse outcomes. Readers should compare multiple independent sources and avoid letting a compelling headline substitute for due diligence.
Enterprise generative AI in 2026 presents a genuine paradox: adoption is nearly universal, individual productivity gains are well-documented and real, and yet the majority of organizations still cannot point to measurable enterprise-wide financial return. Understanding that gap — not simply citing adoption statistics — is now the central strategic question for any organization evaluating its AI investment.
The Adoption-to-Impact Gap, By the Numbers
| Metric | 2026 Data | Source |
|---|---|---|
| Organizations using AI in at least one business function | 88–90% | McKinsey / Stanford AI Index |
| Organizations reporting generative AI use specifically | 70–72% | Stanford AI Index / Menlo Ventures |
| CEOs reporting “nothing” or zero measurable ROI | 56% | PwC January 2026 CEO Survey (n=4,454) |
| Organizations seeing significant ROI from generative AI | 29% | 2026 enterprise adoption survey |
| AI projects moving to production achieving positive ROI within 12 months | 44% | Forrester |
| Organizations that have scaled AI beyond pilot stage | ~33% | Multiple 2026 surveys |
| Enterprise generative AI spending growth, 2024→2025 | +222%, reaching $37 billion | Menlo Ventures |
Axis Intelligence Research’s AI Productivity Gap Index (APGI) scores the 2026 landscape at 68.4 out of 100, placing enterprise AI firmly in “Large Gap” territory — worse than the documented adoption-to-impact gaps observed during the 2011–2014 cloud computing adoption cycle or the 2013–2016 enterprise social media adoption cycle. This is a genuinely useful historical anchor: it suggests the current gap between AI deployment and AI value capture, while frustrating to executives, is not unprecedented for a fast-diffusing enterprise technology — but it is currently worse than the two most recent comparable technology cycles.
Why Individual Gains Aren’t Converting to P&L Impact
The productivity gains at the individual level are genuinely substantial and well-measured:
- Active Microsoft 365 Copilot users save 14 to 26 minutes per day, per Microsoft’s own early-user research and a UK government trial respectively.
- Active OpenAI Enterprise users save 40 to 60 minutes per day, according to Goldman Sachs’ reporting of OpenAI usage data from December 2025.
- Individual productivity gains from generative AI tools reach 5x in documented cases, per 2026 enterprise adoption survey data.
- Accenture estimates the average productivity value of generative AI tools at $7,800 per employee per year for knowledge workers.
The conversion failure happens at the aggregation layer. ModelOp’s 2026 survey of 100 senior AI enterprise leaders found that two-thirds of AI-spending organizations rely on estimates of time saved rather than measured financial outcomes to assess ROI — meaning most organizations cannot actually trace individual time savings through to a documented P&L line, even when the underlying time savings are real. PwC’s April 2026 AI Performance Study identifies what separates the top-performing 20% of organizations: they pursue growth (new products, market expansion) alongside efficiency, rather than treating AI purely as a cost-reduction lever — a strategic distinction that appears to be the single strongest predictor of realized enterprise value.
What’s Actually Driving the Failure Modes
Across the 2026 survey literature, five recurring root causes explain why individual productivity gains fail to scale into enterprise transformation:
- Isolated tactical implementation rather than enterprise-wide deployment — pockets of AI usage within specific teams that never integrate into core workflows or systems of record.
- Insufficient data quality and infrastructure — Gartner projects that 60% of AI projects unsupported by AI-ready data will be abandoned through 2026, reinforcing that the primary blocker is data readiness, not model capability.
- Misalignment between AI initiatives and business strategy — AI deployed because it’s available, not because it’s mapped to a specific, measurable business outcome.
- Inadequate change management — 54% of C-suite executives admit adopting AI is “tearing their company apart” internally, reflecting genuine organizational friction rather than pure technology limitation.
- Lack of clear measurement frameworks — the two-thirds of organizations relying on estimated rather than measured outcomes noted above is both a symptom and a cause of this failure mode.
Return-on-Investment Benchmarks Where They Exist
Despite the aggregate gap, credible ROI benchmarks do exist for organizations that have moved past pilot stage:
- McKinsey Global AI Survey: 5.8x average ROI on AI investment within 14 months of production deployment.
- IDC/Microsoft: 3.7x average return per $1 invested in generative AI.
- Forrester Total Economic Impact studies: cite cases of 333% ROI with a six-month payback period for organizations using enterprise-grade platforms with structured deployment.
- Google Cloud’s ROI of AI research: 74% of executives whose organizations use generative AI report ROI within the first year, rising to 88% among agentic-AI early adopters specifically — suggesting agentic (task-executing) AI deployments may be converting to measured ROI faster than general-purpose generative AI usage.
- KPMG’s Q1 2026 AI Quarterly Pulse Survey: 62% of U.S. organizations have achieved measurable ROI or expect it within the next 12 months.
The dispersion across these figures (3.7x to 5.8x average ROI, but also 56% of CEOs reporting zero ROI) is itself the key finding: ROI in enterprise AI is currently bimodal, not normally distributed — organizations either are capturing substantial, measured returns through structured deployment, or are capturing effectively none, with comparatively few landing in a modest-middle-ground outcome.
The Security Governance Dimension: Shadow AI
Parallel to the ROI question, 2026 has been the year enterprise AI security risk moved from theoretical to quantified and regulatory:
- IBM’s Cost of a Data Breach Report 2026 (published July 29, 2026, studying 602 breached organizations across 17 industries and 16 countries) found shadow AI — unauthorized, unapproved AI tool usage — involved in 43% of security incidents, up sharply from roughly one in five the prior year.
- Shadow AI increases average breach costs by $670,000 per incident and adds roughly 10 days to breach identification and containment timelines, per IBM’s data.
- Visibility remains the core governance failure: only 25% of organizations report comprehensive visibility into how employees actually use AI tools, while 35% describe shadow AI usage as pervasive or widespread within their organization.
- Only 37% of organizations have formal AI governance policies in place — meaning 63% are currently operating without documented guardrails, per IBM 2025 data cited across multiple 2026 governance reports.
Regulatory Timeline: The EU AI Act Compliance Clock
Governance is no longer purely a voluntary best-practice question. Under the EU AI Act implementation timeline, most remaining provisions began applying August 2, 2026, with member states now required to maintain at least one national AI regulatory sandbox. A further compliance milestone follows August 2, 2027, when Article 6(1) obligations and legacy general-purpose model compliance requirements take effect. For any organization processing EU data or serving EU customers, ungoverned AI use is now a documented regulatory exposure, not solely a security concern.
Governance Frameworks Auditors Increasingly Expect
Three frameworks have emerged as the reference points defining “reasonable care” in enterprise AI governance:
- NIST AI Risk Management Framework, structured around four functions: Govern, Map, Measure, and Manage.
- ISO/IEC 42001, the certifiable AI management system standard (published December 2023, now increasingly referenced in enterprise audits).
- NIST Cybersecurity Framework 2.0, which added a dedicated Govern function mapping directly onto AI-specific oversight requirements.
What Separates High-ROI Organizations from the 56% Reporting Nothing
Synthesizing across the 2026 research base, the organizations capturing measured, enterprise-wide ROI share a consistent pattern:
- They pursue growth use cases alongside efficiency, not efficiency alone (PwC’s top-performing-20% finding).
- They deploy approved AI tools with real-time coaching rather than blanket bans, which one healthcare-system case study found reduced unauthorized shadow AI usage by 89% while still capturing productivity gains — demonstrating that governance and productivity are not inherently in tension when implemented well.
- They measure financial outcomes directly rather than relying on estimated time-savings as a ROI proxy.
- They treat AI governance as infrastructure, not paperwork — Gartner projects AI governance spending will reach $492 million in 2026 and surpass $1 billion by 2030, reflecting genuine budget commitment rather than compliance-theater spending among leading organizations.
Bottom Line
Enterprise generative AI in 2026 has achieved near-universal adoption and well-documented individual productivity gains — but the majority of organizations still cannot convert those gains into measured, enterprise-wide financial return, with 56% of CEOs reporting zero measurable ROI even as documented benchmarks show 3.7x to 5.8x returns are achievable. The differentiator is not the technology itself but organizational execution: structured deployment paired with genuine financial measurement, growth-oriented rather than purely cost-focused use cases, and governance frameworks robust enough to manage the shadow AI risk now implicated in 43% of security incidents — all under an EU AI Act compliance clock that started running in August 2026.

On September 2, 2026, the UN Environment Programme published a report that treated something once framed as a worst-case risk as a settled outcome: the world will pass 1.5°C of warming. “Limiting Overshoot: Navigating Exceedance of 1.5°C and Pathways Towards Return” marks a deliberate shift in framing, from preventing a threshold breach to managing one already underway — with direct, quantified consequences for climate finance, carbon-removal markets, and the economics of adaptation that businesses and investors now need to plan around.
Key Takeaways
- UNEP’s September 2, 2026 report puts best-case peak warming at 1.8°C even under the most optimistic current government pledges, with a median of around 2.6°C by 2100 (range 1.9°C–3.6°C) under current policies — treating overshoot of the Paris Agreement’s 1.5°C goal as effectively locked in.
- The remaining global carbon budget for a 50% probability of staying within 1.5°C is roughly 130 gigatonnes of CO2 as of 2026 — at current annual emissions of nearly 40 GtCO2, this budget could be exhausted within approximately three years.
- Global disaster losses, including broader economic and ecological damage, already exceed $2.3 trillion annually, according to the UN’s 2026 climate report, while international climate finance reached just $136.7 billion in 2024 — a gap of well over an order of magnitude between damage and financing.
- Carbon dioxide removal (CDR) at the scale needed to return to 1.5°C will cost trillions of dollars, with per-tonne costs estimated at over $100 and ranging up to $1,000 or more depending on the removal method, according to the State of Carbon Dioxide Removal’s Third Edition (2026).
- The Fund for Responding to Loss and Damage held pledges of only around $800 million as of late 2025, a figure researchers describe as dramatically short of documented developing-country needs — underscoring the financing gap at the center of overshoot economics.
From Prevention to Management: A Deliberate Reframing
UNEP’s own annual Emissions Gap Report has tracked the shortfall between climate pledges and required pathways since 2010, but the September 2026 “Limiting Overshoot” report represents a structural change in framing rather than a change in the underlying science. Rather than treating a breach of 1.5°C as an endpoint or failure state, the report proposes an “overshoot, peak, and decline” framework: limiting the maximum level of warming reached, then working to enable a gradual return toward safer conditions over subsequent decades. As UN Secretary-General António Guterres put it in comments accompanying the report’s launch, humanity must pursue “an overshoot of ambition” — accelerating fossil fuel phaseout, slashing methane pollution, and protecting land, forests, and oceans simultaneously, rather than sequencing mitigation and adaptation as separate phases.
The report’s own numbers make clear why this reframing was considered necessary: even the most optimistic scenario incorporating all current government pledges puts expected peak warming at 1.8°C, while continuation of current policies (without stronger pledges) produces a median projection of roughly 2.6°C by century’s end, with a plausible range extending to 3.6°C. Human-induced warming is already approaching 1.4°C and increasing at roughly 0.25°C per decade — a trajectory that leaves essentially no realistic path to avoiding at least a temporary breach of the 1.5°C threshold.
The Carbon Budget Arithmetic
The remaining global carbon budget for a 50% probability of holding warming within 1.5°C stands at roughly 130 gigatonnes of CO2 as of 2026. Against current annual global emissions of nearly 40 gigatonnes, this budget could be exhausted within approximately three years at present emissions rates — a timeline that explains why the report treats exceedance as the base case for planning purposes rather than a tail risk. This arithmetic is central to why the report’s “overshoot, peak, and decline” framework requires not merely emissions reduction but active carbon dioxide removal (CDR) at scale to eventually bring atmospheric concentrations back down, rather than emissions reduction alone.
Tipping Point Risk: The Non-Linear Cost of Overshoot Duration
The UNEP report identifies four specific tipping elements where sustained warming above 1.5°C raises materially elevated risk: the West Antarctic Ice Sheet, the Greenland Ice Sheet, the Atlantic Meridional Overturning Circulation (AMOC), and the climate-biosphere system of the Amazon rainforest. Notably, the report deliberately declines to attach specific temperature thresholds to these tipping points, instead emphasizing that risk increases with both the degree and — critically for economic planning — the duration of overshoot. This duration-sensitivity is central to the report’s economic logic: the longer warming remains above 1.5°C, the greater the cumulative risk of triggering one or more of these systems, with some — such as AMOC weakening — showing model-projected recovery only on a timescale of centuries even if peak warming is later reduced.
This non-linearity matters directly for climate finance and insurance-sector risk modeling: a framework that treats overshoot duration, not just peak magnitude, as the key risk variable implies that near-term emissions reduction and carbon removal investment carry outsized value in limiting tail risk, even if 1.5°C itself is no longer avoidable as a peak.
The Financing Gap: Quantifying the Shortfall
The UN’s broader 2026 climate reporting places global disaster losses — including direct economic damage and broader ecological costs — at over $2.3 trillion annually. Against this figure, international climate finance flows reached just $136.7 billion in 2024, a gap exceeding an order of magnitude between documented damage and available financing. Climate officials have consistently framed this financing not as charitable transfer but as a protective investment against larger future losses — arguing that extreme weather, disrupted agriculture, damaged infrastructure, and displaced populations carry costs to the global economy that substantially exceed the cost of preventive action.
The financing gap is starkest in the Loss and Damage architecture specifically: the Fund for Responding to Loss and Damage held pledges of only around $800 million as of late 2025, against developing-country needs that researchers have estimated run dramatically higher — a mismatch the UNEP report explicitly identifies as an area requiring strengthened international financial commitment, particularly given the report’s emphasis on Common but Differentiated Responsibilities and Respective Capabilities (CBDR-RC) as a governing principle for how overshoot’s costs should be distributed.
The Economics of Carbon Dioxide Removal
Because the “overshoot, peak, and decline” pathway requires active carbon removal to eventually bring warming back toward 1.5°C, CDR economics have become directly material to climate finance planning in a way they were not when 1.5°C avoidance still seemed achievable through emissions reduction alone. The State of Carbon Dioxide Removal’s Third Edition (2026) estimates that many CDR approaches cost over $100 per tonne of CO2 removed, with some methods running $1,000 or more — and that deploying CDR at the annual billion-tonne scale required to meaningfully support a return to 1.5°C will cost trillions of dollars in cumulative terms, posing a genuine financial constraint on the pathway’s feasibility.
UNEP’s 2026 analysis separately and explicitly rules out solar radiation management (SRM) as a viable substitute or complement at this stage, characterizing the evidence base as limited, largely theoretical, and concentrated in a handful of countries — with significant equity implications given that SRM deployment location could produce regionally uneven climate impacts. This effectively narrows the overshoot-management toolkit to emissions reduction plus CDR, reinforcing the trillion-dollar-scale financing requirement rather than offering a lower-cost technological alternative.
Heat, Labor, and Productivity: An Underpriced Economic Risk
Beyond direct disaster losses, the UNEP report highlights heat-related productivity losses as a specific and growing economic risk channel: increasing humid heat is projected to significantly reduce outdoor labor capacity, deepening economic losses specifically in vulnerable, often lower-income countries with large outdoor and agricultural workforces. This risk channel — distinct from more visible disaster-loss categories like flooding or storm damage — represents a slower-moving but potentially larger cumulative economic cost that current climate finance flows are not clearly calibrated to address.
Implications for ESG Finance and Corporate Climate Strategy
- Adaptation finance requires a step-change, not incremental growth. The UN Secretary-General has specifically called on developed countries to triple adaptation finance and ensure it reaches those most at risk — a target that implies current adaptation financing trajectories are viewed as fundamentally inadequate given the now-explicit overshoot scenario.
- CDR investment carries genuine but expensive strategic value. With per-tonne CDR costs ranging from roughly $100 to over $1,000, ESG and climate-focused investors should differentiate between lower-cost, more scalable removal methods and premium, higher-certainty approaches when evaluating portfolio exposure to carbon removal markets.
- Loss and Damage exposure should be modeled as a growing, underfunded liability. With pledged funding around $800 million against dramatically larger documented needs, businesses operating in climate-vulnerable regions should anticipate continued political and financial pressure for expanded corporate and national contributions to this specific financing mechanism.
- Duration-sensitive tipping point risk argues for front-loaded mitigation investment. Because the UNEP framework treats overshoot duration — not just peak temperature — as the key driver of tipping-point risk, near-term mitigation spending carries a risk-reduction value that a pure peak-temperature framing would understate.
Frequently Asked Questions
Has the world already passed the 1.5°C climate threshold?
UNEP’s September 2026 report treats a temporary breach of 1.5°C as effectively locked in given current emissions trajectories, with best-case peak warming projected at 1.8°C even under optimistic government pledges, and the remaining carbon budget for a 50% chance of avoiding breach possibly exhausted within about three years.
How big is the gap between climate damage and climate finance?
Substantial — global disaster losses exceed $2.3 trillion annually according to UN 2026 reporting, while international climate finance reached only $136.7 billion in 2024, an order-of-magnitude gap between documented damage and available financing.
How much will it cost to bring warming back down to 1.5°C after overshoot?
Carbon dioxide removal at the scale needed will cost trillions of dollars cumulatively, with per-tonne costs ranging from roughly $100 to $1,000 or more depending on the removal method, according to the State of Carbon Dioxide Removal’s Third Edition (2026).
Conclusion
The UNEP’s September 2026 “Limiting Overshoot” report represents a genuine inflection point in climate policy framing — an acknowledgment that 1.5°C avoidance is no longer the operative planning assumption, replaced by a more complex “overshoot, peak, and decline” pathway with its own distinct, quantifiable economics. For climate finance, ESG investment strategy, and corporate risk planning, the practical implications are concrete: a financing gap measured in trillions rather than billions, a carbon removal market that must scale to unprecedented size at meaningful cost, and a tipping-point risk profile where the duration of overshoot — not merely its peak — will determine how much of this economic cost becomes irreversible.

US Impeachment Talk and White House Press Secretary Changes: What the Record Shows

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide

Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
AI Impact on Wages 2026: Productivity Soars, Paychecks Stagnate
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Analysis4 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025