Analysis
When the Strait Shakes: How the US-Iran War Is Rewriting the Rules of Global Finance

There is a moment in every genuine geopolitical crisis when financial markets stop pretending they are merely reacting to data and begin reckoning with something more elemental: fear. That moment arrived on the morning of Saturday, February 28, 2026, when the United States and Israel launched coordinated strikes on Iran—killing Supreme Leader Ayatollah Ali Khamenei and igniting the most consequential military conflict in the Middle East in a generation. By Monday morning in New York, the world’s trading floors were measuring the aftershocks in barrels, basis points, and bullion.
What began as a targeted military operation has rapidly evolved into a multi-front conflict with cascading implications for energy markets, global supply chains, and the architecture of international finance. For investors, policymakers, and ordinary citizens watching the price of petrol rise at the pump, the central question is no longer whether markets will feel the US-Iran conflict market impact—they already are. The real question is how deep, how prolonged, and who ultimately bears the cost.
Immediate Market Reactions: Risk-Off in Real Time
The financial system’s first verdict was swift and largely predictable in its direction if not its magnitude. Stocks fell and the dollar climbed as military strikes intensified across the Middle East, sending oil to its biggest surge in four years while stoking concern that inflation will accelerate. Gold briefly topped $5,400. The S&P 500 dropped 1.1%, following losses in Europe and Asia. Airlines and cruise operators sank while energy and defense shares jumped. Bloomberg
By Monday’s open, the damage had spread more broadly. The Dow Jones Industrial Average dropped 282 points, or 0.6%. The S&P 500 lost 0.5%, and the Nasdaq Composite declined 0.4%—though the three major averages rallied off session lows as gains in technology stocks helped trim losses. At their nadir, the Dow was down about 600 points, or 1.2%. CNBC The CBOE Volatility Index—Wall Street’s so-called “fear gauge”—jumped to its highest level of 2026.
The bond market offered a counterintuitive signal. The 10-year Treasury yield was little changed Monday at 3.97%, regaining some ground after falling to an 11-month low of 3.926% on Friday. CNBC That modest move suggested bond traders are torn between two forces: a flight-to-safety impulse pulling yields lower, and an inflation anxiety—driven by soaring oil—pushing them back up. As an analyst, I’ve observed this precise tension before in conflict-driven crises: the bond market’s internal debate often telegraphs how long-lasting the disruption will prove to be.
The Strait of Hormuz: The World’s Most Expensive Bottleneck
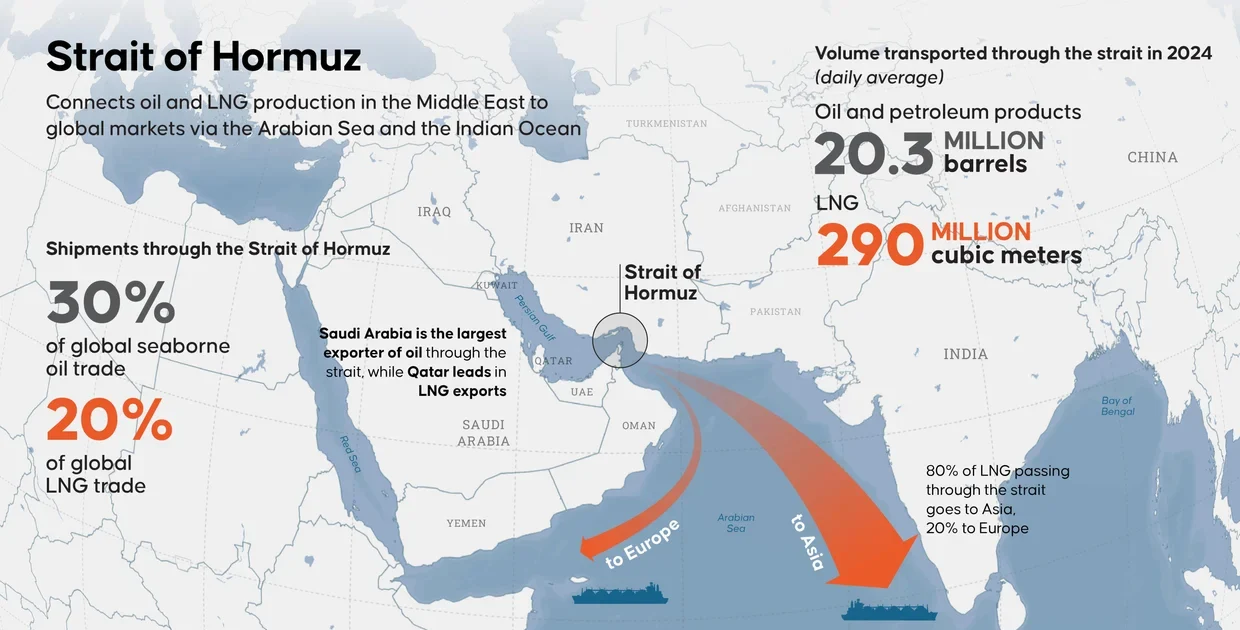
No single geographic feature looms larger over the geopolitical risks oil prices calculation than the Strait of Hormuz. This narrow waterway between Iran and Oman is, in the words of one analyst, not a “production story” but a “chokepoint story”—and chokepoints, when threatened, carry systemic implications that dwarf any single country’s output.
More than 14 million barrels per day flowed through the Strait in 2025, or roughly a third of the world’s total seaborne crude exports. About three-quarters of those barrels went to China, India, Japan and South Korea. China, the world’s second-largest economy, receives half of its crude imports through the Strait. CNBC Iran has threatened to close this waterway entirely.
About 13 million barrels per day of crude oil transited the Strait of Hormuz in 2025, accounting for roughly 31% of global seaborne crude flows, according to market intelligence firm Kpler. CNBC Container shipping giants have already responded: Maersk announced it would suspend all vessel crossings in the Strait of Hormuz until further notice, warning that services calling ports in the Arabian Gulf may experience delays. CNBC
Amrita Sen, founder of Energy Aspects, told CNBC that oil markets are likely to hold around $80 a barrel for now after an initial spike, noting stabilization, but warned that “what the U.S. will not be able to do is control these one-off attacks on tankers.” CNBC The insurance industry is already pricing in the risk: marine hull insurance in the Gulf could rise by 25 to 50 percent in the near term, according to Dylan Mortimer, marine hull UK war leader at insurance broker Marsh. CNBC Those premiums ultimately flow through to the cost of every barrel, and every barrel’s cost flows through to every economy on earth.
Sector-Specific Impacts: Winners, Losers, and the Middle Ground
The Iran tensions global economy shock has not distributed its pain—or its windfalls—evenly across sectors. The divergence is stark.
Energy and Defense: The Reluctant Beneficiaries
Several oil stocks surged following the strikes on fears the conflict could disrupt global crude production and transport. Exxon Mobil and Chevron shares gained about 4%, while ConocoPhillips was also up more than 5%. Brent crude prices hit a new 52-week high of more than $78 on Monday. CNBC Defense contractors followed suit: Lockheed Martin shares gained 6%, while Northrop Grumman was up 5%, and drone maker AeroVironment jumped more than 10%. CNBC
Travel and Hospitality: The Immediate Casualties
Travel-related stocks dropped sharply. United Airlines, most exposed to international travel of the US carriers, tumbled more than 6%. American and Delta each fell more than 5%. Marriott International slid nearly 5%, while Airbnb sank more than 3%. Online reservation platforms Expedia and Booking Holdings slid more than 4% and 3% respectively. CNBC
The human toll on aviation has been immediate. Airlines canceled thousands of flights for the week in the Middle East, with 1,560 flights scrubbed on Monday alone, or 41.28% of those scheduled for arrival in Middle East countries, according to aviation data firm Cirium. Hundreds of thousands of passengers remain stranded. CNBC
Safe-Haven Assets: Gold’s Gravity-Defying Run
Gold’s ascent has been the defining market narrative of this crisis. Gold rallied above $5,300 per ounce, hitting record highs as investors moved into safe-haven assets. JP Morgan has raised its gold price target to $6,300 per ounce by December 2026, reflecting analyst confidence that this isn’t just a temporary spike. INDmoney Precious metals and the US dollar are now functioning as the twin shock absorbers of the global financial system.
Long-Term Risks: Inflation, Fragmentation, and the Asian Dimension
Beyond the immediate volatility lies a more structurally dangerous set of pressures. Elevated oil prices, if sustained, function as a regressive global tax—hitting emerging markets, commodity-importing nations, and lower-income households hardest.
Standard Chartered’s Global Head of Research Eric Robertsen noted that investors had already been underpricing geopolitical risk, with commodity-linked currencies outperforming, suggesting markets are paying for exposure to scarce resources and terms-of-trade winners. CNBC
The implications for Asia—the region most dependent on Hormuz-transiting oil—are severe and underappreciated by Western financial commentary. China, Japan, South Korea, and India collectively import the vast majority of their crude through this corridor. Any sustained disruption would accelerate inflationary pressures across Asian manufacturing economies, potentially stalling the global export recovery that policymakers have counted on.
There is also the geopolitical fracture dimension. China and Russia have condemned the US-Israeli strikes. In a phone call with his Russian counterpart, Chinese Foreign Minister Wang Yi said it was “unacceptable for the US and Israel to launch attacks against Iran.” CNBC This fracture carries long-term implications for dollar-denominated trade systems, multilateral institutions, and the cohesion of any post-conflict reconstruction framework.
The scenario analysis from Wells Fargo is instructive. Their strategists mapped out scenarios ranging from quick de-escalation to a worst-case prolonged Hormuz closure: in their worst-case scenario, the S&P 500 could drop to 6,000 from current levels around 6,850, but their base case still targets 7,500 by year-end. INDmoney The range of that spread—nearly 25%—is itself a measure of how genuinely uncertain the endgame remains.
The Diplomatic Paradox: War Launched During Talks
Perhaps the most jarring dimension of this crisis is the diplomatic context in which it erupted. The UN Secretary-General noted that the joint military operation by Israel and the United States occurred following indirect talks between the US and Iran mediated by Oman, “squandering an opportunity for diplomacy.” UN News
Although the last round of talks ended Thursday with Iran agreeing to “never” stockpile enriched uranium, that was not enough to avert US military action. CNN Markets loathe uncertainty, but they despise diplomatic incoherence even more—because it removes the scaffolding of predictable resolution. The absence of a clear off-ramp is precisely what is keeping risk premiums elevated across asset classes.
President Trump has suggested the conflict could last four weeks, and separately told The Atlantic that Iran’s new leadership wants to resume negotiations. Trump said Iran’s new leadership wanted to resume negotiations and that he has agreed to talk to them, saying “They want to talk, and I have agreed to talk.” CNBC Markets will be parsing every diplomatic signal for evidence of de-escalation—any credible ceasefire announcement would likely trigger a sharp oil selloff and equity recovery.
Investor Implications and Strategic Considerations
For portfolio managers navigating Middle East conflict investment strategies, several principles apply in this environment.
Overweight energy and defense selectively. The oil price tailwind for integrated majors and defense contractors is real, but entry points matter. Much of the initial upside is already priced in.
Reduce exposure to aviation, hospitality, and emerging-market importers. Nations like India, South Korea, and Japan face disproportionate energy import cost pressures, which will compress corporate margins and strain current accounts.
Monitor the Strait obsessively. David Roche of Quantum Strategy framed the market impact in terms of duration and whether Iran would attempt to close the Strait of Hormuz—if the conflict is short and contained, the risk-off move and oil spike could be brief; if it turns into a three-to-five-week regime change endeavor, markets would react “rather badly.” CNBC
Gold remains the structural hedge. With JP Morgan targeting $6,300 by year-end and central bank demand for bullion already at historical highs entering 2026, gold’s role as the geopolitical insurance policy of last resort appears set to deepen.
Conclusion: A Conflict That Will Rewrite Risk Premiums
The US-Iran conflict of February-March 2026 is not merely another geopolitical flare-up to be absorbed and forgotten within a trading week. The assassination of Khamenei, the direct involvement of US military forces, the threatened closure of the world’s most critical energy chokepoint, and the fissure it has opened between Western and non-Western powers collectively represent a structural inflection point for global markets.
In the short term, monitor Brent crude and the CBOE VIX daily as the conflict’s most sensitive barometers. In the medium term, watch whether Iran’s successor leadership follows through on negotiation signals or opts for prolonged asymmetric warfare against Gulf infrastructure. In the long term, consider how this crisis accelerates the already-underway energy transition: every $10 increase in sustainable oil prices makes renewable alternatives marginally more competitive, nudging capital allocation toward green infrastructure.
Conflict is never an opportunity to celebrate. But history teaches that periods of maximum geopolitical uncertainty are also when the contours of the next financial order begin to take shape—quietly, beneath the noise of war. The investors and institutions who read those contours correctly today will be better positioned for the world that emerges when the smoke clears over Tehran.

A major U.S. submarine-manufacturing project announced on October 6, 2026 has put an unfamiliar name at the center of a familiar defense-industry problem: how to build submarine components faster without sacrificing quality or reliability. Defense technology firm Anduril announced plans for Arsenal-2, a facility at Sparrows Point in Maryland intended to expand production of parts for the U.S. Navy’s Virginia-class attack submarines. The combined headline figure is $6.6 billion—made up of the company’s planned $3.7 billion private investment and a Navy contract valued at up to $2.9 billion, with payments tied to production outcomes. These are announcements and commitments, not evidence that all the capital has already been spent. Anduril’s official announcement and Reuters’ independent report outline the project.
Key takeaways:
- Arsenal-2 is a planned submarine-components manufacturing facility, not an already operational assembly line for completed submarines.
- The $6.6 billion headline combines two different funding streams and different forms of financial commitment.
- The project is aimed at bottlenecks in the Virginia-class supply chain, including specialized manufacturing capacity.
- Its success will depend on skilled labor, qualification standards, equipment, scheduling and delivery—not simply construction of a large building.
What is Arsenal-2?
Arsenal-2 is Anduril’s proposed software-centered manufacturing project at Sparrows Point, a former industrial site in Baltimore County, Maryland. According to the company’s October 6 announcement, the facility is designed to make critical components for Virginia-class submarines and give the Navy access to additional industrial capacity. The project illustrates a widening role for technology-sector defense contractors in traditional heavy manufacturing.
Submarine construction is a particularly difficult domain. Components must meet demanding specifications for performance, durability, safety, quality control and compatibility with other systems. A factory that produces ordinary industrial hardware cannot immediately be treated as a qualified submarine supplier.
Anduril’s pitch is that modern factory software, automation, new processes and private capital can ease some of those constraints. Whether the company can execute on that pitch will be judged by qualification milestones and repeatable deliveries.
What will the facility actually produce?
Initial work centers on critical Virginia-class components, including torpedo tubes, according to the company and Reuters. Those are sophisticated submarine systems, but producing them is not the same as manufacturing a complete nuclear-powered submarine.
A Virginia-class attack submarine involves propulsion, pressure-hull construction, combat systems, sensors, life-support equipment, electronics, integrated software and years of testing. Its final assembly and delivery depend on a specialized network of contractors, yards and government oversight. New suppliers can strengthen the network by removing specific bottlenecks rather than replacing every incumbent shipbuilder.
The distinction matters for readers encountering sweeping “Anduril to build submarines” headlines. The verified announcement concerns industrial capacity for components, with ambitions that may expand as the project matures; it should not be presented as a commitment to launch an entire finished fleet by a fixed date.
Understanding the $6.6 billion figure
| Announced element | Stated figure | Important qualification |
|---|---|---|
| Anduril planned private capital | $3.7 billion | Planned investment to develop production capacity |
| U.S. Navy contract | Up to $2.9 billion | Contract ceiling with payments conditioned on outputs |
| Combined headline amount | $6.6 billion | Sum of different commitments; not identical to money already disbursed |
Anduril’s release describes the contract as outcome-based. That arrangement is designed to connect government spending to verified delivery rather than solely to reimbursed activity. But details of individual milestones, acceptance criteria, ownership and long-term risk allocation should be determined from contract documents—not guessed from a launch-day headline.
The distinction between an award, a contract ceiling, a planned investment and cash expenditure is crucial. A press announcement does not mean the project has already consumed $6.6 billion in cash or delivered proportionate output.
Why the Navy needs more industrial capacity
Submarines are strategically important for intelligence collection, maritime defense and deterrence. But they also illustrate the challenges of complex, low-volume manufacturing. The United States needs trained workers who can perform specialized fabrication, welding, machining, inspection and systems integration. Individual suppliers can become bottlenecks if they are asked to deliver more components than their equipment or workforce can manage.
The Financial Times’ account of the announcement situated Arsenal-2 within a larger push to expand the submarine industrial base and modernize acquisition. The Navy’s construction requirements and commitments under the AUKUS security partnership increase the importance of sustainable production capacity over the coming years.
This is a long-term manufacturing question, not an immediate shortcut. Building a factory is one stage; training a workforce, validating manufacturing processes and coordinating with other shipbuilders are additional stages.
Why Sparrows Point matters
Sparrows Point was a major American industrial center associated with steel production. Using that site for advanced defense manufacturing creates a recognizable local economic narrative: industrial land and workforce capacity potentially being redirected toward a contemporary strategic sector.
Associated Press reporting described expectations of approximately 3,100 direct jobs connected to the facility, while Reuters reported similar plans. They are projected jobs rather than a verified count of positions already filled.
The ultimate local impact will depend on the pace of construction, hiring, regional supply chains, transport needs, worker training and how much demand the project sustains. Job announcements should be revisited against actual payroll, construction and production data.
When will Arsenal-2 begin manufacturing?
Accounts of the project point to operations around 2030, subject to execution. Business Insider and Financial Times discussed that timeline. Treat it as a planned target, not an operational fact.
Even if initial lines become active on schedule, production volume and acceptance quality will determine how useful the added capacity becomes to the Navy. A component supplier can have machinery installed yet still face qualification delays, workforce shortages or unexpected integration issues.
The execution milestones worth tracking
- Facility permits, ground work and construction progress.
- Hiring and certification of specialist personnel.
- Commissioning of production lines and inspection systems.
- First qualified component deliveries accepted by the relevant customer.
- Repeat production rates, quality performance and on-time deliveries.
- Evidence that the additional capacity reduces delays in the broader submarine supply chain.
These measurable steps provide a better accountability framework than celebrating the contract’s face value alone.
Can software solve a shipbuilding bottleneck?
Software can improve production scheduling, digital modeling, machine monitoring, traceability and quality documentation. Automation may make some operations more consistent. Those are useful tools, but they still rely on expensive physical equipment, material supply and highly skilled people. A complex pressure-critical component cannot be delivered by software alone.
The question is therefore not whether a tech company can bring useful technology into shipbuilding. It is whether that company can combine technology with industrial practices refined over decades, and do so at sufficient scale.
Frequently asked questions
Is Anduril building complete submarines?
Its verified October 6 announcement emphasizes components for Virginia-class submarines, not delivery of complete nuclear-powered boats.
Where is Arsenal-2 located?
The project is planned for Sparrows Point in Baltimore County, Maryland.
How much is the Navy paying?
Anduril announced a Navy contract of up to $2.9 billion, distinct from the company’s planned $3.7 billion capital investment.
When will it open?
Reports describe a target around 2030. The actual schedule depends on construction, production-line qualification and other milestones.
How many jobs could be created?
Approximately 3,100 direct jobs were projected in contemporaneous reporting; these are not confirmed hires.
Why is this important for AUKUS?
A more resilient U.S. submarine industrial base can support national procurement needs and wider allied commitments, although a single parts factory cannot resolve all submarine-production constraints.
Bottom line
Arsenal-2 is significant because it tests whether a technology-focused contractor can add reliable industrial capacity to one of America’s hardest manufacturing sectors. The $6.6 billion figure describes a potentially major investment and contract arrangement—but future milestones, not headlines, will determine whether it meaningfully speeds submarine deliveries.
Key Takeaways
- Chip stocks tumbled Monday, September 14, 2026, after the CEOs of Anthropic, OpenAI, and xAI publicly aligned behind a call to slow the pace of frontier AI capability development — an unusual moment of unity among fierce industry rivals.
- Nvidia fell 3.4% and the Philadelphia Semiconductor Index (PHLX) sank almost 6%, its worst single day since early July, even as the broader Nasdaq Composite closed down a more modest 0.56%.
- The catalyst was an essay from Anthropic CEO Dario Amodei, titled “We Must Pace the Frontier,” proposing independent outside evaluators be given internal access to frontier AI labs, alongside industry-wide cooperation and government coordination.
- OpenAI CEO Sam Altman confirmed in a Fortune interview that OpenAI will not pursue an IPO in 2026, calling the current safety environment an “ill-advised moment” to go public — pushing one of the most anticipated listings in tech history to 2027 at the earliest.
- The episode followed the resignation of a researcher who had worked at both Anthropic and OpenAI, who warned publicly that people building the technology “earnestly believe it could kill us all by the end of the decade” — a post that drew over 150 million views and prompted more than 20 lawmakers to call for tougher AI regulation.
A rare display of unity among Silicon Valley’s most competitive AI labs sent a jolt through markets this week, as semiconductor stocks logged their worst day in over two months following public calls from the industry’s top executives to deliberately slow the development of increasingly powerful AI systems.
What Triggered the Selloff
The catalyst was an essay published Saturday, September 12, by Anthropic CEO Dario Amodei, titled “We Must Pace the Frontier.” In it, Amodei argued that unchecked acceleration in frontier AI development — driven in part by the risk of recursive self-improvement, where AI systems increasingly assist in designing their own successors — is outpacing the industry’s ability to keep those systems aligned and secure. Amodei wrote that he believes AI could still “dramatically raise the quality of human life,” but argued the risks accompanying its current pace of development need to be taken seriously, proposing that even a modest slowdown of a year or two could meaningfully improve safety outcomes.
What made the essay market-moving wasn’t just its content, but who endorsed it. OpenAI CEO Sam Altman and SpaceX/xAI’s Elon Musk — two executives whose companies compete directly with Anthropic and with each other — both publicly backed Amodei’s proposal within a day. Musk wrote simply on X that “Dario is right,” a notable shift given Musk’s history of sharp public criticism of Anthropic.
The Proposal’s Substance
Amodei’s plan outlined a three-phase approach: independent safety evaluators embedded within frontier AI companies with access equivalent to internal staff (covering training processes, internal systems, and safety-protocol compliance); broader industry-wide cooperation on shared safety standards; and coordination with democratic governments on global regulatory frameworks. Anthropic said it would adopt the outside-evaluator step immediately, while Altman confirmed OpenAI would adopt comparable third-party evaluator access.
The Resignation That Set the Stage
The unity among AI executives followed a more unsettling precursor: a researcher who had previously worked at both Anthropic and OpenAI resigned the prior week, writing publicly that people building the technology “earnestly believe that it could kill us all by the end of the decade.” The post reportedly drew more than 150 million views on X and prompted more than 20 lawmakers to call for tougher AI regulation — context that appears to have accelerated the executives’ public alignment on pacing concerns.
Market Reaction: Chips Hit Hardest
Monday’s trading session showed a clear divergence in how different corners of the AI-linked market absorbed the news. Semiconductor stocks bore the brunt of the selling, given their direct exposure to the capital-expenditure cycle that rapid AI capability development has fueled. Nvidia fell 3.4%, Intel dropped 5.6%, and the Philadelphia Semiconductor Index tumbled nearly 6% — its steepest one-day decline since early July.
By contrast, shares of some larger Big Tech and software companies actually climbed on the day, leaving the broader, tech-heavy Nasdaq Composite down a comparatively modest 0.56%, after having fallen as much as 1.3% intraday before paring losses. The divergence suggests markets are interpreting a potential AI development slowdown as a more direct threat to chip demand specifically — the hardware layer most tied to the “faster, bigger” capability race — than to software and platform companies with more diversified revenue.
OpenAI’s IPO Delay: The Clearest Business Signal
Beyond the one-day stock move, the most concrete business consequence to emerge from the episode was Sam Altman’s confirmation that OpenAI will not go public in 2026. In a Fortune interview published the same weekend, Altman said an IPO “right now would be an ill-advised moment” given the current safety environment, and when asked whether 2027 was more realistic, replied simply, “I would say not 2026.” That timeline represents a real shift: OpenAI CFO Sarah Friar had told employees just a month earlier that the company would likely go public in 2027, or potentially sooner if the business continued to “inflect.”
Notably, Anthropic’s own IPO preparations are reportedly continuing on a separate track. According to reporting on the matter, Anthropic — confidentially valued at $965 billion earlier in 2026 — has continued meeting with prospective investors and could begin marketing its IPO as early as October, aiming to complete the listing before the November midterm elections, even as its CEO simultaneously champions industry-wide deceleration. Observers have noted the apparent tension in pursuing an IPO while publicly urging pacing, though Amodei’s essay explicitly framed pacing as slowing capability development, not halting commercial or fundraising activity.
Market Snapshot: September 14, 2026
| Index / Stock | Move | Note |
|---|---|---|
| Philadelphia Semiconductor Index (SOX) | -5.9% | Worst day since early July |
| Nvidia (NVDA) | -3.4% | Direct AI-chip exposure |
| Intel (INTC) | -5.6% | |
| Nasdaq 100 | -0.8% | |
| Nasdaq Composite | -0.56% | Software names partially offset chip losses |
| S&P 500 | -0.5% |
Why This Matters for Technology News and Investors
This episode marks one of the first times investor sentiment around AI has moved meaningfully on a safety-driven narrative rather than a purely commercial one — competitive product launches, earnings beats, or compute-capacity announcements. For investors tracking technology news, the key signal to watch going forward is whether this represents a genuine, sustained industry pivot toward deliberate pacing (which could structurally slow the capital-expenditure supercycle currently powering semiconductor demand), or a rhetorical moment that fades once competitive pressure between OpenAI, Anthropic, xAI, and other labs reasserts itself — a tension the OpenAI-Anthropic IPO-timing contrast already illustrates.
Frequently Asked Questions
Why did semiconductor stocks fall after the AI slowdown announcement? Chip stocks are directly tied to the capital-expenditure cycle fueling rapid AI capability development, so markets interpreted a potential industry-wide pacing effort as a more direct threat to near-term chip demand than to software or platform companies.
Is OpenAI still planning to go public? Yes, but not in 2026. CEO Sam Altman confirmed OpenAI is delaying its IPO to 2027 at the earliest, citing the current AI safety environment, while OpenAI’s CFO had previously suggested 2027 was the likely target regardless.
What did Anthropic’s CEO actually propose? Dario Amodei’s essay proposed embedding independent outside safety evaluators within frontier AI companies with internal-level access, alongside broader industry cooperation on safety standards and coordination with democratic governments on regulatory frameworks — explicitly framed as pacing capability development, not halting it.
The Mechanics of Government Borrowing and Macroeconomic Stability
A Fiscal Deficit is a fundamental economic concept that occurs when a government’s total expenditures exceed its total revenue (excluding money generated from borrowings) within a specific financial year. In simpler terms, it is the financial shortfall a government experiences when it spends more than it earns. To bridge this gap, the government has no choice but to borrow money, which directly contributes to the accumulation of Public Debt.
For readers of Thefinance.pk and Economy.com.pk, understanding the dynamics of fiscal deficits is essential. The size and management of this deficit influence everything from national inflation rates to the amount of taxes citizens will pay in the future. It is a defining metric of a nation’s fiscal health and its government’s economic discipline.
Revenue vs. Expenditure: The Anatomy of a Deficit
To understand why deficits happen, we must break down a national budget into its two primary components: Revenues and Expenditures.
1. Government Revenues: Governments generate income primarily through taxation. This includes:
- Direct Taxes: Income tax, corporate tax, and property taxes.
- Indirect Taxes: Sales tax, Value Added Tax (VAT), excise duties, and customs duties.
- Non-Tax Revenues: Profits from state-owned enterprises (SOEs), privatization proceeds, administrative fees, and central bank dividends.
2. Government Expenditures: Expenditures are broadly categorized into two types:
- Current (Non-Development) Expenditure: This is the day-to-day cost of running the country. It includes public sector salaries, pensions, defense budgets, subsidies, and—most importantly—interest payments on existing debt.
- Development (Capital) Expenditure: This is money spent on creating productive assets, such as building highways, dams, hospitals, schools, and energy grids. This type of spending is an investment in the country’s future economic capacity.
A fiscal deficit expands when current expenditures spiral out of control, or when tax collection agencies fail to meet their revenue targets. In many developing economies, a narrow tax base and massive inefficiencies in state-owned enterprises create persistent, structural fiscal deficits.
The Difference Between Deficit and Debt
It is crucial to distinguish between a deficit and debt, as the terms are often confused.
- The Fiscal Deficit is a flow variable. It measures the budget shortfall over a specific period, usually one year.
- Public Debt (or National Debt) is a stock variable. It is the cumulative total of all past fiscal deficits that have not yet been repaid. Every year a government runs a deficit, it adds to the national debt.
How Governments Finance the Deficit
When a government runs out of money, it cannot simply close its doors. It must finance the deficit through several channels:
- Domestic Borrowing: The government issues securities like Treasury Bills (T-Bills) and Pakistan Investment Bonds (PIBs). Commercial banks buy these bonds, effectively lending customer deposits to the government.
- External Borrowing: The government borrows foreign currency from multilateral institutions like the International Monetary Fund (IMF) and the World Bank, or bilateral partners. It can also issue international sovereign bonds (like Eurobonds or Sukuks) to foreign investors.
- Central Bank Borrowing (Monetization): Historically, governments would order their central banks to literally print new money to pay for government expenses. This is highly inflationary and is now strictly prohibited or limited by law in most modern economies.
The Consequences of High Fiscal Deficits
While running a small deficit is normal, chronically high fiscal deficits can devastate an economy.
The Crowding-Out Effect: When a government borrows heavily from domestic banks to fund its deficit, it absorbs the capital that would have otherwise been lent to the private sector. Banks prefer lending to the government because it is risk-free. As a result, businesses are “crowded out” of the credit market, stifling private investment, entrepreneurship, and job creation.
The Debt Trap: If a government continually borrows just to pay off the interest on its previous loans, it falls into a sovereign debt trap. In Pakistan, a massive percentage of the Federal Board of Revenue’s (FBR) tax collection goes entirely toward debt servicing, leaving very little room for health, education, or infrastructure spending.
Inflation and Currency Devaluation: If external borrowing is not utilized for productive, export-enhancing projects, the debt burden weakens the country’s macroeconomic fundamentals. This leads to currency depreciation, which makes importing essential goods (like oil) more expensive, fueling domestic inflation.
Is a Fiscal Deficit Always Bad?
Not necessarily. According to Keynesian economic theory, a fiscal deficit can be a powerful tool for good. During an economic recession, private businesses stop investing and consumers stop spending. In this scenario, the government should intentionally run a fiscal deficit—cutting taxes and increasing spending on public infrastructure—to stimulate demand, create jobs, and pull the economy out of the slump.
The golden rule of public finance is that borrowing is justified if the funds are used for productive capital investments whose economic returns exceed the interest rate of the loan. However, borrowing to fund current expenditures—like paying government salaries or sustaining loss-making state enterprises—is universally condemned by economists.
Key Takeaways:
- A fiscal deficit occurs when government spending eclipses tax revenues.
- Deficits are financed through domestic bank borrowing or external debt.
- Public debt is the cumulative accumulation of annual fiscal deficits.
- High deficits can cause the “crowding out” of private sector investment and lead to a sovereign debt trap.
- Borrowing for infrastructure is generally acceptable; borrowing to pay salaries or debt interest is economically destructive.
Authoritative Sources & Further Reading:

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide

Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Is SPY Overvalued in September 2026? Fed Rate Hike Odds & Intrinsic Value
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
The New Executive Gold Standard: Top 10 Companies Lavishing Unprecedented Perks on CEOs and CFOs in 2025–2026
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Analysis4 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025