Business
Pakistan’s KSE-100 Nears Record Territory Even as the Trade Gap Persists

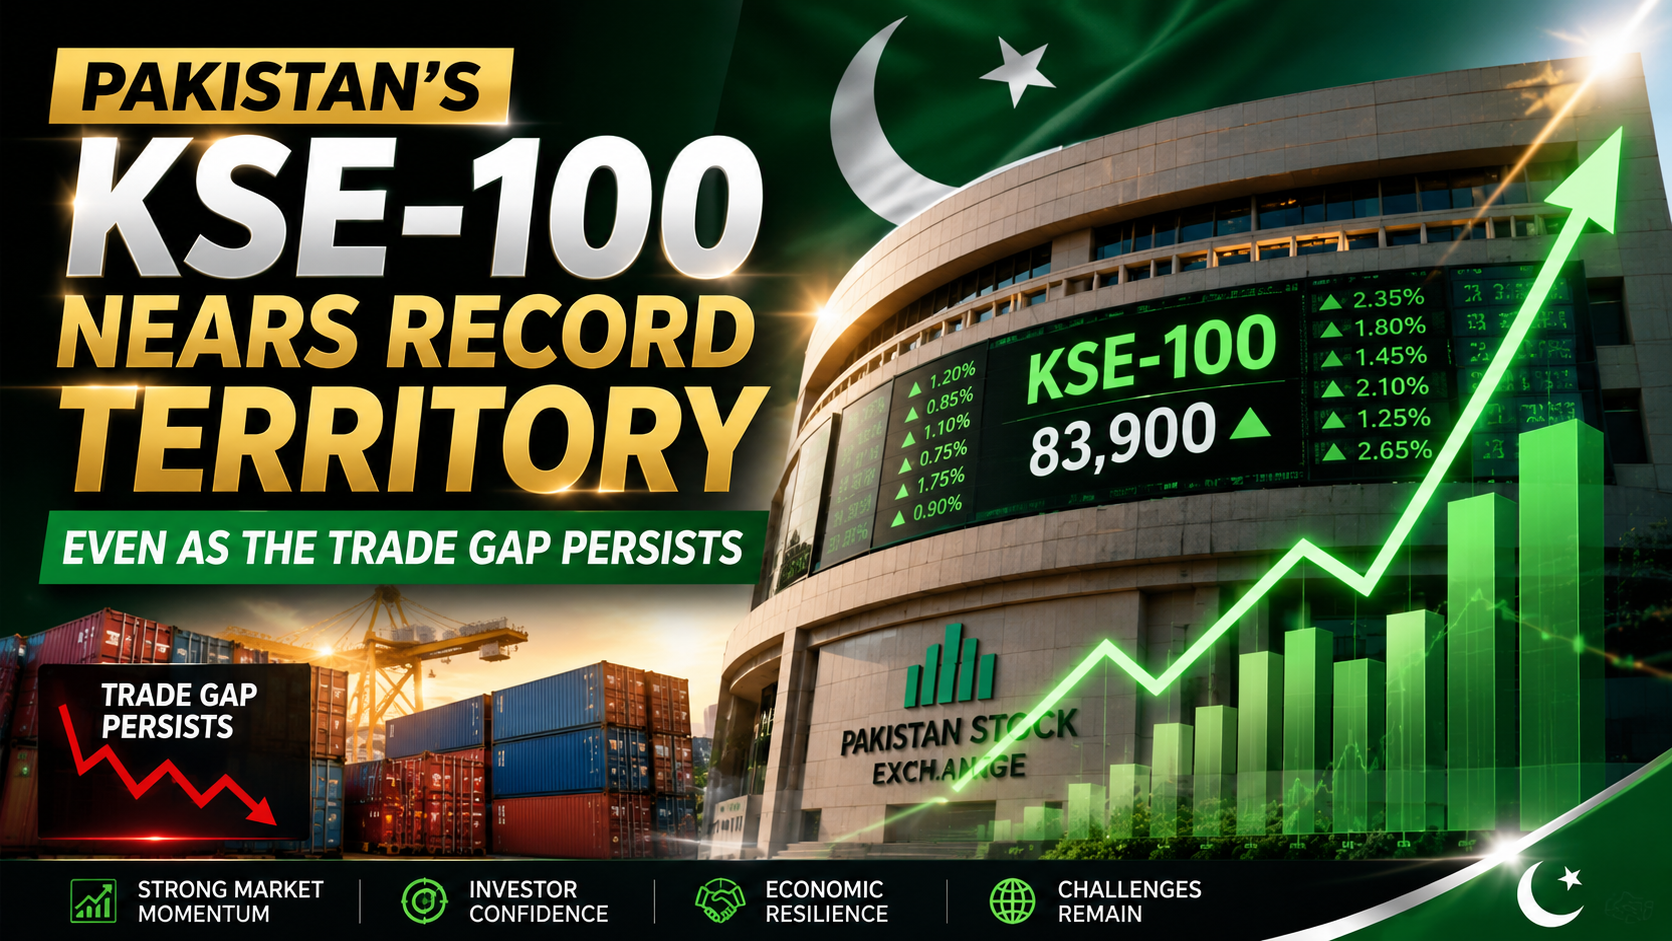
Pakistan’s KSE-100 is up nearly 19% year-on-year and within striking distance of its all-time high — even as the country’s structural trade deficit remains unresolved. Here’s the full picture.
Pakistan’s stock market is delivering one of the more remarkable emerging-market growth stories of 2026, even as the country’s underlying trade imbalance remains a live structural concern. Per Trading Economics, the KSE-100 fell to 178,213 points on August 18, 2026, losing 1.27% from the previous session — but the index remains up 18.99% compared to the same time last year and has climbed 1.30% over the past month, with the index having touched an all-time high of 189,556 points.
Key Takeaways
- The KSE-100 stood at 178,213 points on August 18, 2026, up 18.99% year-on-year, and within range of its all-time high of 189,556.
- The index has gained 10.89% over the past four weeks and 64.89% over the past twelve months by an alternate measure of the same rally.
- The rally is being driven by macro stabilisation, S&P’s credit upgrade (see Article 4), and renewed foreign portfolio inflows.
- Pakistan’s structural trade gap — imports consistently exceeding exports — remains unresolved even as equities rally.
- Historical precedent (2024’s record run) shows KSE-100 rallies have previously been fuelled by the largest foreign equity buying in a decade.
The scale of the multi-year rally is worth putting in context, because Pakistan’s equity market has been one of the standout performers globally over an extended stretch, not just a recent spike. The Trading Economics data shows the index gained 10.89% over a recent four-week window and 64.89% over the trailing twelve months, reaching successive all-time highs through late 2025 and into 2026 — from 170,249 in mid-December 2025 to 170,719 by year-end to 189,556 at its most recent peak.
This isn’t the first time Pakistan’s market has rallied on this scale, and the historical pattern is instructive. A Bloomberg report from a prior cycle describes the KSE-100 closing near a then-record high after gaining more than 30% in a single year, aided by foreign investors’ net purchases of $87 million in local shares — at the time, the highest level of foreign buying since 2014. The current rally, still building on that earlier momentum, reflects a continuation of the same foreign-inflow-driven dynamic, now reinforced by the macro stabilisation narrative detailed in Article 4: S&P’s July 22 upgrade of Pakistan’s sovereign credit rating to ‘B’ from ‘B-‘, alongside a 22-year-low fiscal deficit of 2.6% of GDP.
What the rally does not resolve, however, is Pakistan’s persistent external trade imbalance — a structural feature the equity euphoria sits somewhat uneasily alongside. Pakistan’s own national statistics, summarized on Wikipedia’s Economy of Pakistan page using official data, show exports of $40.79 billion against imports of $78.02 billion in 2025 — a nearly $37 billion gap, with petroleum imports alone totaling $15.1 billion, textiles remaining the dominant export category at $16.3 billion, and China, the UAE and the US as the country’s largest trading partners on both sides of the ledger.
Business press coverage from Business Recorder captures the tension in real time: alongside reporting on the fiscal deficit improvement and credit upgrade, the same outlet has separately reported on Pakistan’s textile mills being “caught in a contradiction they did not design” regarding their European buyers, and on the Finance Division sounding “the alarm over the persistent inflation” even as headline stabilisation indicators improve — evidence that the equity rally and the export-competitiveness challenge are running on genuinely separate tracks, both real, both simultaneously true.
Why It Matters
A market this close to record highs, riding genuine macro-improvement momentum, sends a strong signal to portfolio investors evaluating frontier and emerging markets broadly — but the persistent trade gap is the metric that ultimately determines how much of that momentum translates into durable currency stability and reduced dependence on IMF and bilateral bridge financing.
Data and Evidence
- KSE-100, August 18, 2026: 178,213 points, -1.27% daily, +18.99% YoY, +1.30% over the past month
- KSE-100 all-time high: 189,556 points
- 2025 exports: $40.79bn; 2025 imports: $78.02bn (petroleum: $15.1bn of the total)
- S&P sovereign rating: upgraded to ‘B’ from ‘B-‘ (July 22, 2026)
- FY2025-26 fiscal deficit: 2.6% of GDP, a 22-year low
Global Impact
Pakistan’s equity rally, set against a still-wide trade deficit, is a data point international frontier-market investors weigh alongside similar stabilisation-but-imbalanced stories in other IMF-program economies — a useful comparative lens for any reader tracking emerging-market risk more broadly across this batch’s coverage of Indonesia (Article 11) and other developing economies.
What Happens Next
Watch whether the KSE-100 tests its 189,556 all-time high in the coming weeks, and whether Pakistan’s upcoming trade data shows any narrowing of the export-import gap as the fiscal stabilisation narrative continues to build.
Frequently Asked Questions
Is the KSE-100 at a record high right now?
Not quite — as of August 18, 2026 it stood at 178,213, below its all-time high of 189,556, though up nearly 19% year-on-year.
What’s driving the rally?
Macro stabilisation, the S&P credit rating upgrade, a record-low fiscal deficit, and renewed foreign portfolio inflows.
Does the stock rally mean Pakistan’s economy has fully recovered?
Not entirely — the country’s structural trade deficit, with imports far exceeding exports, remains unresolved.
How big is Pakistan’s trade gap?
Roughly $37 billion in 2025, with imports of $78.02 billion against exports of $40.79 billion.
Has Pakistan’s market rallied like this before?
Yes — a similar rally in 2024 was driven by the largest foreign equity buying in a decade at that time.
The New Risk Frontier of Digital Exports
As software, AI models, digital media, and cross-border SaaS platforms dominate global trade, traditional commercial property and casualty insurance is no longer sufficient. Digital exporters face complex liabilities ranging from cross-border data privacy breaches and algorithmic bias claims to intellectual property infringement in foreign jurisdictions. In 2026, protecting a borderless digital enterprise requires specialized insurance coverage tailored to intangible asset risks.
Failing to secure robust digital export insurance can expose founders and shareholders to catastrophic lawsuits originating from overseas regulatory bodies.
Essential Coverages for Digital Export Enterprises
Cyber Liability and Algorithmic Error Coverage
If an AI model or software product exported overseas malfunctions or suffers a data breach, foreign regulators can levy severe fines under regional privacy laws. Modern cyber policies cover both regulatory defense costs and third-party damages.
Intellectual Property and Copyright Defense
Digital creators and SaaS firms operating globally are frequent targets of frivolous IP litigation in unfamiliar legal systems. Specialized IP insurance covers the exorbitant legal fees required to defend international patents and copyrights.
| Insurance Policy Type | Primary Protection Area | Target Enterprise | Average Annual Premium |
| Global Cyber Liability | Data breaches, ransomware, AI output errors | SaaS & AI Platforms | $5,000 – $18,000 |
| E&O Professional Liability | Service failures, missed deliverables | Digital Consultancies & Agencies | $3,000 – $10,000 |
| International IP Defense | Foreign copyright & patent lawsuits | Software Developers & Creators | $7,000 – $25,000 |
Securing Comprehensive Coverage: Best Practices
Navigating the insurance market for digital exports requires partnering with specialized brokers who understand intangible asset exposures.
Audit Geographic Exposures: Clearly map where your digital users reside to ensure your policy covers those specific regulatory jurisdictions.
Verify AI Exclusion Clauses: Carefully review policy wording to ensure your generative AI or automated tools are not explicitly excluded from coverage.
Maintain Incident Response Protocols: Insurers offer lower premiums to firms that demonstrate rigorous cybersecurity and data governance standards.
“Risk Management Expert Note: Your software may be intangible, but your liability in foreign markets is entirely real. Comprehensive digital export insurance is the ultimate shield for borderless growth.”
Equipping your digital export enterprise with specialized insurance safeguards your balance sheet and ensures uninterrupted global expansion.
American consumers delivered a double dose of weak data last week, and markets are still recalibrating what it means for the Federal Reserve’s next move. Retail sales fell unexpectedly in July while consumer sentiment posted its first monthly decline in three months — a combination that has pushed the odds of Fed action lower even as inflation concerns keep the central bank’s path anything but settled.
The Numbers That Moved Markets
Headline retail sales fell 0.6% in July to $763.6 billion, an unexpected decline, while core retail sales — excluding volatile categories — fell 0.3%, missing expectations on both counts. Consumer sentiment told an even starker story: the University of Michigan’s index dropped to 51.0 in August, well below the 54.5 economists had forecast — a reading low enough to raise questions about the durability of consumer spending heading into the back half of the year.
The market reaction was immediate. The dollar index fell 0.27% as the weak data reduced the probability of a September Fed rate move to roughly 32%, down from 35% the day before, according to rate-futures pricing. That move was reinforced by a broader shift in risk sentiment after President Trump appeared to step back from plans for further major military action against Iran, favouring economic pressure instead — reducing safe-haven demand for the dollar on top of the weak domestic data.
A Softer Consumer, But Not a Collapsing One
The picture is nuanced rather than uniformly gloomy. One report noted that retailers using tariff refunds to cut prices may be helping bring down inflation, adding to the broader market view that price pressures could ease even as spending cools — a combination that, if it holds, would give the Fed more room to prioritise growth support over inflation vigilance.
Corporate earnings released the same week offered a partial counterweight to the soft consumer data. Applied Materials reported third-quarter results showing that higher demand tied to artificial intelligence continued to support its business, reinforcing the now-familiar pattern in 2026 US markets: AI-linked capital spending remains robust even as traditional consumer-facing indicators soften.
Equity markets took the mixed signals in stride rather than panicking. At midday on the day of the release, the Nasdaq Composite fell 0.44%, the Dow Jones Industrial Average lost 0.21%, and the S&P 500 slipped 0.19% — modest declines that suggest investors read the data as consistent with a “soft landing” narrative rather than a recession warning.
The Fed’s Balancing Act
The weak retail and sentiment data arrived on top of an already-building case for caution at the Fed. A separate Seeking Alpha report described Fed rate-hike odds for September sliding further after the unexpected drop in retail sales and the first decline in consumer sentiment in three months, part of what the outlet called a broader raft of soft economic data across the week.
That said, the picture the Fed faces is genuinely mixed rather than one-directional. The same week’s economic briefings noted that the 10-year Treasury note yield rose 5 basis points despite the weak reports, driven by lingering inflation concerns tied in part to the elevated oil prices flowing from the Middle East conflict — the same dynamic complicating central bank calculus in the UK and across much of the developed world this year.
What It Means Heading Into September
The net effect is a Federal Reserve now navigating a genuinely two-sided risk environment: a softening domestic consumer that would normally argue for lower rates, against an energy-driven inflation risk that argues for caution. With September Fed odds now hovering in the low-to-mid 30% range for further tightening — effectively pricing a Fed on hold rather than hiking — markets appear to be betting that policymakers will prioritise the growth signal over the inflation signal, at least for now.
The coming weeks of data, particularly the next round of CPI and PCE inflation readings, are likely to be decisive in confirming or overturning that bet.
Key Takeaways
- US retail sales fell 0.6% in July, missing expectations, while core retail sales dropped 0.3%.
- Consumer sentiment fell to 51.0 in August, its first decline in three months and well below the 54.5 forecast.
- September Fed rate-hike odds fell to roughly 32% from 35% following the data.
- AI-linked corporate demand, evidenced by Applied Materials’ results, remains a bright spot even as broader consumer indicators soften.
- Treasury yields rose despite the weak data, reflecting lingering inflation concerns tied to elevated oil prices.
Frequently Asked Questions
How much did US retail sales fall in July 2026? US retail sales fell 0.6% in July to $763.6 billion, an unexpected decline, with core retail sales down 0.3%.
What happened to US consumer sentiment in August 2026? The University of Michigan consumer sentiment index dropped to 51.0 in August, its first monthly decline in three months and well below the 54.5 economists had forecast.
What are the odds of a Fed rate move in September 2026? Following the weak retail sales and sentiment data, the probability of Fed action in September fell to roughly 32%, down from 35% the previous day.
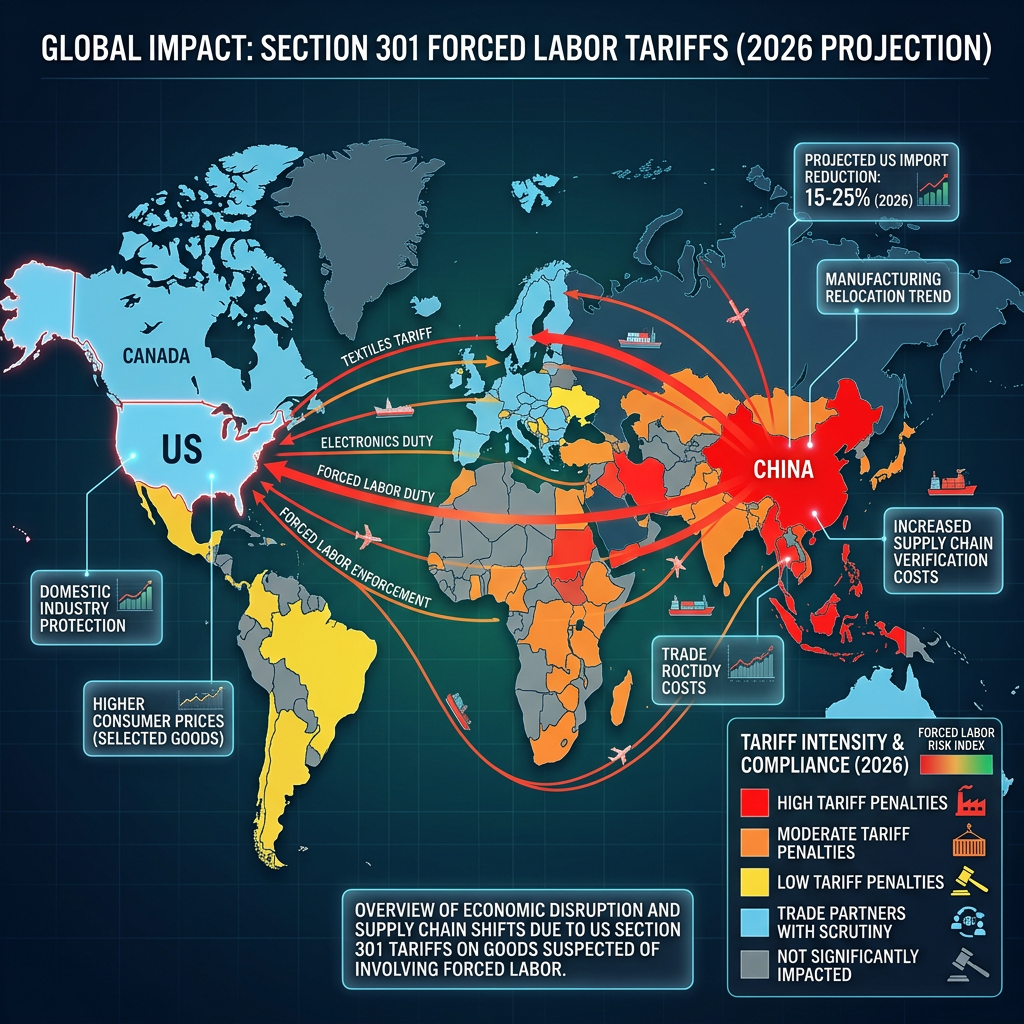
On June 2, 2026, the Office of the United States Trade Representative made a determination that quietly touches nearly every major global trading relationship at once: all 60 economies investigated for failing to adequately prohibit or enforce bans on forced-labor-produced imports were found to be acting unreasonably and burdening US commerce — with proposed tariffs of 10% to 12.5% now on the table for each (USTR).
This isn’t a fringe trade action. The 60 economies under investigation account for over 90% of all imports into the United States (Covington & Burling) — meaning this single proceeding has the potential to reshape tariff exposure across nearly the entire US import base simultaneously.
Why the Legal Framing Matters More Than the Headline
Understanding why USTR chose this specific legal pathway is essential context most coverage skips. Following a Supreme Court ruling that President Trump lacked authority to impose broad tariffs under the International Emergency Economic Powers Act (IEEPA), the administration pivoted to Section 301 of the Trade Act of 1974 — a statutory authority Congress has explicitly delegated to the executive branch for addressing unreasonable or discriminatory foreign trade practices, offering a legally sturdier foundation for longer-term tariffs than the IEEPA route that courts struck down (Covington & Burling).
That legal pivot is the real story: it signals the administration intends to build a more durable, litigation-resistant tariff architecture going forward, rather than relying on emergency powers that face ongoing court challenges.
The Two-Tier Structure, and Who Lands Where
USTR’s proposed action splits the 60 economies into two tariff tiers based on their existing forced-labor enforcement posture. Fourteen unique trading entities — including 13 countries plus the European Union — qualify for the lower 10% rate because they either maintain some form of import prohibition, operate a partial enforcement regime, or have committed to action through an Agreement on Reciprocal Trade (Green Worldwide Shipping).
The remaining 46 economies, which have neither imposed a forced labor import prohibition nor committed to establishing one, face the higher 12.5% rate.
Within the lower tier, USTR specifically identified six economies — Canada, Ecuador, the European Union, Indonesia, Mexico, and Pakistan — as jurisdictions that do maintain a forced labor import prohibition on paper, but have failed to enforce it effectively (Green Worldwide Shipping). That’s a notably diverse list spanning North America, South America, Europe, and South and Southeast Asia — underscoring that this is a genuinely global enforcement action, not one targeted at a specific region or bloc.
What USTR’s Own Report Argues Is at Stake
USTR’s underlying findings frame the economic argument in fairly direct terms: the failure to impose and enforce forced labor import prohibitions undermines global efforts to eliminate forced labor, permits firms using forced labor to produce goods at artificially lower cost, and correspondingly reduces the profitability and competitiveness of firms that don’t rely on forced labor (Green Worldwide Shipping). US Trade Representative Ambassador Jamieson Greer acknowledged some trading partners have taken initial steps — through USMCA commitments and Agreements on Reciprocal Trade — but stated each partner “must do more to ensure that trade does not perversely encourage and entrench forced labor globally” (Thompson Hine SmarTrade).
The Exemptions That Actually Determine Real-World Impact
The headline 10-12.5% figures overstate the action’s uniform impact, because the proposal includes a substantial list of carve-outs that materially change exposure depending on product category and origin. Goods listed in Annex A of the Federal Register notice — organized by Harmonized Tariff Schedule classification rather than product name — are excluded entirely. Also excluded: products already subject to Section 232 sector-specific duties, USMCA-compliant goods from Canada and Mexico, textiles and apparel entering duty-free under CAFTA-DR from Costa Rica, the Dominican Republic, El Salvador, Guatemala, Honduras, or Nicaragua, and informational materials, donations, and accompanied baggage (Covington & Burling).
USTR has also proposed a specific textile mechanism allowing a certain volume of apparel and textile imports to enter at the reduced Section 301 rate, calibrated to the volume of US-manufactured textile inputs (cotton and man-made fibers) that a given trading partner imports from the United States — effectively rewarding countries that maintain reciprocal textile trade relationships with the US (Clark Hill).
The Process Timeline and Why It Matters for Businesses Now
USTR initiated these 60 investigations on March 12, 2026, and moved through the process on what the agency has explicitly called an “accelerated timeframe.” Over the following weeks, USTR held consultations with 46 of the 60 targeted governments, received more than 450 public comments, and conducted two days of public hearings on April 28-29, 2026, with nearly 60 witnesses testifying (Green Worldwide Shipping).
The next critical dates: written public comments on the proposed actions were due July 6, 2026, and the Section 301 Committee held public hearings on the proposed action on July 7, 2026, at the US International Trade Commission in Washington (USTR). Notably, unlike prior Section 301 proceedings, USTR has not indicated it will accept post-hearing rebuttal comments in this instance — suggesting the agency intends to move toward a final determination relatively quickly once the hearing process concludes (Covington & Burling).
Crucially, no new duties are in effect yet — this remains a proposed action pending finalization. But trade law specialists are explicitly advising importers not to wait for finalization before assessing exposure, given how compressed this timeline already is compared to typical Section 301 proceedings (Clark Hill).
What Businesses Should Actually Be Doing Right Now
Trade counsel tracking this proceeding recommend a specific sequence of practical steps for import-exposed businesses. First, map exposure by country of origin and Harmonized Tariff Schedule (HTS) number specifically, pulling 2025-2026 entry data across the 60 investigated economies to identify which product lines would fall outside Annex A or other exclusions. Second, model the proposed 10% and 12.5% duties as an additional tariff layer and stress-test margin impact, pricing strategy, customer cost pass-through capacity, and import bond sufficiency. Third, don’t assume coverage or exemption without verification — confirm Section 232, USMCA, CAFTA-DR, Chapter 98, informational-materials, donation, and Annex A treatment against actual customs documentation rather than general product category assumptions (Clark Hill).
For companies with meaningful exposure, engaging directly in the comment process — either individually or through industry coalitions — remains a live opportunity to influence the final scope, exclusion list, and duty levels before USTR issues its final action.
Why This Story Deserves More Attention Than It’s Getting
Given that this single proceeding touches over 90% of US import volume, spans every major economic region this publication covers — the EU (and by extension UK-adjacent trade dynamics), Canada, Indonesia, and Pakistan are all explicitly named among the six enforcement-gap economies — and represents a structurally more durable tariff mechanism than the IEEPA approach the Supreme Court struck down, it’s genuinely surprising how little mainstream financial coverage has connected these dots into a single comprehensive picture. Most coverage to date has come from specialized trade law and customs compliance publications rather than general business media, leaving a meaningful gap for anyone trying to understand how this action might reshape global trade costs through the second half of 2026 and beyond.
The Bottom Line
The Section 301 forced labor tariff proceeding is one of the most consequential and least-covered trade policy developments of 2026, precisely because its framing — human rights enforcement rather than explicit protectionism — makes it politically harder to challenge than a straightforward tariff action, while its legal foundation under Section 301 makes it more durable than the IEEPA-based tariffs courts have already invalidated. With over 90% of US import volume affected and a compressed timeline that skipped the traditional post-hearing rebuttal period, businesses with meaningful cross-border exposure to any of the 60 named economies — which include major US trading partners across virtually every region — have a narrow and rapidly closing window to assess exposure and engage the process before these tariffs move from proposal to finalized policy.

2026 Economic Outlook: Investment Tips for Pakistani Investors

Anduril’s $6.6 Billion Submarine Shipyard Plan Explained

Life Insurance Comparison: Term vs. Whole Life and What Each Actually Costs

Stock Market Today: Nasdaq Hits Record High as Dow and S&P 500 Stumble on Middle East Diplomatic Shifts

Energy Market Spikes vs. Consumer App Data: What GasBuddy and Crude Prices Signal for Inflation

China’s FTAAP Push for APEC 2026 in Shenzhen: US Tariffs and Unite Asia-Pacific

AI Stocks Slide After Industry Leaders Call for a Development Slowdown

Singapore Stocks vs. Japan Stocks: Safe Havens in the Asian Economic Slowdown

Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street

Fiscal Deficit and Public Debt

T-Mobile’s Enterprise Push and the Evolution of Modern Corporate Mobility Solutions

Enterprise Generative AI ROI 2026: The Adoption-to-Impact Gap Explained

Climate Finance and the Economic Reality of Passing 1.5°C
Business Insurance for Digital Exports: Protecting Your Company in the AI Era
Real Estate Crash Predictions 2026: Data-Backed Regional Guide

Unrecoverable Delays: How the St. Louis Strike Crippled Boeing’s F-15EX Eagle II
What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO
How to Invest in the Anthropic IPO: Step-by-Step Guide for Retail Investors
Mario Kart 8 Deluxe 4.0.0 Patch Notes: 8-Player Split Screen & CameraPlay
Is SPY Overvalued in September 2026? Fed Rate Hike Odds & Intrinsic Value
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
The Institutional Era: A Comprehensive Cryptocurrency Investment Analysis for 2026
Real Estate Crash Predictions 2026: Data-Backed Regional Guide
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks
The Contours of 21st-Century Geopolitics Will Become Clearer in 2026: A New World Is Starting to Emerge
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
🌍 Davos 2026: The World Economic Forum Annual Meeting Sets the Stage for Global Transformation
Agentic AI in Finance: How Artificial Intelligence Is Replacing Routine Tasks on Wall Street
The New Executive Gold Standard: Top 10 Companies Lavishing Unprecedented Perks on CEOs and CFOs in 2025–2026
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Analysis4 months ago
China Economy 2026: Property Crisis, AI Investment & Export Surplus Explained
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025